12 Smart Habits That Can Help Reduce Your Business Tax Burden


Most business owners don’t want to spend more time thinking about taxes, they want to spend more time growing their business. The good news is that reducing your tax burden often isn’t about finding complicated tax strategies. It’s about building simple habits throughout the year.

Waiting until tax season to think about taxes can mean missed deductions, unnecessary penalties, and a larger tax bill than expected. Here are 12 habits that can help you keep more of what you earn while staying organized and compliant.

  1. Separate Business and Personal Finances

One of the easiest ways to improve your tax situation is to keep business and personal expenses separate. Use a dedicated business bank account and credit card so your bookkeeping stays clean and you don’t accidentally miss deductible expenses.

Why it matters: Clean financial records save time, reduce stress, and makes us tax preparers much more confident and decisive with your return.

  1. Review Your Financial Reports Every Month

Don’t wait until year-end to find out how your business is performing. Set aside time each month to review your Profit & Loss statement, cash flow, and major expenses.

Why it matters: Monthly reviews help you identify opportunities to reduce taxes before it’s too late to act.

  1. Keep Track of Every Business Expense

Small expenses add up over the course of a year. Software subscriptions, office supplies, marketing costs, professional memberships, and business meals may all be deductible when properly documented.

Common mistake: Waiting until tax season to search for receipts usually means some deductions get lost.

  1. Pay Estimated Taxes on Time

Many business owners are required to make quarterly estimated tax payments. Missing these deadlines can result in penalties and interest.

Planning ahead helps spread your tax payments throughout the year instead of facing one large surprise.

  1. Contribute to Retirement Accounts

Retirement plans can do more than prepare you for the future, they may also reduce your taxable income today.

Depending on your business structure, there may be several retirement plan options available that provide valuable tax benefits.

  1. Track Business Mileage

If you use your personal vehicle for business, keep an accurate mileage log throughout the year.

Trying to recreate mileage months later isn’t just difficult, it may also reduce the accuracy of your records.

  1. Don’t Overlook Home Office Expenses

If you legitimately qualify for the home office deduction, keeping good records is essential. Expenses such as utilities, internet, insurance, and maintenance may qualify depending on your situation.

Good documentation makes all the difference.

  1. Plan Major Purchases Before Year-End

Thinking about buying equipment, upgrading computers, or investing in new software?

The timing of these purchases can affect your tax liability. Planning ahead may allow you to maximize available deductions while still making smart business decisions.

  1. Meet With Your CPA Before Tax Season

One of the biggest mistakes business owners make is waiting until tax season to ask tax questions.

A year-end planning meeting gives you time to discuss strategies such as:

  • Managing taxable income
  • Retirement contributions
  • Equipment purchases
  • Estimated tax payments
  • Potential tax credits

By the time your tax return is being prepared, many planning opportunities have already passed.

  1. Keep Your Bookkeeping Current

Accurate bookkeeping isn’t just for tax returns; it’s one of the best management tools a business owner has.

When your financial records are current, you can:

  • Make better business decisions
  • Identify unnecessary spending
  • Prepare for tax season with confidence
  • Reduce the likelihood of costly mistakes
  1. Stay Organized Throughout the Year

Instead of scrambling every spring, create simple weekly or monthly routines.

Examples include:

  • Filing receipts
  • Reconciling bank accounts
  • Reviewing invoices
  • Recording payroll
  • Organizing important tax documents

A little consistency goes a long way.

  1. Ask Before You Make Big Decisions

Hiring employees, purchasing equipment, expanding locations, or changing your business structure can all have tax consequences.

A quick conversation before making a major decision often uncovers opportunities that aren’t available afterward.

The Bottom Line

The business owners who consistently reduce their tax burden aren’t necessarily the ones with the biggest budgets or the most complex businesses. They’re the ones who plan ahead.

Good tax planning starts long before tax season. By building a few simple habits into your routine, you’ll be better prepared to claim every deduction you’re entitled to, avoid unnecessary surprises, and make more informed financial decisions throughout the year.

At Wilson Rogers, we believe tax planning should be proactive, not reactive. Our goal is to help business owners understand what their numbers mean, avoid common pitfalls, and make confident decisions that support long-term success. When taxes become part of your year-round business strategy, you’re in a much stronger position to keep more of what you’ve worked hard to earn.
A Guide to the “No Tax on Overtime” Provision in the OBBA

Understanding the “No Tax on Overtime” Provision Under the One Big Beautiful Act (OBBA)

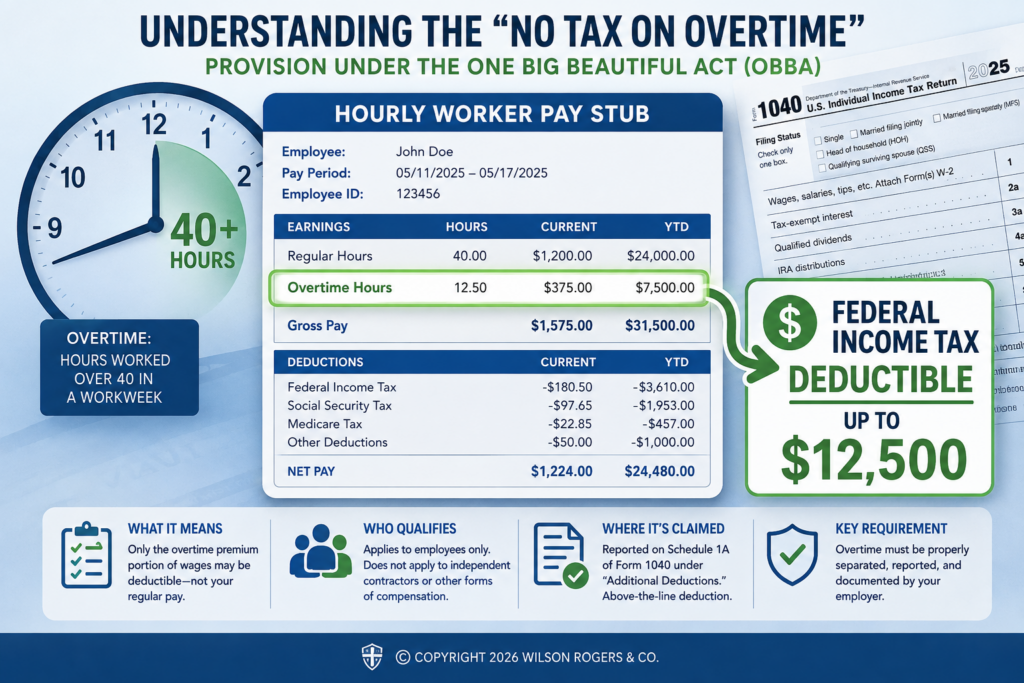
One of the more commonly misunderstood changes introduced under the One Big Beautiful Act (OBBA) is the “no tax on overtime” provision. At first glance, the name suggests that overtime pay is no longer taxable. In reality, that is not the case. This provision does not eliminate tax on overtime wages. Instead, it creates a limited deduction that applies only to a specific portion of overtime compensation, and only when it is properly identified, calculated, and reported.

What “No Tax on Overtime” Actually Means

Under OBBA, the provision applies only to the overtime premium portion of wages. This is the additional amount paid above an employee’s regular hourly rate for hours worked beyond standard thresholds. Regular wages remain fully taxable, only the premium portion may qualify for the deduction. Overtime is generally defined under FLSA (Fair Labor Standards Act) rules, typically for hours worked over 40 in a workweek. This provision applies strictly to employees and does not extend to independent contractors or other forms of compensation such as bonuses. It is also important to understand that simply working overtime is not enough to qualify. The overtime must be separated into its regular rate and overtime premium, and only the premium portion is eligible for consideration.

Limits and Income Phase-Out Rules

Like most tax provisions, the overtime deduction includes strict limitations. The deduction for qualified overtime compensation is capped at $12,500 per year for most filers and $25,000 per year for Married Filing Jointly.

The benefit also phases out based on income. The phase-out begins when adjusted gross income exceeds $150,000 for Single, Head of Household, and Married Filing Separately, and $300,000 for Married Filing Jointly. As income increases beyond those thresholds, the deduction is gradually reduced until it is fully phased out.

Employers are required to separately account for qualified overtime compensation. This reporting requirement is part of the framework that ensures proper identification of eligible amounts.

How Overtime Is Reported

Even with this provision, overtime reporting has not changed at its core. On Form W-2, total wages are still reported in Box 1, which includes both regular and overtime earnings. However, the overtime premium portion must now be separately identified using updated IRS wage codes or reporting fields.

On Form 1040, overtime income is still included in gross wages. The key difference is that the tax benefit is not applied at the wage level. Instead, it is calculated later in the return as an adjustment to income.

Where the Deduction Is Claimed

The deduction is reported on Schedule 1A of Form 1040 under “Additional Deductions.” This is a new OBBA-related line item beginning in 2025. This is considered an above-the-line deduction, meaning it reduces adjusted gross income before either the standard deduction or itemized deductions are applied. This structure is significant because it can affect taxable income more broadly than a typical below-the-line deduction.

Documentation and Verification Requirements

Proper documentation is a key part of this provision. The IRS will expect clear support showing how overtime was calculated and separated from regular wages.

Pay stubs alone that simply label overtime are not sufficient. The underlying breakdown must clearly show regular pay versus overtime premium amounts. Verification should be based on employer payroll records, which serve as the primary source of truth, followed by pay stubs as supporting documentation. Employee statements or estimates are not reliable on their own and should not be used in place of formal records. Consistency across all documentation is essential. The classification of overtime must match across payroll systems, W-2 reporting, and any supporting forms used in the return.

Final Takeaway

The “no tax on overtime” provision under OBBA does not eliminate taxation on overtime earnings. Instead, it provides a limited deduction that applies only to the overtime premium portion of wages and only for taxpayers who meet specific income and reporting requirements.

While the provision may offer meaningful tax relief for eligible individuals, it depends heavily on accurate payroll reporting, proper classification of wages, and strong documentation. As with many tax changes, the details determine the outcome, and precision in reporting is essential for compliance.

What is Circular 230 & Why Taxpayers Can Feel at Ease

Ever feel nervous handing over your tax documents to someone else? You’re not alone. Every year, taxpayers trust preparers with their most personal financial information—income, investments, dependents, and more—hoping everything is done correctly.

The good news? There’s already a safeguard in place to protect you and hold your preparer accountable. It’s called Circular 230, and it’s one of the most important—but least known—rules in the tax world.

What Exactly is Circular 230?

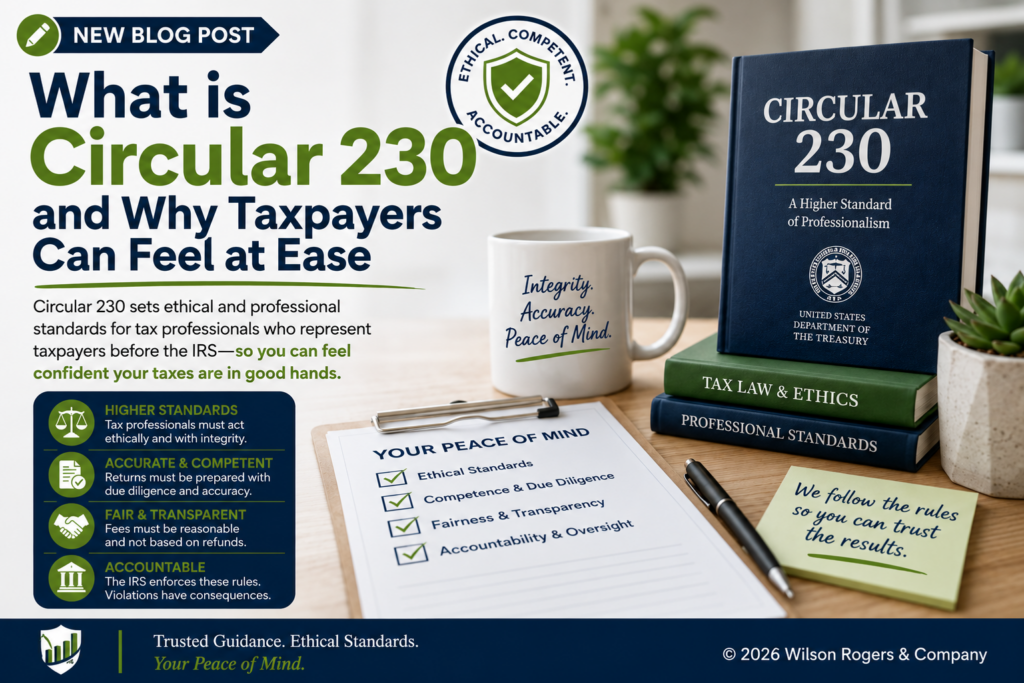
Circular 230 is an official publication from the U.S. Department of the Treasury. It sets the rules and ethical standards for professionals who represent taxpayers before the IRS.

This includes CPAs, Enrolled Agents (EAs), tax attorneys, and other individuals authorized to practice before the IRS. Essentially, if someone is legally allowed to handle your taxes, they must follow Circular 230.

Think of it as the IRS’s code of conduct for tax professionals. It ensures that your preparer acts with integrity, honesty, and professionalism—giving you confidence that your taxes are in capable hands.

How Circular 230 Protects You

Circular 230 exists not just for professionals, but for taxpayers. It ensures that anyone handling your return is competent, ethical, and accountable.

First, it holds preparers to a higher standard. They must act ethically, avoid conflicts of interest, and exercise due diligence. Misleading clients, making unrealistic promises, or taking risky tax positions is not allowed.

Second, it requires accuracy and competence. Tax professionals must verify information and ensure returns are correct. This reduces the risk of errors, penalties, or audits from sloppy or negligent work.

Third, it promotes fairness. Circular 230 regulates fees in many cases, preventing unreasonable or contingent charges. You can trust you’re being charged fairly, not based on the size of your refund.

Finally, it enforces accountability. The IRS Office of Professional Responsibility monitors compliance, and a preparer who acts unethically can be suspended or barred from practice. That oversight means you’re not on your own if something goes wrong.

Why This Matters to You

Working with a preparer covered under Circular 230—like a CPA, EA, or tax attorney—gives you peace of mind. They are legally bound by federal ethics and practice standards, required to act in your best interest, and can face real consequences for misconduct.

Put simply, Circular 230 gives you a safety net every time you file. Your preparer is trained to handle your taxes responsibly, accurately, and ethically.

Your Role as a Taxpayer

Circular 230 protects you, but you still play a key role in keeping your tax process safe. Always confirm your preparer’s credentials, review your return before signing, keep copies of your records, and provide accurate information. Being proactive helps protect both you and your preparer.

Final Thoughts

Most taxpayers never think about Circular 230, but it works quietly in the background to keep the tax system ethical, fair, and accountable. It’s why you can hand over your financial documents to a qualified preparer and trust that they are required to act professionally.

Behind every trusted tax professional is a set of IRS-enforced rules designed to protect you. Circular 230 gives taxpayers peace of mind, knowing their preparer is qualified, ethical, and committed to doing things the right way—every single time.


Go to Top