12 Smart Habits That Can Help Reduce Your Business Tax Burden


Most business owners don’t want to spend more time thinking about taxes, they want to spend more time growing their business. The good news is that reducing your tax burden often isn’t about finding complicated tax strategies. It’s about building simple habits throughout the year.

Waiting until tax season to think about taxes can mean missed deductions, unnecessary penalties, and a larger tax bill than expected. Here are 12 habits that can help you keep more of what you earn while staying organized and compliant.

  1. Separate Business and Personal Finances

One of the easiest ways to improve your tax situation is to keep business and personal expenses separate. Use a dedicated business bank account and credit card so your bookkeeping stays clean and you don’t accidentally miss deductible expenses.

Why it matters: Clean financial records save time, reduce stress, and makes us tax preparers much more confident and decisive with your return.

  1. Review Your Financial Reports Every Month

Don’t wait until year-end to find out how your business is performing. Set aside time each month to review your Profit & Loss statement, cash flow, and major expenses.

Why it matters: Monthly reviews help you identify opportunities to reduce taxes before it’s too late to act.

  1. Keep Track of Every Business Expense

Small expenses add up over the course of a year. Software subscriptions, office supplies, marketing costs, professional memberships, and business meals may all be deductible when properly documented.

Common mistake: Waiting until tax season to search for receipts usually means some deductions get lost.

  1. Pay Estimated Taxes on Time

Many business owners are required to make quarterly estimated tax payments. Missing these deadlines can result in penalties and interest.

Planning ahead helps spread your tax payments throughout the year instead of facing one large surprise.

  1. Contribute to Retirement Accounts

Retirement plans can do more than prepare you for the future, they may also reduce your taxable income today.

Depending on your business structure, there may be several retirement plan options available that provide valuable tax benefits.

  1. Track Business Mileage

If you use your personal vehicle for business, keep an accurate mileage log throughout the year.

Trying to recreate mileage months later isn’t just difficult, it may also reduce the accuracy of your records.

  1. Don’t Overlook Home Office Expenses

If you legitimately qualify for the home office deduction, keeping good records is essential. Expenses such as utilities, internet, insurance, and maintenance may qualify depending on your situation.

Good documentation makes all the difference.

  1. Plan Major Purchases Before Year-End

Thinking about buying equipment, upgrading computers, or investing in new software?

The timing of these purchases can affect your tax liability. Planning ahead may allow you to maximize available deductions while still making smart business decisions.

  1. Meet With Your CPA Before Tax Season

One of the biggest mistakes business owners make is waiting until tax season to ask tax questions.

A year-end planning meeting gives you time to discuss strategies such as:

  • Managing taxable income
  • Retirement contributions
  • Equipment purchases
  • Estimated tax payments
  • Potential tax credits

By the time your tax return is being prepared, many planning opportunities have already passed.

  1. Keep Your Bookkeeping Current

Accurate bookkeeping isn’t just for tax returns; it’s one of the best management tools a business owner has.

When your financial records are current, you can:

  • Make better business decisions
  • Identify unnecessary spending
  • Prepare for tax season with confidence
  • Reduce the likelihood of costly mistakes
  1. Stay Organized Throughout the Year

Instead of scrambling every spring, create simple weekly or monthly routines.

Examples include:

  • Filing receipts
  • Reconciling bank accounts
  • Reviewing invoices
  • Recording payroll
  • Organizing important tax documents

A little consistency goes a long way.

  1. Ask Before You Make Big Decisions

Hiring employees, purchasing equipment, expanding locations, or changing your business structure can all have tax consequences.

A quick conversation before making a major decision often uncovers opportunities that aren’t available afterward.

The Bottom Line

The business owners who consistently reduce their tax burden aren’t necessarily the ones with the biggest budgets or the most complex businesses. They’re the ones who plan ahead.

Good tax planning starts long before tax season. By building a few simple habits into your routine, you’ll be better prepared to claim every deduction you’re entitled to, avoid unnecessary surprises, and make more informed financial decisions throughout the year.

At Wilson Rogers, we believe tax planning should be proactive, not reactive. Our goal is to help business owners understand what their numbers mean, avoid common pitfalls, and make confident decisions that support long-term success. When taxes become part of your year-round business strategy, you’re in a much stronger position to keep more of what you’ve worked hard to earn.
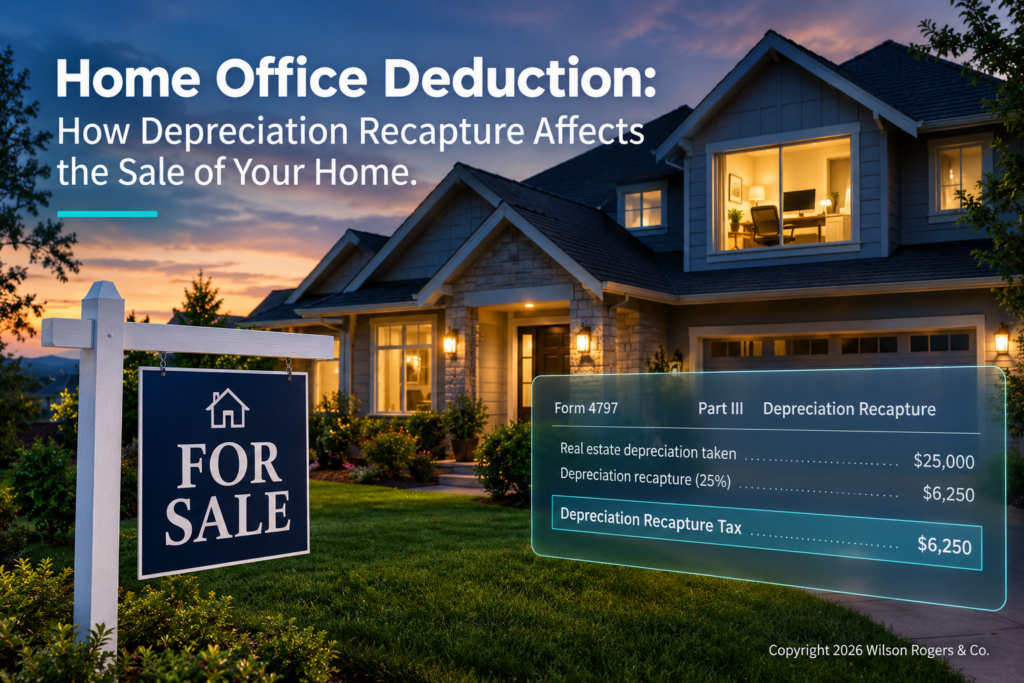
Home Office Deduction: How Depreciation Recapture Affects the Sale of Your Home


Using part of your home for business can provide meaningful tax savings through the home office deduction. Homeowners and renters alike can benefit from this deduction, but if you later sell your home, there’s an important consideration: depreciation recapture. Understanding how this works can help you plan ahead and avoid surprises at tax time.

Requirements for the Home Office Deduction

To claim the home office deduction, two key requirements must be met. First, the space must be used regularly and exclusively for business purposes. A home office cannot double as a guest room, den, or entertainment space. Occasional or incidental business use, such as quarterly meetings, does not qualify. Second, your home must serve as your principal place of business. Even if you conduct work elsewhere, you may qualify if you use your home substantially and regularly. Separate structures, such as garages, studios, or barns, can also qualify if they are used exclusively for business.

How to Claim the Deduction

Deductions are generally based on the percentage of your home used for business. There are two calculation methods. The simplified method allows a deduction of $5 per square foot, up to 300 square feet, for a maximum of $1,500. Depreciation is not claimed under this method, which means no recapture tax applies when you sell, and recordkeeping is minimal.

The regular (actual expense) method calculates the actual expenses of operating your home, including mortgage interest, utilities, insurance, repairs, and depreciation. Expenses are allocated based on the business-use portion of your home, and deductions are reported on IRS Form 8829. While this method often results in larger deductions each year, it triggers depreciation recapture when you sell your home.

Where you report the deduction depends on your business type. Self-employed individuals typically report it on Schedule C, Line 30. Employees may report eligible expenses on Schedule A as itemized deductions (if allowed). Partnerships, LLCs, and S-Corps usually handle the deduction through accountable plans or entity-level reimbursements.

Depreciation Recapture Explained

Depreciation reduces your taxable income in the years you claim it, but when you sell your home, the IRS requires you to recapture the depreciation for the business-use portion. Depreciation recapture is taxed at a maximum rate of 25%, separate from long-term capital gains, which are generally taxed at 15%. Even if you didn’t claim all allowable depreciation, the IRS requires recapture of any portion that could have been claimed.

Example:

  • Home purchase price: $300,000
  • Business-use portion: 10%
  • Depreciation claimed: $10,000
  • Sale price: $500,000

Recapture: $10,000 taxed at up to 25%
Remaining gain: $190,000 may qualify for the capital gains exclusion ($250,000 single / $500,000 married filing jointly)

Capital Gains Exclusion and the Home Office

The capital gains exclusion allows homeowners to exclude up to $250,000 (single) or $500,000 (married filing jointly) of gain on the sale of their primary residence if they owned and lived in the home for at least two of the last five years. If your office is inside the home, the exclusion generally applies to the entire home, but depreciation recapture still applies.

If your office is in a separate structure, the IRS treats it as a separate dwelling unit. You must meet ownership and use requirements for both the home and the structure to apply the exclusion. If these requirements are not met, gains from the office portion are fully taxable, including depreciation recapture at 25% and any additional gain at 15%.

Planning Strategies Before Selling

Business owners can take steps to minimize the impact of depreciation recapture. If the office is in a separate structure, consider not claiming home office deductions for at least two years before selling to maximize the exclusion on the full property. If the office is inside your home, continue claiming deductions, since recapture is required regardless of whether you claimed them.

Maintaining detailed records is essential. Keep track of expenses, depreciation, and the square footage of your office. Accurate documentation ensures correct calculation of recapture and can help prevent errors or audits.

Why Depreciation Recapture Isn’t a Penalty

It’s important to understand that depreciation recapture is not a penalty. It simply balances the tax benefit you’ve already received. Depreciation reduces taxable income over the years, providing real savings, and recapture ensures the IRS taxes the portion of gain already offset by those deductions. Even with recapture, the home office deduction remains a valuable tool for business owners, helping offset real expenses and reflecting the dual purpose of your home as both a residence and a workspace.


Who do I issue a 1099-Misc to?

****UPDATE as of 01/01/21****

The information below was originally written when money paid to independent contractors was reported on Form 1099-MISC.  As a result of the The Protecting Americans from Tax Hikes Act of 2015 (the PATH Act), independent contractor payments are now reported via Form 1099-NEC effective tax year 2020 (being filed in 2021). The deadline for filing remains January 31st.

While most of the information below for Form 1099-MISC applies to Form 1099-NEC and generally is still relevant, please refer to the YouTube video below for instructions on how to complete Form 1099-NEC.

******** Original Post Begins Below **********

If you employ an independent contractor in your trade or business, you are obligated to report their earnings to them and the IRS.  This is typically done via the IRS form 1099-MISC.  But just who is supposed to receive this form, when is it due and what are the penalties if it’s not filed on time?

Who Receives Form 1099-MISC

Form 1099 goes out to independent contractors if you pay them $600 or more to do work for your company during the tax year.  Additionally, those whom you pay at least $10 in royalties or broker payments in lieu of dividends or tax-exempt interest should also receive a 1099.

Taxpayers should note that if you earned less than $600 and you don’t get a 1099, this doesn’t mean you don’t have to report the income.  All income (it doesn’t matter if it’s $1) is taxable and should/must be reported.

In addition to individuals, you must also send a 1099 to the following if you paid them for doing work:

  • Businesses that file on form 1040 Schedule C (i.e. sole proprietors/self employed)
  • Single member LLCs, as they are considered disregarded entities (DREs) and also file on Sch C
  • Partnerships or Multimember LLCs as they essentially file the same return as a partnership

However, there are some instances in which you don’t need to issue a 1099-MISC.  These exceptions include:

  • Suppliers of merchandise, telegrams, telephone, freight, storage, and similar items, with the exception of those who deal in fish or other aquatic life
  • Corporations (e.g. those who’s names contain Corporation, Company, Incorporated, Limited, Corp., Co., Inc. or Ltd.) are also exempt from 1099 requirements, with the exception of those you pay for medical or health care, or law firms that you’ve hired for legal services
  • Those corporations that have filed a S-Corp election with the IRS
  • Tax-exempt organizations or to American or foreign governments

Need the specifics on who is exempt and who isn’t and don’t mind reading the Internal Revenue Code?  Check out section Treasury Regulations, Subchapter A, Sec. 1.6049-4(c)(1)(ii) where it talks about a corporation, as defined in section 7701(a)(3).

When Is Form 1099 Due?

Generally you must furnish a copy of form 1099-MISC to the recipient by January 31st of the year following when the payments were made.   If you are reporting payments in boxes 8 or 14, then you have until February 15th of the year following when the payments were made.

In addition to the recipient, you must also send a copy to the IRS (along with Form 1096) by January 31st IF you are reporting amounts in Box 7 for Nonemployee Compensation.  If you are reporting amounts in any other box:

  • You must submit it by February 28th of the year following when the payments were made if you are sending it via paper
  • If you are submitting everything electronically, then you have until March 31st of the year following payment.

What are the penalties for filing late?

If you fail to file a correct information return by the due date and you cannot show reasonable cause, you may be subject to a penalty. The amount of the penalty is based on when you file the correct information return. Currently, the penalty is:

  • $50 per information return if you correctly file within 30 days; maximum penalty $532,000 per year ($186,000 for small businesses)
  • $100 per information return if you correctly file more than 30 days after the due date but by August 1; maximum penalty $1,596,500 per year ($532,000 for small businesses)
  • $260 per information return if you file after August 1 or you do not file required information returns; maximum penalty $3,193,000 per year ($1,064,000 for small businesses)

Obtaining the information needed to file Form 1099

To ensure that you issue a correct 1099 to the recipient, complete Form W-9, Request for Taxpayer Identification and Certification.  The W-9 includes the individual or businesses legal name, tax ID number, address and their signature attesting to the correctness of the content. You will then use this information to create the 1099 and send it to the IRS.

Do you have 1099s that you need to file?  Shoot us an email at the address below or give us a call at 773-239-8850.  Our filing services are extremely affordable (as low as $10/form) and not only will your documents be filed with the IRS, SSA and state, they can also be mailed to the recipient!

Go to Top