12 Smart Habits That Can Help Reduce Your Business Tax Burden


Most business owners don’t want to spend more time thinking about taxes, they want to spend more time growing their business. The good news is that reducing your tax burden often isn’t about finding complicated tax strategies. It’s about building simple habits throughout the year.

Waiting until tax season to think about taxes can mean missed deductions, unnecessary penalties, and a larger tax bill than expected. Here are 12 habits that can help you keep more of what you earn while staying organized and compliant.

  1. Separate Business and Personal Finances

One of the easiest ways to improve your tax situation is to keep business and personal expenses separate. Use a dedicated business bank account and credit card so your bookkeeping stays clean and you don’t accidentally miss deductible expenses.

Why it matters: Clean financial records save time, reduce stress, and makes us tax preparers much more confident and decisive with your return.

  1. Review Your Financial Reports Every Month

Don’t wait until year-end to find out how your business is performing. Set aside time each month to review your Profit & Loss statement, cash flow, and major expenses.

Why it matters: Monthly reviews help you identify opportunities to reduce taxes before it’s too late to act.

  1. Keep Track of Every Business Expense

Small expenses add up over the course of a year. Software subscriptions, office supplies, marketing costs, professional memberships, and business meals may all be deductible when properly documented.

Common mistake: Waiting until tax season to search for receipts usually means some deductions get lost.

  1. Pay Estimated Taxes on Time

Many business owners are required to make quarterly estimated tax payments. Missing these deadlines can result in penalties and interest.

Planning ahead helps spread your tax payments throughout the year instead of facing one large surprise.

  1. Contribute to Retirement Accounts

Retirement plans can do more than prepare you for the future, they may also reduce your taxable income today.

Depending on your business structure, there may be several retirement plan options available that provide valuable tax benefits.

  1. Track Business Mileage

If you use your personal vehicle for business, keep an accurate mileage log throughout the year.

Trying to recreate mileage months later isn’t just difficult, it may also reduce the accuracy of your records.

  1. Don’t Overlook Home Office Expenses

If you legitimately qualify for the home office deduction, keeping good records is essential. Expenses such as utilities, internet, insurance, and maintenance may qualify depending on your situation.

Good documentation makes all the difference.

  1. Plan Major Purchases Before Year-End

Thinking about buying equipment, upgrading computers, or investing in new software?

The timing of these purchases can affect your tax liability. Planning ahead may allow you to maximize available deductions while still making smart business decisions.

  1. Meet With Your CPA Before Tax Season

One of the biggest mistakes business owners make is waiting until tax season to ask tax questions.

A year-end planning meeting gives you time to discuss strategies such as:

  • Managing taxable income
  • Retirement contributions
  • Equipment purchases
  • Estimated tax payments
  • Potential tax credits

By the time your tax return is being prepared, many planning opportunities have already passed.

  1. Keep Your Bookkeeping Current

Accurate bookkeeping isn’t just for tax returns; it’s one of the best management tools a business owner has.

When your financial records are current, you can:

  • Make better business decisions
  • Identify unnecessary spending
  • Prepare for tax season with confidence
  • Reduce the likelihood of costly mistakes
  1. Stay Organized Throughout the Year

Instead of scrambling every spring, create simple weekly or monthly routines.

Examples include:

  • Filing receipts
  • Reconciling bank accounts
  • Reviewing invoices
  • Recording payroll
  • Organizing important tax documents

A little consistency goes a long way.

  1. Ask Before You Make Big Decisions

Hiring employees, purchasing equipment, expanding locations, or changing your business structure can all have tax consequences.

A quick conversation before making a major decision often uncovers opportunities that aren’t available afterward.

The Bottom Line

The business owners who consistently reduce their tax burden aren’t necessarily the ones with the biggest budgets or the most complex businesses. They’re the ones who plan ahead.

Good tax planning starts long before tax season. By building a few simple habits into your routine, you’ll be better prepared to claim every deduction you’re entitled to, avoid unnecessary surprises, and make more informed financial decisions throughout the year.

At Wilson Rogers, we believe tax planning should be proactive, not reactive. Our goal is to help business owners understand what their numbers mean, avoid common pitfalls, and make confident decisions that support long-term success. When taxes become part of your year-round business strategy, you’re in a much stronger position to keep more of what you’ve worked hard to earn.
Ethical Standards for Tax Preparers

In the complicated world of taxation, where financial responsibilities intersect with legal obligations, the role of a tax preparer is both crucial and delicate. As tax season approaches, it becomes increasingly important to shine a light on the ethical standards that guide these financial professionals. In this blog post, we explore the essential ethical principles that should govern the conduct of tax preparers, ensuring not only compliance with the law but also the maintenance of trust and integrity in their crucial role.

There are several key ethical principles that tax preparers should follow, these includes:

  1. Confidentiality: the preparer has the responsibility to keep all of their client’s information confidential, even if the relationship ends, they must continue to follow this. The only time they should disclose information is with the client’s consent or when it is required by the law.


  1. Competence: they should also keep up to date with the latest tax laws and regulations in order to stay competent in their specific field. This includes providing services that they are qualified to provide and should refer clients to other professionals if they aren’t prepared.


  1. Integrity: tax preparers must be honest, credible, and trustworthy as it is their obligation to protect and enhance the trust of the client. This includes avoiding any conflicts of interest and not engaging in any activity that could damage their own reputation or profession.


  1. Due Diligence: Tax preparers should perform due diligence on their client information and should never prepare returns that are inaccurate or incomplete knowingly.


  1. Independence: tax preparers should not allow their personal interest to interfere with their personal judgment. This includes any relationship that could compromise their objectivity or integrity.

In addition to these general ethical principles, they must also comply with specific professional standards and regulations. They may vary depending on the jurisdiction in which the tax preparer is practicing and the specific area they are focused in. However, some of the most common standards and regulations include:

  • Circular 230: These are a set of regulations issues by the US department of the Treasury that govern the practice of tax law. This also requires tax preparers to be competent, honest, and ethical in their dealings with clients.
  • AICPA Statements on Standards for Tax Services: These are a set of standards issued by the American Institute of Certified Public Accountants that govern the preparation of tax returns. These standards require tax preparers to perform due diligence in order to disclose any material uncertainties and to avoid taking unreasonable positions.
  • National Associations of Tax Professionals (NATP) Code of Ethics: this is made up of the code of ethics that are applied to all members of the NATP. The NATP Code of Ethics requires members to be honest, competent, and ethical when it comes to working with their clients.

If a tax preparer engages in any unethical conduct, they can potentially face a number of consequences, such as:

  • Loss of professional license
  • Fines and penalties
    • These include fines up to $100,000 or $500,000 in the case of a corporation
  • Criminal Chargers
    • Imprisonment for up to three years with felony or misdemeanors being on your record

These consequences vary for each situation such as the penalty being less expensive as we mentioned or imprisonment being less time. Whatever the case maybe they are nothing to take lightly.

In conclusion, ethical standards are paramount for tax preparers as they navigate the complicated landscape of taxation. These standards, encompassing confidentiality, competence, integrity, due diligence, and independence, form the bedrock of responsible and honest conduct. Reinforced by specific professional standards, violations can lead to severe consequences, including the loss of professional licenses, substantial fines, and criminal charges. As tax preparers approach the challenges of tax season, faithfulness to these ethical principles is not only an expectation but an obligation. Upholding these standards is crucial for maintaining trust, safeguarding reputations, and preserving the integrity of the financial profession. In essence, ethical conduct is not just a guideline; it is an indispensable compass that guides tax preparers towards principled and responsible tax preparation.

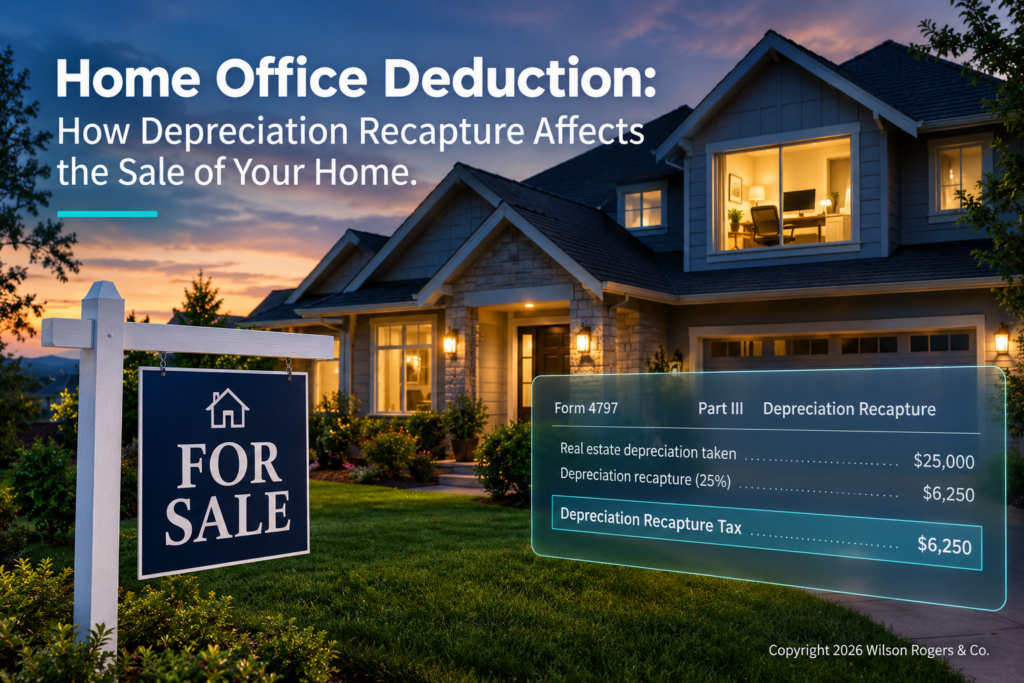
Home Office Deduction: How Depreciation Recapture Affects the Sale of Your Home


Using part of your home for business can provide meaningful tax savings through the home office deduction. Homeowners and renters alike can benefit from this deduction, but if you later sell your home, there’s an important consideration: depreciation recapture. Understanding how this works can help you plan ahead and avoid surprises at tax time.

Requirements for the Home Office Deduction

To claim the home office deduction, two key requirements must be met. First, the space must be used regularly and exclusively for business purposes. A home office cannot double as a guest room, den, or entertainment space. Occasional or incidental business use, such as quarterly meetings, does not qualify. Second, your home must serve as your principal place of business. Even if you conduct work elsewhere, you may qualify if you use your home substantially and regularly. Separate structures, such as garages, studios, or barns, can also qualify if they are used exclusively for business.

How to Claim the Deduction

Deductions are generally based on the percentage of your home used for business. There are two calculation methods. The simplified method allows a deduction of $5 per square foot, up to 300 square feet, for a maximum of $1,500. Depreciation is not claimed under this method, which means no recapture tax applies when you sell, and recordkeeping is minimal.

The regular (actual expense) method calculates the actual expenses of operating your home, including mortgage interest, utilities, insurance, repairs, and depreciation. Expenses are allocated based on the business-use portion of your home, and deductions are reported on IRS Form 8829. While this method often results in larger deductions each year, it triggers depreciation recapture when you sell your home.

Where you report the deduction depends on your business type. Self-employed individuals typically report it on Schedule C, Line 30. Employees may report eligible expenses on Schedule A as itemized deductions (if allowed). Partnerships, LLCs, and S-Corps usually handle the deduction through accountable plans or entity-level reimbursements.

Depreciation Recapture Explained

Depreciation reduces your taxable income in the years you claim it, but when you sell your home, the IRS requires you to recapture the depreciation for the business-use portion. Depreciation recapture is taxed at a maximum rate of 25%, separate from long-term capital gains, which are generally taxed at 15%. Even if you didn’t claim all allowable depreciation, the IRS requires recapture of any portion that could have been claimed.

Example:

  • Home purchase price: $300,000
  • Business-use portion: 10%
  • Depreciation claimed: $10,000
  • Sale price: $500,000

Recapture: $10,000 taxed at up to 25%
Remaining gain: $190,000 may qualify for the capital gains exclusion ($250,000 single / $500,000 married filing jointly)

Capital Gains Exclusion and the Home Office

The capital gains exclusion allows homeowners to exclude up to $250,000 (single) or $500,000 (married filing jointly) of gain on the sale of their primary residence if they owned and lived in the home for at least two of the last five years. If your office is inside the home, the exclusion generally applies to the entire home, but depreciation recapture still applies.

If your office is in a separate structure, the IRS treats it as a separate dwelling unit. You must meet ownership and use requirements for both the home and the structure to apply the exclusion. If these requirements are not met, gains from the office portion are fully taxable, including depreciation recapture at 25% and any additional gain at 15%.

Planning Strategies Before Selling

Business owners can take steps to minimize the impact of depreciation recapture. If the office is in a separate structure, consider not claiming home office deductions for at least two years before selling to maximize the exclusion on the full property. If the office is inside your home, continue claiming deductions, since recapture is required regardless of whether you claimed them.

Maintaining detailed records is essential. Keep track of expenses, depreciation, and the square footage of your office. Accurate documentation ensures correct calculation of recapture and can help prevent errors or audits.

Why Depreciation Recapture Isn’t a Penalty

It’s important to understand that depreciation recapture is not a penalty. It simply balances the tax benefit you’ve already received. Depreciation reduces taxable income over the years, providing real savings, and recapture ensures the IRS taxes the portion of gain already offset by those deductions. Even with recapture, the home office deduction remains a valuable tool for business owners, helping offset real expenses and reflecting the dual purpose of your home as both a residence and a workspace.


How to Report Gambling Winnings and Losses


Gambling income often creates confusion at tax time because the reporting rules do not follow what most taxpayers naturally expect. Many assume they are only taxed on their “net” winnings for the year. However, the IRS does not allow gambling to be reported that way. Instead, winnings and losses are handled separately, and that distinction drives the outcome on your tax return.

Reporting W-2G Gambling Winnings

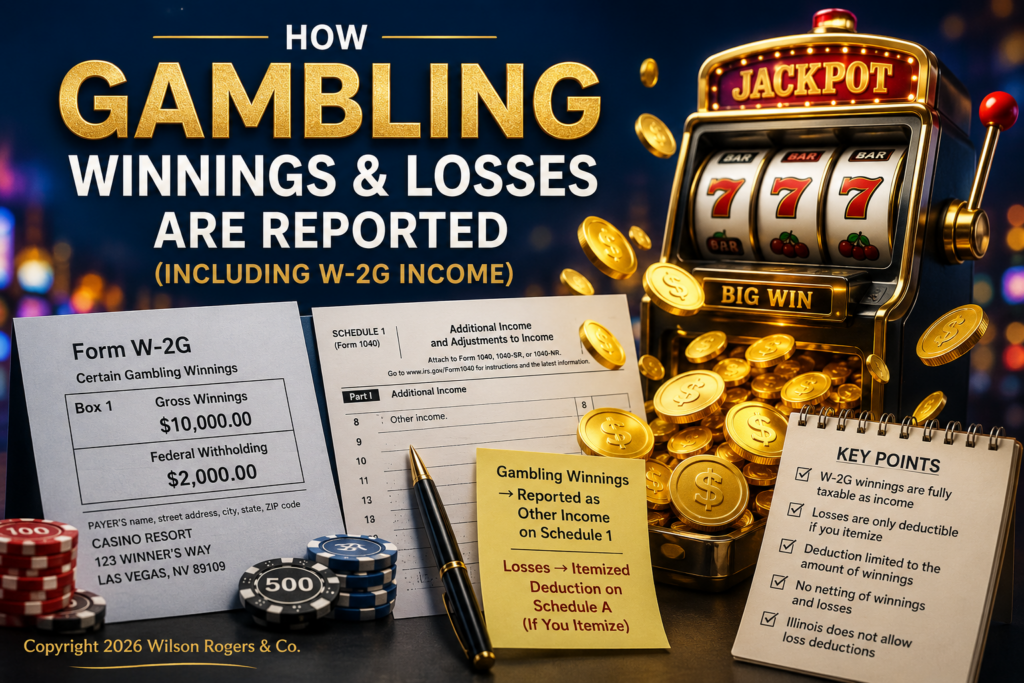
When you receive a Form W-2G, it means your gambling winnings have been reported to both you and the IRS. These forms are typically issued for larger payouts from casinos, sportsbooks, lotteries, or similar gambling activities that meet reporting thresholds. Even though a W-2G is issued, it does not change how the income is treated. The full amount shown on the form is taxable and must be included on your return.

From a reporting standpoint, W-2G winnings are included as Other Income on Schedule 1 (Form 1040). That amount then flows through to your Form 1040 and increases your total taxable income. The key point here is that the IRS is always looking at the gross winnings reported on the form, not any net figure after losses. If federal income tax was withheld and shown on the W-2G, that withholding is treated as a prepayment toward your total tax liability. It is applied when you file your return, similar to wage withholding, but it does not change the fact that the full winnings are still taxable.

How Gambling Losses Are Treated

Gambling losses are not reported in the same place as winnings, and they do not automatically reduce the income shown on a W-2G. Instead, losses are only deductible if you itemize deductions on Schedule A. This is an important distinction because many taxpayers take the standard deduction, and in those cases, gambling losses provide no tax benefit at all. Even when itemizing, losses are limited. You can only deduct gambling losses up to the amount of gambling winnings reported on your return. There is no ability to create a net loss or carry excess losses forward to future years.

For example, if you have $10,000 in W-2G winnings and $12,000 in losses, your deduction is limited to $10,000. The remaining $2,000 is not usable for tax purposes.

No Netting of Winnings and Losses

One of the most common mistakes taxpayers make is assuming they can simply net their gambling activity for the year. The IRS does not allow this approach. Gambling winnings are reported in full as income, and gambling losses are only considered separately as an itemized deduction if you qualify. There is no single calculation on the tax return where the two are combined into a net result.

State Tax Considerations (Illinois)

Illinois follows a different approach than the federal return when it comes to gambling losses, and this is where taxpayers often get caught off guard. At the federal level, gambling losses can be deducted if you itemize, up to the amount of gambling winnings. Illinois does not follow this treatment in the same way. Illinois still taxes gambling winnings in full, but it generally does not allow a deduction for gambling losses. This means that even if you had significant losses during the year, those losses typically do not reduce your Illinois taxable income. Your gambling winnings remain fully included in your Illinois return, without the same offset you might see federally.

As a result, you can end up in a situation where your federal return reflects gambling losses (if you itemize), but your Illinois return still taxes the full amount of gambling winnings. This difference can be especially noticeable for taxpayers with regular gambling activity, where the overall economic result of the year does not match the taxable outcome at the state level.

Recordkeeping Requirements

The IRS places the responsibility for documentation on the taxpayer. This means maintaining records that support both winnings and losses, including dates, locations, types of gambling activity, and amounts. While casino or sportsbook statements can be helpful, they should not be relied on as the only source of documentation if records are ever requested.

Bringing It All Together

The most important takeaway is that gambling winnings reported on a W-2G are fully taxable and must be included in income regardless of losses during the year. Those winnings flow through Schedule 1 into Form 1040 and increase taxable income directly. Losses, on the other hand, are limited, conditional, and reported separately. They only provide a benefit if you itemize deductions and only up to the amount of reported winnings.

Once you understand that winnings and losses are reported in different parts of the return, the structure of how gambling is taxed becomes much clearer and easier to follow.

Understanding the “No Tax on Tips” Provision Under the One Big Beautiful Act (OBBA)

Tax rules continue to evolve, and every so often a provision gets a headline that sounds far simpler than what the law actually does. The “no tax on tips” provision under the One Big Beautiful Act (OBBA) is a good example of that. While the name suggests that tip income is no longer taxed, that is not what the law provides.

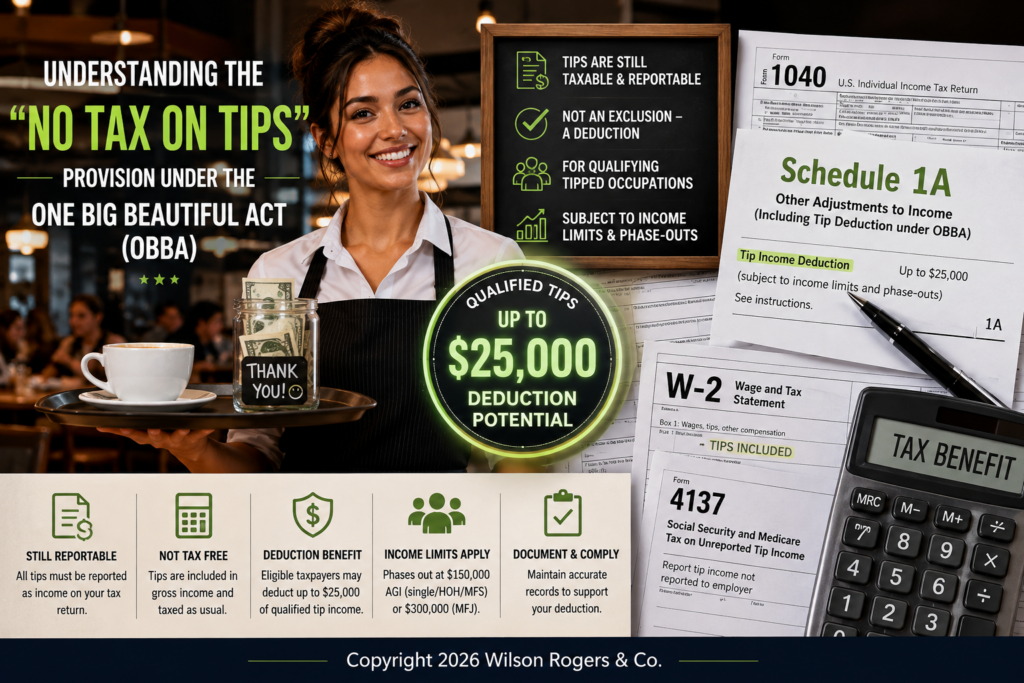
Tip income is still fully taxable and still must be reported. The core reporting rules have not changed. What OBBA introduces is not an exclusion from income, but a potential deduction that may reduce taxable income for certain qualifying tip earnings.


Tip Income is Still Reportable Income

The most important point to understand is that nothing about tip reporting has been removed or reduced. Employees and self-employed individuals are still required to report all tip income as part of gross income.

For employees, this continues to be reflected on Form W-2 as part of Box 1 wages. For self-employed individuals, tip income is still included in business receipts and ultimately flows through to Schedule C and Form 1040.

So despite the branding of “no tax on tips,” the income itself is still very much part of the tax system. The change occurs later in the return process, not at the reporting stage.


What the Provision Actually Does

Under OBBA, certain taxpayers may be eligible for a federal income tax deduction tied to qualified tip income. This is where the terminology often causes confusion. The law does not remove tips from taxable income. Instead, it allows a deduction against taxable income if the tips meet specific requirements. To qualify, the income must come from occupations that customarily and regularly received tips prior to December 31, 2024. This keeps the benefit focused on traditional tipped industries such as restaurant staff, bartenders, salon workers, and similar service-based roles.

Not all payments labeled as tips qualify. Service charges, mandatory gratuities, and standard wages are not included in the definition, even if they may resemble tips in practice.


How the Tax Benefit Is Applied

Even when tip income qualifies, it is still included in gross income. There is no exclusion at the wage or income reporting level.

Instead, the benefit is applied later as an adjustment to income. This means the taxpayer first reports all income normally, and then, if eligible, applies a deduction that reduces taxable income. This structure is important because it changes how the benefit is felt. Rather than removing tax from tip income entirely, it reduces overall taxable income after everything has already been reported.


Income Limits and Phase-Out Rules

The deduction is not unlimited and is subject to both a cap and income-based reductions. The maximum deduction allowed under OBBA is $25,000 per year. However, not every taxpayer will receive the full amount. The benefit begins to phase out once adjusted gross income exceeds certain thresholds. For single filers, head of household, and married filing separately, the phase-out begins at $150,000 of AGI. For married filing jointly, the threshold is $300,000. As income increases above these levels, the deduction is gradually reduced until it is fully phased out.

For self-employed taxpayers, there is also an additional limitation. The deduction cannot exceed the net profit of the business generating the tip income, which prevents the deduction from creating or increasing a loss position.


How Tip Income Is Reported Under Current Rules

Despite the introduction of this provision, the way tip income is reported has not changed. Employees still receive Form W-2 reporting their wages, including tip income in Box 1. Employers may separately track qualifying tip amounts for reporting purposes, but the overall structure remains the same. For individuals, all tip income continues to flow into Form 1040 as part of gross income. There is no separate exclusion or adjustment at the wage level. The only difference appears later in the return, where eligible taxpayers may apply the deduction.


Where the Deduction Appears on the Tax Return

The deduction is claimed on Schedule 1A of Form 1040, which is a new schedule introduced beginning in 2025 under OBBA. This schedule is used for “Other Adjustments to Income,” including several new provisions created by the legislation. In general, the deduction is based on either qualified tips reported by the employer on Form W-2 or tip income reported directly by the taxpayer on Form 4137 when applicable.

Regardless of the reporting method, the key requirement is that the income must be properly documented and traceable through official records.


Documentation and Compliance Requirements

As with most tax provisions tied to income adjustments, documentation is essential. The IRS will expect consistency between employer reporting and taxpayer reporting, and discrepancies can create issues during review. Supporting documentation may include payroll records, employer tip allocation reports, Form W-2, and Form 4137 when tips are not fully captured through payroll systems.

Accurate reporting matters not just for compliance, but also for ensuring the deduction is not disallowed due to incomplete or inconsistent records.


Final Takeaway

Despite its name, the “no tax on tips” provision does not eliminate taxation on tip income. Instead, it creates a targeted deduction that reduces taxable income for qualifying taxpayers in certain tipped occupations. The income is still reported, still tracked, and still subject to the same reporting rules as before. The difference lies in how the tax calculation is adjusted after reporting is complete.

As with most tax law changes, the real impact comes down to details, documentation, and income level. For taxpayers who rely on tip income, understanding how this provision fits into the broader return is key to avoiding confusion at tax time.


A Guide to the “No Tax on Overtime” Provision in the OBBA

Understanding the “No Tax on Overtime” Provision Under the One Big Beautiful Act (OBBA)

One of the more commonly misunderstood changes introduced under the One Big Beautiful Act (OBBA) is the “no tax on overtime” provision. At first glance, the name suggests that overtime pay is no longer taxable. In reality, that is not the case. This provision does not eliminate tax on overtime wages. Instead, it creates a limited deduction that applies only to a specific portion of overtime compensation, and only when it is properly identified, calculated, and reported.

What “No Tax on Overtime” Actually Means

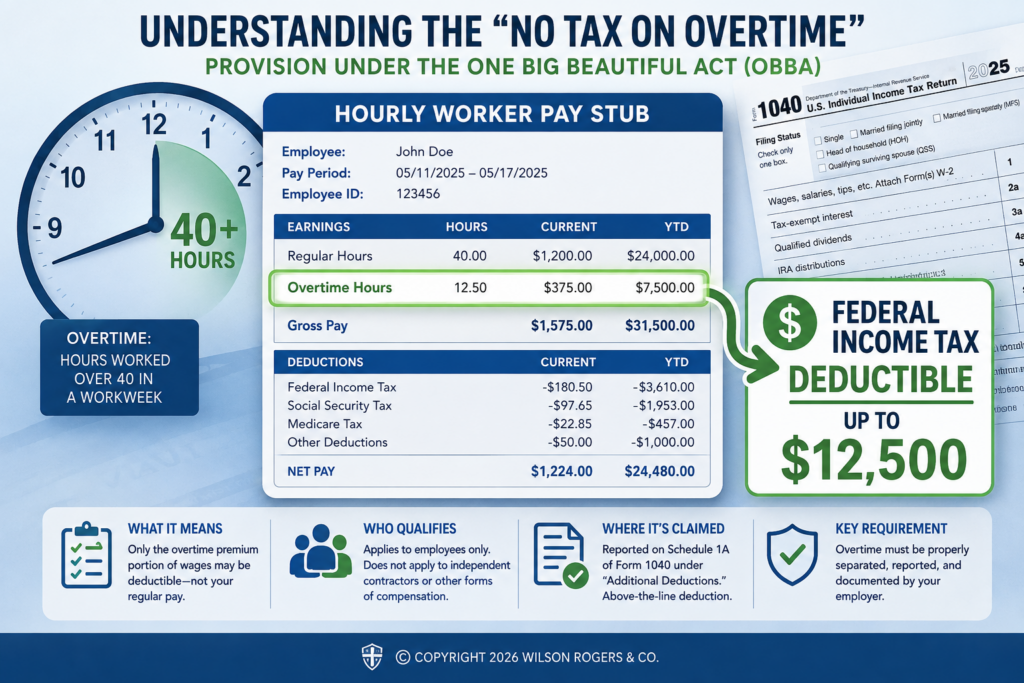
Under OBBA, the provision applies only to the overtime premium portion of wages. This is the additional amount paid above an employee’s regular hourly rate for hours worked beyond standard thresholds. Regular wages remain fully taxable, only the premium portion may qualify for the deduction. Overtime is generally defined under FLSA (Fair Labor Standards Act) rules, typically for hours worked over 40 in a workweek. This provision applies strictly to employees and does not extend to independent contractors or other forms of compensation such as bonuses. It is also important to understand that simply working overtime is not enough to qualify. The overtime must be separated into its regular rate and overtime premium, and only the premium portion is eligible for consideration.

Limits and Income Phase-Out Rules

Like most tax provisions, the overtime deduction includes strict limitations. The deduction for qualified overtime compensation is capped at $12,500 per year for most filers and $25,000 per year for Married Filing Jointly.

The benefit also phases out based on income. The phase-out begins when adjusted gross income exceeds $150,000 for Single, Head of Household, and Married Filing Separately, and $300,000 for Married Filing Jointly. As income increases beyond those thresholds, the deduction is gradually reduced until it is fully phased out.

Employers are required to separately account for qualified overtime compensation. This reporting requirement is part of the framework that ensures proper identification of eligible amounts.

How Overtime Is Reported

Even with this provision, overtime reporting has not changed at its core. On Form W-2, total wages are still reported in Box 1, which includes both regular and overtime earnings. However, the overtime premium portion must now be separately identified using updated IRS wage codes or reporting fields.

On Form 1040, overtime income is still included in gross wages. The key difference is that the tax benefit is not applied at the wage level. Instead, it is calculated later in the return as an adjustment to income.

Where the Deduction Is Claimed

The deduction is reported on Schedule 1A of Form 1040 under “Additional Deductions.” This is a new OBBA-related line item beginning in 2025. This is considered an above-the-line deduction, meaning it reduces adjusted gross income before either the standard deduction or itemized deductions are applied. This structure is significant because it can affect taxable income more broadly than a typical below-the-line deduction.

Documentation and Verification Requirements

Proper documentation is a key part of this provision. The IRS will expect clear support showing how overtime was calculated and separated from regular wages.

Pay stubs alone that simply label overtime are not sufficient. The underlying breakdown must clearly show regular pay versus overtime premium amounts. Verification should be based on employer payroll records, which serve as the primary source of truth, followed by pay stubs as supporting documentation. Employee statements or estimates are not reliable on their own and should not be used in place of formal records. Consistency across all documentation is essential. The classification of overtime must match across payroll systems, W-2 reporting, and any supporting forms used in the return.

Final Takeaway

The “no tax on overtime” provision under OBBA does not eliminate taxation on overtime earnings. Instead, it provides a limited deduction that applies only to the overtime premium portion of wages and only for taxpayers who meet specific income and reporting requirements.

While the provision may offer meaningful tax relief for eligible individuals, it depends heavily on accurate payroll reporting, proper classification of wages, and strong documentation. As with many tax changes, the details determine the outcome, and precision in reporting is essential for compliance.

How OBBA New Car Loan Interest Deduction Works

Understanding the New Car Loan Interest Deduction Under the OBBA

The One Big Beautiful Act (OBBA) introduces a new deduction for car loan interest that can be easy to misunderstand or misapply if the requirements aren’t carefully reviewed. While it may sound straightforward, the details around vehicle eligibility, loan structure, and income limits are critical. Missing any one of these rules can result in claiming a deduction that doesn’t actually apply.

Below is a breakdown of how it works, who qualifies, and how it must be reported.

What This Deduction Is

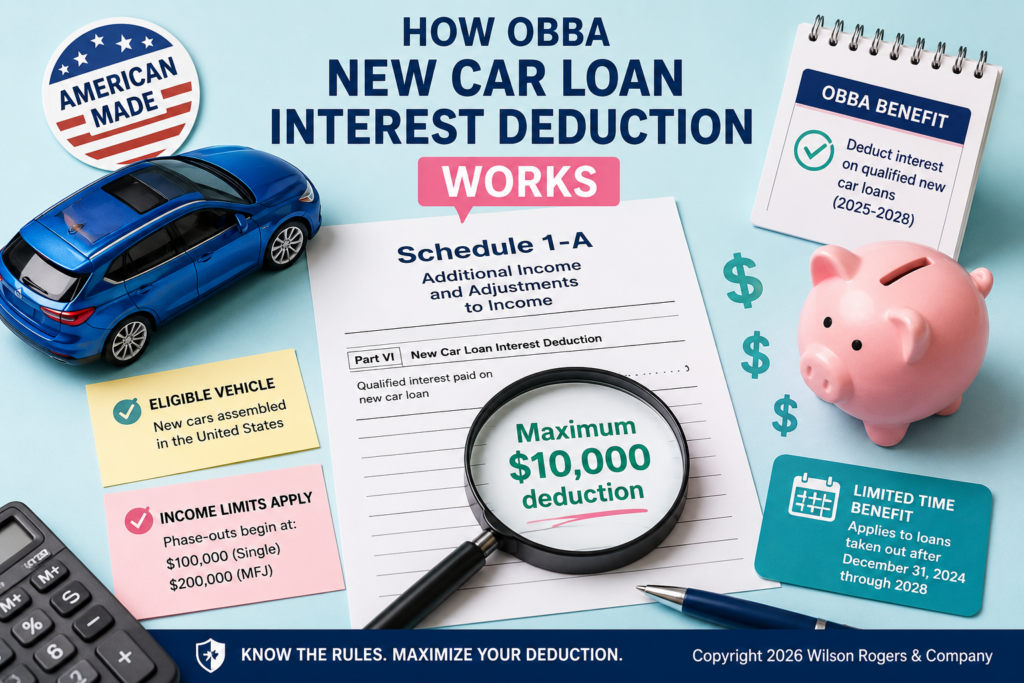
Under the OBBA, taxpayers may deduct interest paid on a qualified passenger vehicle loan. The key distinction here is that only the interest portion of the loan qualifies—not the purchase price, not the down payment, and not any related costs like insurance or registration. Another important feature is how the deduction is claimed. It is available regardless of whether you itemize deductions, which makes it more broadly accessible than many traditional tax breaks. Instead of being reported on Schedule A, it is taken on Schedule 1A, reducing your adjusted gross income directly.

Vehicle Qualification Requirements

This is the most important part of the rule set, and it cannot be overlooked. Before considering any interest amounts, the vehicle must be confirmed as qualifying.

The vehicle must be for personal use and cannot be used for business or mixed-use purposes. It must be a passenger vehicle and must have final assembly occurring in the United States. It also needs to meet IRS passenger vehicle weight limits.

In addition to the vehicle requirements, the loan itself must also qualify. The loan must be incurred after 2024 and must be secured by a first lien, meaning it is a secured loan used specifically to purchase the vehicle. If any of these requirements are not met, the deduction does not apply.

Caps, Phase-Outs, and Reporting

The deduction is capped at $10,000 of interest per tax year. It begins to phase out when adjusted gross income exceeds $100,000 for single filers and $200,000 for married filing jointly. Once income exceeds these thresholds, the available deduction is gradually reduced until it is fully phased out.

How to Report the Deduction

The deduction is calculated and reported on Schedule 1A of Form 1040. This is a deduction, not a credit, meaning it reduces taxable income rather than directly reducing tax liability.

Proper documentation is also required. Taxpayers must have lender interest documentation such as Form 1098-V or a similar statement to support the deduction.

Important Reminder for Business Vehicles

Business vehicle interest follows entirely different rules and must not be combined with this deduction. The OBBA provision applies strictly to qualified personal-use vehicles, and blending business interest into this calculation would result in an incorrect application of the rules.

In Summary

This deduction is temporary and is currently available for tax years 2025 through 2028. Proper application requires careful verification of vehicle eligibility, loan qualifications, adjusted gross income thresholds, and correct reporting on Schedule 1A. While it can provide meaningful tax savings, it is highly dependent on meeting all qualification rules exactly as outlined.


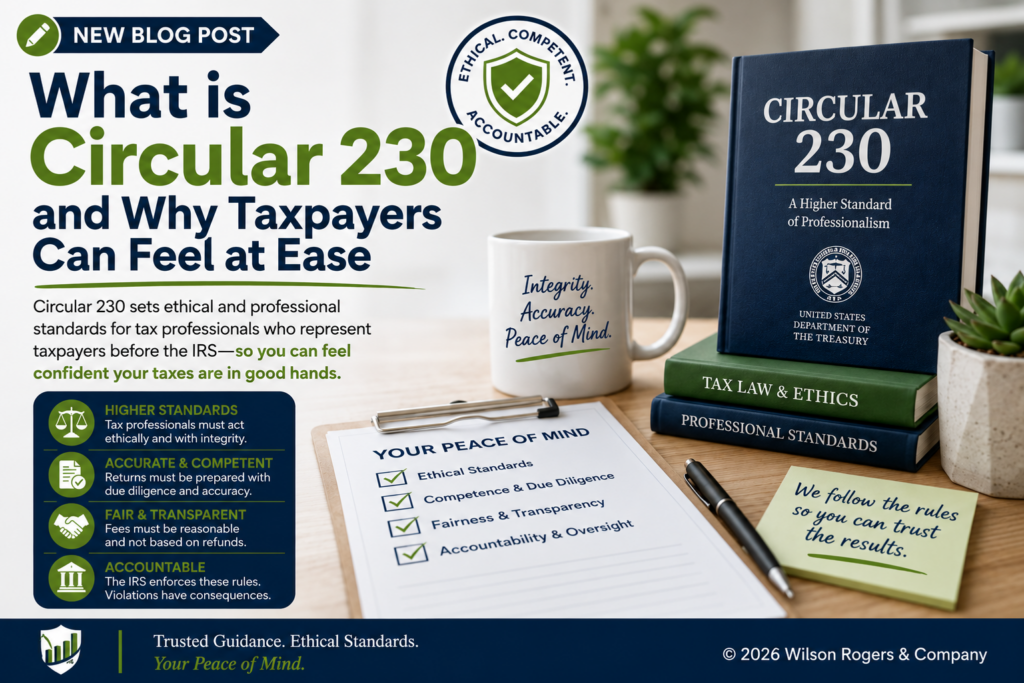
What is Circular 230 & Why Taxpayers Can Feel at Ease

Ever feel nervous handing over your tax documents to someone else? You’re not alone. Every year, taxpayers trust preparers with their most personal financial information—income, investments, dependents, and more—hoping everything is done correctly.

The good news? There’s already a safeguard in place to protect you and hold your preparer accountable. It’s called Circular 230, and it’s one of the most important—but least known—rules in the tax world.

What Exactly is Circular 230?

Circular 230 is an official publication from the U.S. Department of the Treasury. It sets the rules and ethical standards for professionals who represent taxpayers before the IRS.

This includes CPAs, Enrolled Agents (EAs), tax attorneys, and other individuals authorized to practice before the IRS. Essentially, if someone is legally allowed to handle your taxes, they must follow Circular 230.

Think of it as the IRS’s code of conduct for tax professionals. It ensures that your preparer acts with integrity, honesty, and professionalism—giving you confidence that your taxes are in capable hands.

How Circular 230 Protects You

Circular 230 exists not just for professionals, but for taxpayers. It ensures that anyone handling your return is competent, ethical, and accountable.

First, it holds preparers to a higher standard. They must act ethically, avoid conflicts of interest, and exercise due diligence. Misleading clients, making unrealistic promises, or taking risky tax positions is not allowed.

Second, it requires accuracy and competence. Tax professionals must verify information and ensure returns are correct. This reduces the risk of errors, penalties, or audits from sloppy or negligent work.

Third, it promotes fairness. Circular 230 regulates fees in many cases, preventing unreasonable or contingent charges. You can trust you’re being charged fairly, not based on the size of your refund.

Finally, it enforces accountability. The IRS Office of Professional Responsibility monitors compliance, and a preparer who acts unethically can be suspended or barred from practice. That oversight means you’re not on your own if something goes wrong.

Why This Matters to You

Working with a preparer covered under Circular 230—like a CPA, EA, or tax attorney—gives you peace of mind. They are legally bound by federal ethics and practice standards, required to act in your best interest, and can face real consequences for misconduct.

Put simply, Circular 230 gives you a safety net every time you file. Your preparer is trained to handle your taxes responsibly, accurately, and ethically.

Your Role as a Taxpayer

Circular 230 protects you, but you still play a key role in keeping your tax process safe. Always confirm your preparer’s credentials, review your return before signing, keep copies of your records, and provide accurate information. Being proactive helps protect both you and your preparer.

Final Thoughts

Most taxpayers never think about Circular 230, but it works quietly in the background to keep the tax system ethical, fair, and accountable. It’s why you can hand over your financial documents to a qualified preparer and trust that they are required to act professionally.

Behind every trusted tax professional is a set of IRS-enforced rules designed to protect you. Circular 230 gives taxpayers peace of mind, knowing their preparer is qualified, ethical, and committed to doing things the right way—every single time.


Benefits of E-Filing vs. Paper Filing


E-Filing vs. Paper Filing: Which Is Better for Taxpayers?

When tax season arrives, one of the first decisions taxpayers face is how to file their return. While paper filing was once the standard, electronic filing—commonly known as e-filing—has become the preferred method for both taxpayers and the IRS. And for good reasons. E-filing offers speed, accuracy, and security that paper simply can’t match.

Whether you file on your own or work with a tax professional, understanding the benefits of e-filing can help you make a confident, informed choice.

Faster Processing Means Faster Refunds

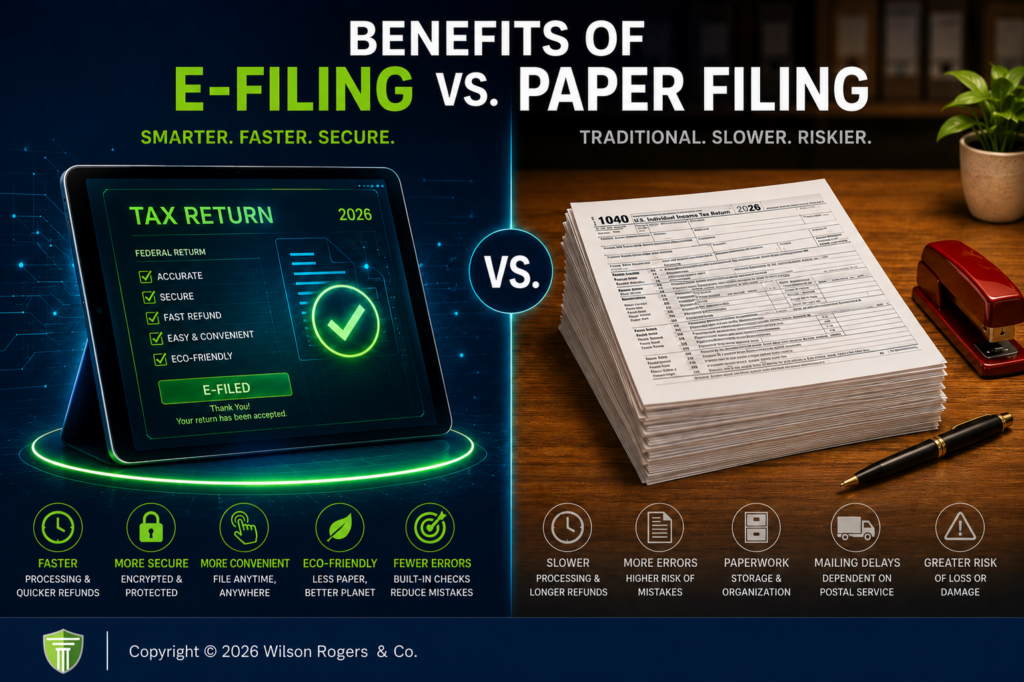
One of the most significant advantages of e-filing is how quickly your return moves through the IRS system. Electronic returns are transmitted instantly and begin processing within hours. In most cases, taxpayers who e-file and choose direct deposit receive their refunds in 1–3 weeks.

Paper returns, on the other hand, must travel through the mail, wait in IRS processing queues, and be manually entered into the system. This often results in 6–12 week wait times—and longer during IRS backlogs.

If getting your refund quickly is a priority, e-filing is the clear winner.

Greater Accuracy and Fewer IRS Notices

E-filing significantly reduces the risk of mathematical errors and missing information. Tax software automatically performs calculations, checks for inconsistencies, and flags required fields before the return is submitted. The IRS reports that e-filed returns have a much lower error rate compared to paper filings.

With paper returns, even a small mistake—such as a mismatched Social Security number or an overlooked signature—can trigger delays or IRS notices.

E-filing helps avoid these issues and ensures your return starts on the right foot.

Immediate Confirmation of Submission

Waiting and wondering whether the IRS received your paper return can be stressful. With e-filing, you receive electronic confirmation that your return has been received and accepted. No guessing, no tracking numbers, and no risk of lost mail.

For taxpayers who value peace of mind, this acknowledgment is a major benefit.

Enhanced Security and Data Protection

E-filing systems use encrypted, secure channels to protect your sensitive financial information – the same level of protection used by major banks. Paper returns, however, can be lost, misdelivered, or even stolen while being mailed.

If safeguarding your personal information is a top priority, e-filing offers the strongest layer of protection.

Easy Access to Prior-Year Tax Documents

When you e-file, your tax professional or software program securely stores your return and supporting documents. If you need a copy for a mortgage, loan application, or audit, retrieving it takes seconds.

Paper returns can be misplaced or damaged, creating stress when documentation is needed most.

Environmentally Friendly

E-filing cuts down on unnecessary paper and reduces waste. It’s a simple way to go greener during tax season.

Required for Many Preparers and Businesses

The IRS requires certain tax preparers and many businesses to electronically file once they meet specific thresholds. E-filing helps ensure compliance and avoids penalties, making it the practical choice for most professionals.

When Paper Filing May Be Necessary

Although e-filing is the preferred method, there are a few situations where paper filing may still be required or beneficial:

  1. Filing After the E-File Deadline

Once the IRS e-file system shuts down for the season—typically in October—late returns must be submitted on paper. This often happens when taxpayers miss both the regular deadline and any extension deadline.

  1. Returns That Cannot Be E-Filed

Certain uncommon forms, elections, or specialized filings cannot be submitted electronically. For example, if your return includes forms the IRS does not support for e-file, a paper return may be necessary.

  1. Correcting Identity or Data Issues

If the IRS rejects an e-filed return due to mismatched Social Security numbers, prior-year AGI problems, or identity theft flags—and the issue can’t be resolved electronically—a paper return may be required.

  1. Amended Returns (in rare cases)

Although most amended returns can now be e-filed, some older tax years or special situations still require mailing a paper Form 1040-X.

  1. Filing Without Proper E-File Access

Taxpayers with limited technology access or those who prefer physical signatures in rare circumstances may choose paper filing, though this is far less common.

While these situations exist, they are the exception—not the rule. For the vast majority of taxpayers, e-filing remains the most efficient and reliable option.

Conclusion

While both e-filing and paper filing will get your tax return to the IRS, the benefits of e-filing—faster refunds, fewer errors, stronger security, and immediate confirmation—make it the smarter choice for most taxpayers. Paper filing still plays an important role in special situations, such as filing after the e-file deadline or handling uncommon forms the IRS doesn’t support electronically. But for everyday taxpayers and most businesses, e-filing remains the simplest, safest, and most efficient way to stay compliant during tax season.

Money Management YouTube Series

Our YouTube videos discuss money management and tax saving strategies. Artwork compliments of Michael Voogd at VoogDesigns!

Many Americans often find themselves broke and living paycheck to paycheck. But why does this happen? Is it because of lack of income/earnings? Is it due to not having certain “higher” level education or degrees like a Bachelor’s or Master’s degree from college? Is it because of certain race, gender, sexual preference or other items which can be discriminated against? Contrary to popular belief, it’s NOT just tied to how much money a person makes.

George Floyd’s Impact, Inspiration and Legacy

In early 2020, because of the tragic murder and death of George Floyd, Americans were forced to confront some realities that some would rather not. His death, on top of many Americans being out of work due to the Covid-19 Pandemic, was just enough to push us into a tailspin of social unrest. The resulting looting, rioting and “every person for themselves” mentality which followed, made one thing clear (if it was to no one other than ourselves). Through no fault of their own, many Americans are only one paycheck away from disaster.

This can be a small disaster like missing a cell phone bill, a cable bill or not having enough to go out and eat at your favorite restaurant. Or it could be a serious disaster like missing a rent or mortgage payment, getting evicted, or having to turn to a food pantry for help.

Our good friend, and client, Ashanti Johnson over at 360 Mind Body Soul here in Chicago, encouraged us to start a video series in connection with a virtual wellness summit that our CEO, Jared Rogers, participated in. Check out this specific point in Episode 10 where Jared shares a snippet of her summit and talks about George Floyd and the resulting motivation to launch the series.

In the end, seeing as we deal with money on a day-in and day-out basis, it only made sense that we should work to share the knowledge we have built up over the years with those who need it the most. So, through a culmination of all of the above, we decided that we had an obligation to do more.

Minding My Money Mondays & Tax Chit Chat

Minding My Money Mondays (#MMMM) was the YouTube series that was directly birthed following the events after Mr. Floyd’s death. In early December, we created a separate series called Tax Chit Chat (#TCC) that is for those looking specifically for just tax tips. All videos will ultimately get rolled into a much larger money management website (hopefully by early H2 of 2021), but in the interim, you can follow both series by subscribing to our YouTube channel. Each series has it’s own playlist and releases videos according to it’s prescribed schedule.

Video Episode Listing

Shown below is a listing of the episodes that were created through the date of this blog post. They go from most recent back to the very first episode. To catch an episode, simply click the title above the video thumbnail and you’ll be taken directly to it within YouTube. It’s our sincere hope that that you:

  1. Enjoy the videos and learn from them
  2. Spread the word on social media via the hashtags #MMMM and #TCC as we really hope to help people “Make My Money Make Sense!”
  3. Eventually join us on the money management website once it’s launched
  4. Send us questions and video suggestions at questions@makemymoneymakesense.com as we hope to help everyone learn how to better manage their money and avoid financial disaster (although NO ONE saw a Covid-19 type event coming).
3 Reasons People Are Broke! | MMMM S1 EP26
Top Year End Tax Saving Tips For 2020 | TCC S1 EP1
How Much To Contribute To Your 401K or Retirement Plan? | MMMM S1 EP25
How to save money buying a new car | MMMM S1 EP24
Move Out of Parents House After Graduating? | MMMM S1 EP23
Saving Money On A Tight Budget or Low Income| MMMM S1 EP22
Inherited $200K; Dealing With A Windfall| MMMM S1 EP21
Drain My Savings To Pay Off Debt? | MMMM S1 EP20
Wealth Is A Game of Emotions! | MMMM S1 EP19
Big Bank vs. Online Bank vs. Credit Union | MMMM S1 EP18
Tax Loss Harvesting Explained | MMMM S1 EP16
Student Loans: Pay Off or Pay For Life? | MMMM S1 EP15
Pay Off High Interest of High Balance Card First? | MMMM S1 EP14
Alternatives to low interest CDs | MMMM S1 EP13
5 ways to make $1,000! | MMMM S1 EP12
Broke? How to start an emergency fund from ZERO! | MMMM S1 EP11
Without these 2, you’ll never have money success! | MMMM S1 EP10
Poor money habits = profits for banks! | MMMM S1 EP9
Rockefeller on The Power of Interest | MMMM S1 EP8
IRS Guaranteed Installment Agreement | MMMM S1 EP7
I Can’t Pay The IRS; Now What? | MMMM S1 EP6
How To Get A 800+ Credit Score | MMMM S1 EP5
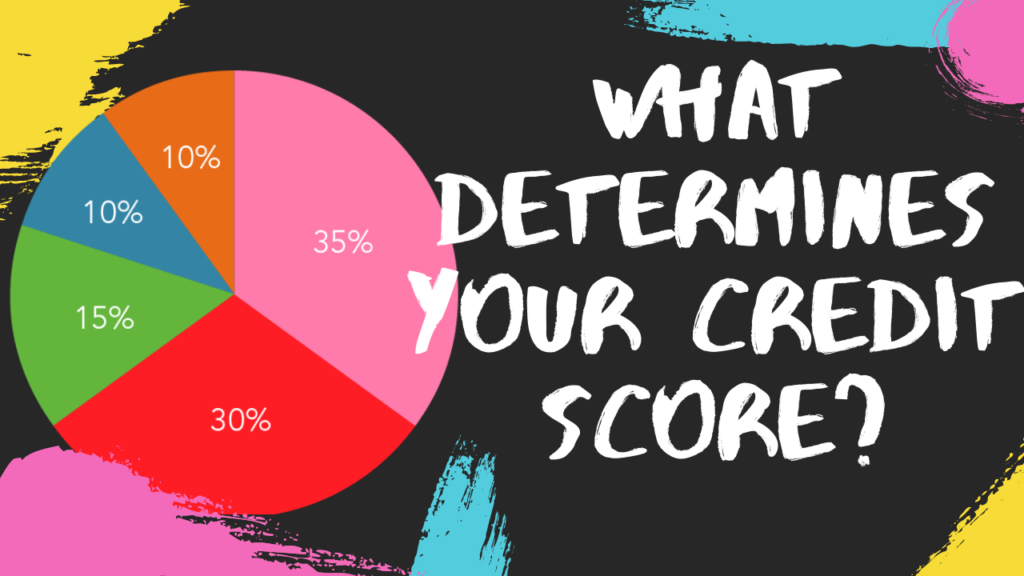
What Makes Up Your Credit Score? | MMMM S1 EP4
How Should You Manage Money? | MMMM S1 EP3
What Is A (Ideal) Budget? | MMMM S1 EP2
What is Money? | MMMM S1 EP1
By |2024-04-13T14:31:20-06:00December 14, 2020|Categories: Accounting Talk, Tax Talk|Tags: , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , , |0 Comments
Go to Top