Ethical Standards for Tax Preparers
In the complicated world of taxation, where financial responsibilities intersect with legal obligations, the role of a tax preparer is both crucial and delicate. As tax season approaches, it becomes increasingly important to shine a light on the ethical standards that guide these financial professionals. In this blog post, we explore the essential ethical principles that should govern the conduct of tax preparers, ensuring not only compliance with the law but also the maintenance of trust and integrity in their crucial role.
There are several key ethical principles that tax preparers should follow, these includes:
- Confidentiality: the preparer has the responsibility to keep all of their client’s information confidential, even if the relationship ends, they must continue to follow this. The only time they should disclose information is with the client’s consent or when it is required by the law.
- Competence: they should also keep up to date with the latest tax laws and regulations in order to stay competent in their specific field. This includes providing services that they are qualified to provide and should refer clients to other professionals if they aren’t prepared.
- Integrity: tax preparers must be honest, credible, and trustworthy as it is their obligation to protect and enhance the trust of the client. This includes avoiding any conflicts of interest and not engaging in any activity that could damage their own reputation or profession.
- Due Diligence: Tax preparers should perform due diligence on their client information and should never prepare returns that are inaccurate or incomplete knowingly.
- Independence: tax preparers should not allow their personal interest to interfere with their personal judgment. This includes any relationship that could compromise their objectivity or integrity.
In addition to these general ethical principles, they must also comply with specific professional standards and regulations. They may vary depending on the jurisdiction in which the tax preparer is practicing and the specific area they are focused in. However, some of the most common standards and regulations include:
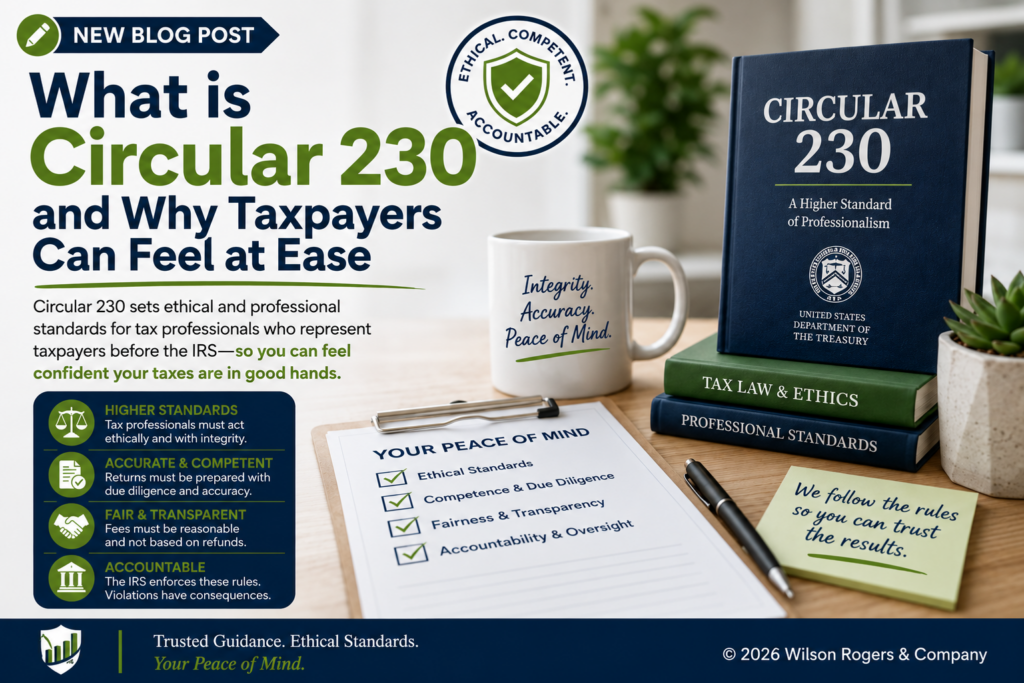
- Circular 230: These are a set of regulations issues by the US department of the Treasury that govern the practice of tax law. This also requires tax preparers to be competent, honest, and ethical in their dealings with clients.
- AICPA Statements on Standards for Tax Services: These are a set of standards issued by the American Institute of Certified Public Accountants that govern the preparation of tax returns. These standards require tax preparers to perform due diligence in order to disclose any material uncertainties and to avoid taking unreasonable positions.
- National Associations of Tax Professionals (NATP) Code of Ethics: this is made up of the code of ethics that are applied to all members of the NATP. The NATP Code of Ethics requires members to be honest, competent, and ethical when it comes to working with their clients.
If a tax preparer engages in any unethical conduct, they can potentially face a number of consequences, such as:
- Loss of professional license
- Fines and penalties
- These include fines up to $100,000 or $500,000 in the case of a corporation
- Criminal Chargers
- Imprisonment for up to three years with felony or misdemeanors being on your record
These consequences vary for each situation such as the penalty being less expensive as we mentioned or imprisonment being less time. Whatever the case maybe they are nothing to take lightly.
In conclusion, ethical standards are paramount for tax preparers as they navigate the complicated landscape of taxation. These standards, encompassing confidentiality, competence, integrity, due diligence, and independence, form the bedrock of responsible and honest conduct. Reinforced by specific professional standards, violations can lead to severe consequences, including the loss of professional licenses, substantial fines, and criminal charges. As tax preparers approach the challenges of tax season, faithfulness to these ethical principles is not only an expectation but an obligation. Upholding these standards is crucial for maintaining trust, safeguarding reputations, and preserving the integrity of the financial profession. In essence, ethical conduct is not just a guideline; it is an indispensable compass that guides tax preparers towards principled and responsible tax preparation.