Home Office Deduction: How Depreciation Recapture Affects the Sale of Your Home
Using part of your home for business can provide meaningful tax savings through the home office deduction. Homeowners and renters alike can benefit from this deduction, but if you later sell your home, there’s an important consideration: depreciation recapture. Understanding how this works can help you plan ahead and avoid surprises at tax time.
Requirements for the Home Office Deduction
To claim the home office deduction, two key requirements must be met. First, the space must be used regularly and exclusively for business purposes. A home office cannot double as a guest room, den, or entertainment space. Occasional or incidental business use, such as quarterly meetings, does not qualify. Second, your home must serve as your principal place of business. Even if you conduct work elsewhere, you may qualify if you use your home substantially and regularly. Separate structures, such as garages, studios, or barns, can also qualify if they are used exclusively for business.
How to Claim the Deduction
Deductions are generally based on the percentage of your home used for business. There are two calculation methods. The simplified method allows a deduction of $5 per square foot, up to 300 square feet, for a maximum of $1,500. Depreciation is not claimed under this method, which means no recapture tax applies when you sell, and recordkeeping is minimal.
The regular (actual expense) method calculates the actual expenses of operating your home, including mortgage interest, utilities, insurance, repairs, and depreciation. Expenses are allocated based on the business-use portion of your home, and deductions are reported on IRS Form 8829. While this method often results in larger deductions each year, it triggers depreciation recapture when you sell your home.
Where you report the deduction depends on your business type. Self-employed individuals typically report it on Schedule C, Line 30. Employees may report eligible expenses on Schedule A as itemized deductions (if allowed). Partnerships, LLCs, and S-Corps usually handle the deduction through accountable plans or entity-level reimbursements.
Depreciation Recapture Explained
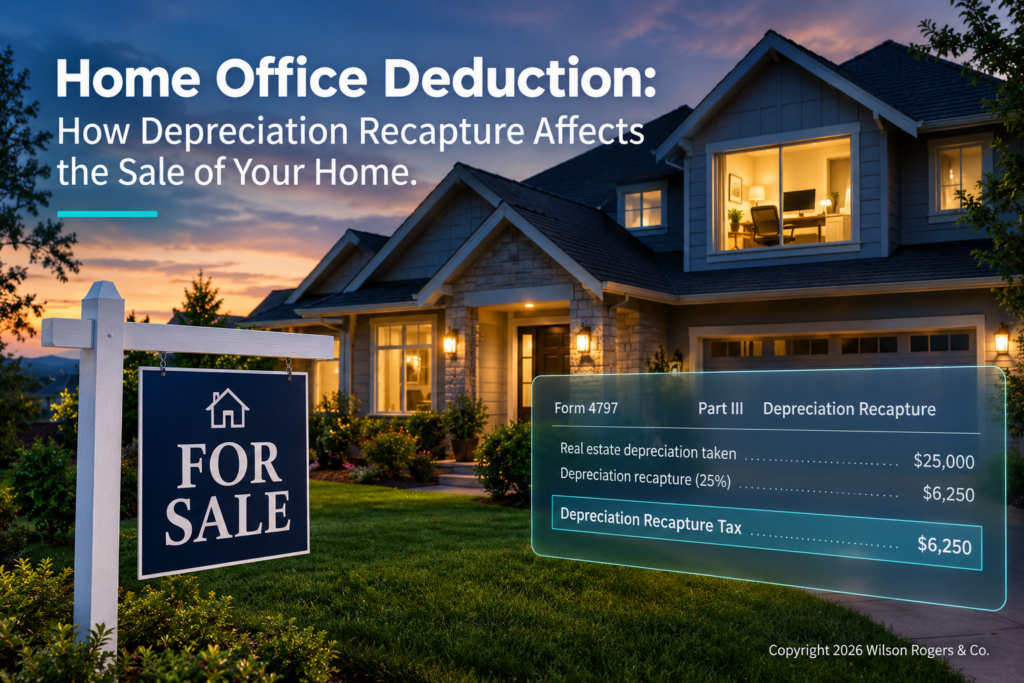
Depreciation reduces your taxable income in the years you claim it, but when you sell your home, the IRS requires you to recapture the depreciation for the business-use portion. Depreciation recapture is taxed at a maximum rate of 25%, separate from long-term capital gains, which are generally taxed at 15%. Even if you didn’t claim all allowable depreciation, the IRS requires recapture of any portion that could have been claimed.
Example:
- Home purchase price: $300,000
- Business-use portion: 10%
- Depreciation claimed: $10,000
- Sale price: $500,000
Recapture: $10,000 taxed at up to 25%
Remaining gain: $190,000 may qualify for the capital gains exclusion ($250,000 single / $500,000 married filing jointly)
Capital Gains Exclusion and the Home Office
The capital gains exclusion allows homeowners to exclude up to $250,000 (single) or $500,000 (married filing jointly) of gain on the sale of their primary residence if they owned and lived in the home for at least two of the last five years. If your office is inside the home, the exclusion generally applies to the entire home, but depreciation recapture still applies.
If your office is in a separate structure, the IRS treats it as a separate dwelling unit. You must meet ownership and use requirements for both the home and the structure to apply the exclusion. If these requirements are not met, gains from the office portion are fully taxable, including depreciation recapture at 25% and any additional gain at 15%.
Planning Strategies Before Selling
Business owners can take steps to minimize the impact of depreciation recapture. If the office is in a separate structure, consider not claiming home office deductions for at least two years before selling to maximize the exclusion on the full property. If the office is inside your home, continue claiming deductions, since recapture is required regardless of whether you claimed them.
Maintaining detailed records is essential. Keep track of expenses, depreciation, and the square footage of your office. Accurate documentation ensures correct calculation of recapture and can help prevent errors or audits.
Why Depreciation Recapture Isn’t a Penalty
It’s important to understand that depreciation recapture is not a penalty. It simply balances the tax benefit you’ve already received. Depreciation reduces taxable income over the years, providing real savings, and recapture ensures the IRS taxes the portion of gain already offset by those deductions. Even with recapture, the home office deduction remains a valuable tool for business owners, helping offset real expenses and reflecting the dual purpose of your home as both a residence and a workspace.