12 Smart Habits That Can Help Reduce Your Business Tax Burden


Most business owners don’t want to spend more time thinking about taxes, they want to spend more time growing their business. The good news is that reducing your tax burden often isn’t about finding complicated tax strategies. It’s about building simple habits throughout the year.

Waiting until tax season to think about taxes can mean missed deductions, unnecessary penalties, and a larger tax bill than expected. Here are 12 habits that can help you keep more of what you earn while staying organized and compliant.

  1. Separate Business and Personal Finances

One of the easiest ways to improve your tax situation is to keep business and personal expenses separate. Use a dedicated business bank account and credit card so your bookkeeping stays clean and you don’t accidentally miss deductible expenses.

Why it matters: Clean financial records save time, reduce stress, and makes us tax preparers much more confident and decisive with your return.

  1. Review Your Financial Reports Every Month

Don’t wait until year-end to find out how your business is performing. Set aside time each month to review your Profit & Loss statement, cash flow, and major expenses.

Why it matters: Monthly reviews help you identify opportunities to reduce taxes before it’s too late to act.

  1. Keep Track of Every Business Expense

Small expenses add up over the course of a year. Software subscriptions, office supplies, marketing costs, professional memberships, and business meals may all be deductible when properly documented.

Common mistake: Waiting until tax season to search for receipts usually means some deductions get lost.

  1. Pay Estimated Taxes on Time

Many business owners are required to make quarterly estimated tax payments. Missing these deadlines can result in penalties and interest.

Planning ahead helps spread your tax payments throughout the year instead of facing one large surprise.

  1. Contribute to Retirement Accounts

Retirement plans can do more than prepare you for the future, they may also reduce your taxable income today.

Depending on your business structure, there may be several retirement plan options available that provide valuable tax benefits.

  1. Track Business Mileage

If you use your personal vehicle for business, keep an accurate mileage log throughout the year.

Trying to recreate mileage months later isn’t just difficult, it may also reduce the accuracy of your records.

  1. Don’t Overlook Home Office Expenses

If you legitimately qualify for the home office deduction, keeping good records is essential. Expenses such as utilities, internet, insurance, and maintenance may qualify depending on your situation.

Good documentation makes all the difference.

  1. Plan Major Purchases Before Year-End

Thinking about buying equipment, upgrading computers, or investing in new software?

The timing of these purchases can affect your tax liability. Planning ahead may allow you to maximize available deductions while still making smart business decisions.

  1. Meet With Your CPA Before Tax Season

One of the biggest mistakes business owners make is waiting until tax season to ask tax questions.

A year-end planning meeting gives you time to discuss strategies such as:

  • Managing taxable income
  • Retirement contributions
  • Equipment purchases
  • Estimated tax payments
  • Potential tax credits

By the time your tax return is being prepared, many planning opportunities have already passed.

  1. Keep Your Bookkeeping Current

Accurate bookkeeping isn’t just for tax returns; it’s one of the best management tools a business owner has.

When your financial records are current, you can:

  • Make better business decisions
  • Identify unnecessary spending
  • Prepare for tax season with confidence
  • Reduce the likelihood of costly mistakes
  1. Stay Organized Throughout the Year

Instead of scrambling every spring, create simple weekly or monthly routines.

Examples include:

  • Filing receipts
  • Reconciling bank accounts
  • Reviewing invoices
  • Recording payroll
  • Organizing important tax documents

A little consistency goes a long way.

  1. Ask Before You Make Big Decisions

Hiring employees, purchasing equipment, expanding locations, or changing your business structure can all have tax consequences.

A quick conversation before making a major decision often uncovers opportunities that aren’t available afterward.

The Bottom Line

The business owners who consistently reduce their tax burden aren’t necessarily the ones with the biggest budgets or the most complex businesses. They’re the ones who plan ahead.

Good tax planning starts long before tax season. By building a few simple habits into your routine, you’ll be better prepared to claim every deduction you’re entitled to, avoid unnecessary surprises, and make more informed financial decisions throughout the year.

At Wilson Rogers, we believe tax planning should be proactive, not reactive. Our goal is to help business owners understand what their numbers mean, avoid common pitfalls, and make confident decisions that support long-term success. When taxes become part of your year-round business strategy, you’re in a much stronger position to keep more of what you’ve worked hard to earn.
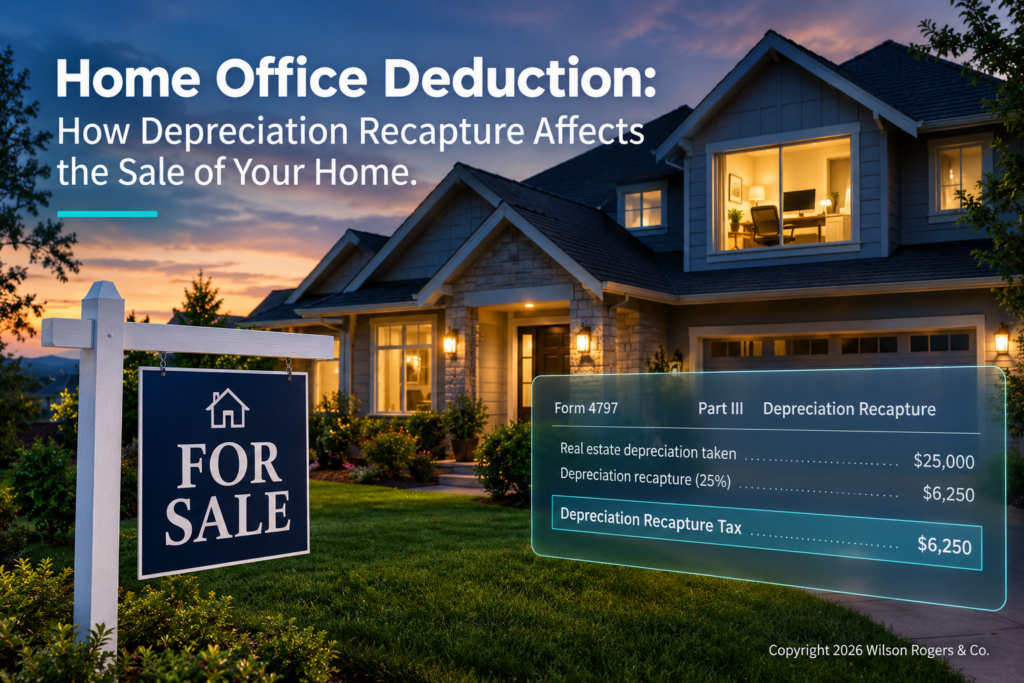
Home Office Deduction: How Depreciation Recapture Affects the Sale of Your Home


Using part of your home for business can provide meaningful tax savings through the home office deduction. Homeowners and renters alike can benefit from this deduction, but if you later sell your home, there’s an important consideration: depreciation recapture. Understanding how this works can help you plan ahead and avoid surprises at tax time.

Requirements for the Home Office Deduction

To claim the home office deduction, two key requirements must be met. First, the space must be used regularly and exclusively for business purposes. A home office cannot double as a guest room, den, or entertainment space. Occasional or incidental business use, such as quarterly meetings, does not qualify. Second, your home must serve as your principal place of business. Even if you conduct work elsewhere, you may qualify if you use your home substantially and regularly. Separate structures, such as garages, studios, or barns, can also qualify if they are used exclusively for business.

How to Claim the Deduction

Deductions are generally based on the percentage of your home used for business. There are two calculation methods. The simplified method allows a deduction of $5 per square foot, up to 300 square feet, for a maximum of $1,500. Depreciation is not claimed under this method, which means no recapture tax applies when you sell, and recordkeeping is minimal.

The regular (actual expense) method calculates the actual expenses of operating your home, including mortgage interest, utilities, insurance, repairs, and depreciation. Expenses are allocated based on the business-use portion of your home, and deductions are reported on IRS Form 8829. While this method often results in larger deductions each year, it triggers depreciation recapture when you sell your home.

Where you report the deduction depends on your business type. Self-employed individuals typically report it on Schedule C, Line 30. Employees may report eligible expenses on Schedule A as itemized deductions (if allowed). Partnerships, LLCs, and S-Corps usually handle the deduction through accountable plans or entity-level reimbursements.

Depreciation Recapture Explained

Depreciation reduces your taxable income in the years you claim it, but when you sell your home, the IRS requires you to recapture the depreciation for the business-use portion. Depreciation recapture is taxed at a maximum rate of 25%, separate from long-term capital gains, which are generally taxed at 15%. Even if you didn’t claim all allowable depreciation, the IRS requires recapture of any portion that could have been claimed.

Example:

  • Home purchase price: $300,000
  • Business-use portion: 10%
  • Depreciation claimed: $10,000
  • Sale price: $500,000

Recapture: $10,000 taxed at up to 25%
Remaining gain: $190,000 may qualify for the capital gains exclusion ($250,000 single / $500,000 married filing jointly)

Capital Gains Exclusion and the Home Office

The capital gains exclusion allows homeowners to exclude up to $250,000 (single) or $500,000 (married filing jointly) of gain on the sale of their primary residence if they owned and lived in the home for at least two of the last five years. If your office is inside the home, the exclusion generally applies to the entire home, but depreciation recapture still applies.

If your office is in a separate structure, the IRS treats it as a separate dwelling unit. You must meet ownership and use requirements for both the home and the structure to apply the exclusion. If these requirements are not met, gains from the office portion are fully taxable, including depreciation recapture at 25% and any additional gain at 15%.

Planning Strategies Before Selling

Business owners can take steps to minimize the impact of depreciation recapture. If the office is in a separate structure, consider not claiming home office deductions for at least two years before selling to maximize the exclusion on the full property. If the office is inside your home, continue claiming deductions, since recapture is required regardless of whether you claimed them.

Maintaining detailed records is essential. Keep track of expenses, depreciation, and the square footage of your office. Accurate documentation ensures correct calculation of recapture and can help prevent errors or audits.

Why Depreciation Recapture Isn’t a Penalty

It’s important to understand that depreciation recapture is not a penalty. It simply balances the tax benefit you’ve already received. Depreciation reduces taxable income over the years, providing real savings, and recapture ensures the IRS taxes the portion of gain already offset by those deductions. Even with recapture, the home office deduction remains a valuable tool for business owners, helping offset real expenses and reflecting the dual purpose of your home as both a residence and a workspace.


S-Corp Home Office Deduction

Taking the home office deduction is fairly simple when you’re a self-employed individual and file Schedule C.  In those instances, you simply indicate on Form 8829 the percentage of your home that is used for work, the costs to maintain your space, and that amount will go on your Schedule C as a deduction.

If you are a member of a partnership or multimemeber LLC, then you use a similar calculation to the one listed above (see the worksheet on page 27).  However, you deduct the expenses as unreimbursed partnership expenses on Schedule E.

But what if you’re a member of a S-Corp?  Well, if you still want that home office deduction, just be prepared to do a few workarounds to get it.

25 years ago Congress enacted a law prohibiting the deduction of expenses related to the rental of a portion of one’s home to their employer.  The law was enacted in response to a Supreme Court decision [Feldman v. Commissioner].  The rental arrangement involved was viewed as an attempt to circumvent the purpose of Internal Revenue Code Section 280A, which limits deduction of expenses allocable to the business use of one’s home.

Given that office-in-the-home expenses are not allowable if the office is rented to one’s employer, an S Corporation shareholder-employee “could” deduct office-in-the-home expenses as miscellaneous itemized deductions.  But these deductions are of little or no value because of the 2% income floor imposed on Schedule A, and the add back of such deductions in computing alternative minimum taxable income.

Based on the above, the old workaround that was often used was:

  • create a rental property on Schedule E of the individuals return, and include a portion of all expenses (rent, mortgage interest, property tax, insurance, utilities, etc). You would then report an amount of income that’s equal to;
  • rent expense that you report on your S-Corp tax return. Those two amounts will offset (the rent deduction on your S-corp return and the rent income on your individual return); and you will be left with the home office deduction.

Well,  the IRS got tired of sifting through fake rental properties and instead recommends that the employee submit an expense report as part of what’s called an “accountable plan.”

So based on this guidance, here is the new way of deducting home office expenses if you are a member of a S-Corp:

  • Draft an accountable plan agreement for your company.  It will outline what expenses are eligible for reimbursement, how they will be paid, etc.  A sample plan can be found here, or you can create your own.
  • Calculate the percentage of your home that is used exclusively for business purposes.  Divide the square footage used for business by the total square footage of the home and multiply by 100.
  • Calculate the total amount of eligible reimbursable expenses (see Form 8829 above).  Multiply each amount by the percentage of business use calculated in the step above and enter the results on the expense form that you use for your accountable plan.
  • Prepare expense reports as the employee and turn them in to your company on a regular basis.  Attach receipts or other documentation to the form to substantiate them.
  • Cut the check from the business account and deposit it into your personal account. Attach a copy of the check to the form as documentation that these were paid.
  • Enter the amount of the payment into your S corporation’s records as a reimbursement for employee expenses. Post each expense claimed to the appropriate expense account so that these expenses may be deducted from the corporation’s income on its tax return.

And there you have it.  You have now created a tax-deductible business expense for the S-corp, and you don’t have to report the reimbursement as income.

Could you be paying more in taxes than you should?

As a business owner, there are some tax benefits to being structured as a S-Corp.  The biggest one (that almost everyone knows) is the potential to reduce/minimize their employment taxes.  But did you know that through some deliberate and diligent tax planning, you could be able to legally reduce your tax burden further?

If your business does $100K (or more) in revenue, you would be a perfect candidate for our S-Corp Tax Reduction Analysis.  This analysis (a package valued at $1097, but $345 to you for a limited time), includes the following:

  • One hour investigative session to understand your business operations and potential tax levers
  • Review of the past 3 years of filed Form 1120S tax returns to unearth potentially missed deductions or tax savings
  • Formulation of potential tax strategies that if implemented could reduce the underlying tax liability
  • Comprehensive report indicating findings, tax strategies and steps to implement
  • Complementary copy of Jared’s book How to Slash Your Taxes Legally and Ethically

Furthermore, this analysis is guaranteed by our 100% ironclad money back guarantee.  If we can’t find any tax savings that equal or exceed the cost of the analysis, we’ll refund your money, no questions asked!

To claim your analysis, simply email us via the address in the footer on this page or give our office a call at 773-239-8850.  We only have capacity to perform so many of these analysis per month so get yours NOW.  We look forward to working with you!

S-Corps and Taxation Considerations

An S corporation (sometimes referred to as an S Corp) is a special type of corporation created through an IRS tax election (you must first incorporate the business and then make the IRS election via Form 2553).  Many new business owners often contact us asking if this is a good form to conduct business under.  While there are advantages to operating as an S Corp, there are some things that one should consider prior to making the election.  Depending on your goals, one may find that it’s better to operate under another organizational structure.

Ownership Restrictions

Per IRS guidelines, S Corp owners (shareholders) must first meet the following criteria:

  • Limited to 100 or fewer persons/entities
  • Must be US citizens/residents (cannot be non-resident aliens)
  • Cannot be C Corporations (C Corp), other S Corps, limited liability companies (LLCs), partnerships or certain trusts
  • Any shareholder who works for the company must pay him or herself “reasonable compensation.” Basically, the shareholder must be paid fair market value, or the IRS might reclassify any additional corporate earnings as “wages”

Benefits

Many small business owners elect S Corp status for two main reasons:

  • Avoid double taxation on distributions
  • Allow corporate losses to flow through to its owners (however there are 3 loss limitations discussed later)

Other typical advantages include:

  • Limited liability protection. Owners are not typically responsible for business debts and liabilities.
  • Easy transfer of ownership. Ownership is easily transferable through the sale of stock.
  • Unlimited life. When a corporation’s owner incurs a disabling illness or dies, the corporation does not cease to exist.
  • Potential use of personal assets for business use.  Check out this post about S-Corp vehicle usage and this one for S-Corp home office usage.

Pass Through Taxation

What makes the S Corp different from C Corp is that profits and losses pass through to your personal tax return. Consequently, the business is not taxed itself, only the shareholders are taxed.  The amount which is taxed is determined by the shareholders basis (i.e. their interest in the business).  What is unique about S Corp basis is that it fluctuates depending on several things including the company’s operational performance.

Additionally, since the tax liability lies with the shareholder and not the corporation, individuals have to make sure that they receive enough money from the corporation in the form of distributions in order to satisfy their tax obligation.  Non dividend distributions aren’t taxable to the extent the shareholder has adequate basis.

Importance of Basis

It is important that a shareholder know their stock AND debt basis at all times. As such, it is imperative that it be calculated every year.  If the corporation allocates a loss or deduction to the shareholder, in order to claim it the shareholder needs to demonstrate that they have enough stock or debt basis.  For example, if a person invests $10,000 in a company (i.e. stock basis) and the company then passes through a $18,000 loss to them in a single year, only $10,000 will be deductible in that year.  The remaining $8,000 becomes “suspended” until the shareholder has adequate basis in the future.

Loss Limitations

As mentioned above, losses are limited to the extent that an owner has basis.  However, there are in fact three limitations which could cause a loss to be nondeductible at any given time.  Each limitation must be met in the following order before a shareholder is allowed to claim a flow through loss:

  • Stock and Debt Basis Limitations
  • At Risk Limitations
  • Passive Activity Limitations

Calculating Stock Basis

A good way to think of stock basis is in terms of a checking account.  Basis essentially equals deposits and earnings less any withdrawals made.  Furthermore, similar to a bank account (with no overdraft protection) basis cannot go negative – that is more cannot come out than goes in.

  • Initial basis typically starts with the money a shareholder paid for the S Corp shares, property contributed to the corporation, carryover basis if gifted stock, stepped-up basis if inherited stock or basis of C Corp stock at the time the C Corp converts to an S Corp.
  • Subsequent basis is made via adjustments which are typically recorded at the end of the corporations tax year.  First they are increased by income items, then decreased by distributions and lastly decreased by deduction and loss items.  The order is important because if basis is positive before distributions but would be negative if all deduction items were subtracted (however, again, basis cannot be negative) then the excess loss would be suspended rather than the excess distribution being taxable.

Other Important Considerations

  • S Corps must pay reasonable compensation to a shareholder-employee in return for services that the employee provides to the corporation before non-wage distributions may be made to the shareholder-employee.
  • The instructions to the Form 1120S, U.S. Income Tax Return for an S Corporation, state “Distributions and other payments by an S corporation to a corporate officer must be treated as wages to the extent the amounts are reasonable compensation for services rendered to the corporation.”
  • Under section 7436 of the Internal Revenue Code, the IRS has the authority to reclassify payments made to shareholders from non-wage distributions to wages (which are subject to employment taxes).
  • Suspended losses and deductions due to basis limitations retain their character in subsequent years. Any suspended loss or deduction items in excess of stock and/or debt basis are carried forward indefinitely until basis is increased in subsequent years or the shareholder disposes of their stock.
  • In determining current year allowable losses, current year loss and deduction items are combined with the suspended loss and deduction items carried over from the prior year, though the current year and suspended items should be separately stated on the Form 1040 Schedule E or other appropriate schedule on the return.
  • If the current year has different types of loss and deduction items, which exceed stock and/or debt basis, the allowable loss and deduction items must be allocated pro rata based on the size of the particular loss and deduction items.
  • If a shareholder sells their stock, suspended losses due to basis limitations are lost. Any gain on the sale of the stock does not increase the shareholder’s stock basis. A stock basis computation should be reviewed in the year stock is sold or disposed of.
  • A non-dividend distribution in excess of stock basis is taxed as a capital gain on the shareholder’s personal return. Stock held for longer than one year is a long-term capital gain (LTCG).
Go to Top