12 Smart Habits That Can Help Reduce Your Business Tax Burden

Most business owners don’t want to spend more time thinking about taxes, they want to spend more time growing their business. The good news is that reducing your tax burden often isn’t about finding complicated tax strategies. It’s about building simple habits throughout the year.
Waiting until tax season to think about taxes can mean missed deductions, unnecessary penalties, and a larger tax bill than expected. Here are 12 habits that can help you keep more of what you earn while staying organized and compliant.
- Separate Business and Personal Finances
One of the easiest ways to improve your tax situation is to keep business and personal expenses separate. Use a dedicated business bank account and credit card so your bookkeeping stays clean and you don’t accidentally miss deductible expenses.
Why it matters: Clean financial records save time, reduce stress, and makes us tax preparers much more confident and decisive with your return.
- Review Your Financial Reports Every Month
Don’t wait until year-end to find out how your business is performing. Set aside time each month to review your Profit & Loss statement, cash flow, and major expenses.
Why it matters: Monthly reviews help you identify opportunities to reduce taxes before it’s too late to act.
- Keep Track of Every Business Expense
Small expenses add up over the course of a year. Software subscriptions, office supplies, marketing costs, professional memberships, and business meals may all be deductible when properly documented.
Common mistake: Waiting until tax season to search for receipts usually means some deductions get lost.
- Pay Estimated Taxes on Time
Many business owners are required to make quarterly estimated tax payments. Missing these deadlines can result in penalties and interest.
Planning ahead helps spread your tax payments throughout the year instead of facing one large surprise.
- Contribute to Retirement Accounts
Retirement plans can do more than prepare you for the future, they may also reduce your taxable income today.
Depending on your business structure, there may be several retirement plan options available that provide valuable tax benefits.
- Track Business Mileage
If you use your personal vehicle for business, keep an accurate mileage log throughout the year.
Trying to recreate mileage months later isn’t just difficult, it may also reduce the accuracy of your records.
- Don’t Overlook Home Office Expenses
If you legitimately qualify for the home office deduction, keeping good records is essential. Expenses such as utilities, internet, insurance, and maintenance may qualify depending on your situation.
Good documentation makes all the difference.
- Plan Major Purchases Before Year-End
Thinking about buying equipment, upgrading computers, or investing in new software?
The timing of these purchases can affect your tax liability. Planning ahead may allow you to maximize available deductions while still making smart business decisions.
- Meet With Your CPA Before Tax Season
One of the biggest mistakes business owners make is waiting until tax season to ask tax questions.
A year-end planning meeting gives you time to discuss strategies such as:
- Managing taxable income
- Retirement contributions
- Equipment purchases
- Estimated tax payments
- Potential tax credits
By the time your tax return is being prepared, many planning opportunities have already passed.
- Keep Your Bookkeeping Current
Accurate bookkeeping isn’t just for tax returns; it’s one of the best management tools a business owner has.
When your financial records are current, you can:
- Make better business decisions
- Identify unnecessary spending
- Prepare for tax season with confidence
- Reduce the likelihood of costly mistakes
- Stay Organized Throughout the Year
Instead of scrambling every spring, create simple weekly or monthly routines.
Examples include:
- Filing receipts
- Reconciling bank accounts
- Reviewing invoices
- Recording payroll
- Organizing important tax documents
A little consistency goes a long way.
- Ask Before You Make Big Decisions
Hiring employees, purchasing equipment, expanding locations, or changing your business structure can all have tax consequences.
A quick conversation before making a major decision often uncovers opportunities that aren’t available afterward.
The Bottom Line
The business owners who consistently reduce their tax burden aren’t necessarily the ones with the biggest budgets or the most complex businesses. They’re the ones who plan ahead.
Good tax planning starts long before tax season. By building a few simple habits into your routine, you’ll be better prepared to claim every deduction you’re entitled to, avoid unnecessary surprises, and make more informed financial decisions throughout the year.
At Wilson Rogers, we believe tax planning should be proactive, not reactive. Our goal is to help business owners understand what their numbers mean, avoid common pitfalls, and make confident decisions that support long-term success. When taxes become part of your year-round business strategy, you’re in a much stronger position to keep more of what you’ve worked hard to earn.
Ethical Standards for Tax Preparers
In the complicated world of taxation, where financial responsibilities intersect with legal obligations, the role of a tax preparer is both crucial and delicate. As tax season approaches, it becomes increasingly important to shine a light on the ethical standards that guide these financial professionals. In this blog post, we explore the essential ethical principles that should govern the conduct of tax preparers, ensuring not only compliance with the law but also the maintenance of trust and integrity in their crucial role.
There are several key ethical principles that tax preparers should follow, these includes:
- Confidentiality: the preparer has the responsibility to keep all of their client’s information confidential, even if the relationship ends, they must continue to follow this. The only time they should disclose information is with the client’s consent or when it is required by the law.
- Competence: they should also keep up to date with the latest tax laws and regulations in order to stay competent in their specific field. This includes providing services that they are qualified to provide and should refer clients to other professionals if they aren’t prepared.
- Integrity: tax preparers must be honest, credible, and trustworthy as it is their obligation to protect and enhance the trust of the client. This includes avoiding any conflicts of interest and not engaging in any activity that could damage their own reputation or profession.
- Due Diligence: Tax preparers should perform due diligence on their client information and should never prepare returns that are inaccurate or incomplete knowingly.
- Independence: tax preparers should not allow their personal interest to interfere with their personal judgment. This includes any relationship that could compromise their objectivity or integrity.
In addition to these general ethical principles, they must also comply with specific professional standards and regulations. They may vary depending on the jurisdiction in which the tax preparer is practicing and the specific area they are focused in. However, some of the most common standards and regulations include:
- Circular 230: These are a set of regulations issues by the US department of the Treasury that govern the practice of tax law. This also requires tax preparers to be competent, honest, and ethical in their dealings with clients.
- AICPA Statements on Standards for Tax Services: These are a set of standards issued by the American Institute of Certified Public Accountants that govern the preparation of tax returns. These standards require tax preparers to perform due diligence in order to disclose any material uncertainties and to avoid taking unreasonable positions.
- National Associations of Tax Professionals (NATP) Code of Ethics: this is made up of the code of ethics that are applied to all members of the NATP. The NATP Code of Ethics requires members to be honest, competent, and ethical when it comes to working with their clients.
If a tax preparer engages in any unethical conduct, they can potentially face a number of consequences, such as:
- Loss of professional license
- Fines and penalties
- These include fines up to $100,000 or $500,000 in the case of a corporation
- Criminal Chargers
- Imprisonment for up to three years with felony or misdemeanors being on your record
These consequences vary for each situation such as the penalty being less expensive as we mentioned or imprisonment being less time. Whatever the case maybe they are nothing to take lightly.
In conclusion, ethical standards are paramount for tax preparers as they navigate the complicated landscape of taxation. These standards, encompassing confidentiality, competence, integrity, due diligence, and independence, form the bedrock of responsible and honest conduct. Reinforced by specific professional standards, violations can lead to severe consequences, including the loss of professional licenses, substantial fines, and criminal charges. As tax preparers approach the challenges of tax season, faithfulness to these ethical principles is not only an expectation but an obligation. Upholding these standards is crucial for maintaining trust, safeguarding reputations, and preserving the integrity of the financial profession. In essence, ethical conduct is not just a guideline; it is an indispensable compass that guides tax preparers towards principled and responsible tax preparation.
Home Office Deduction: How Depreciation Recapture Affects the Sale of Your Home
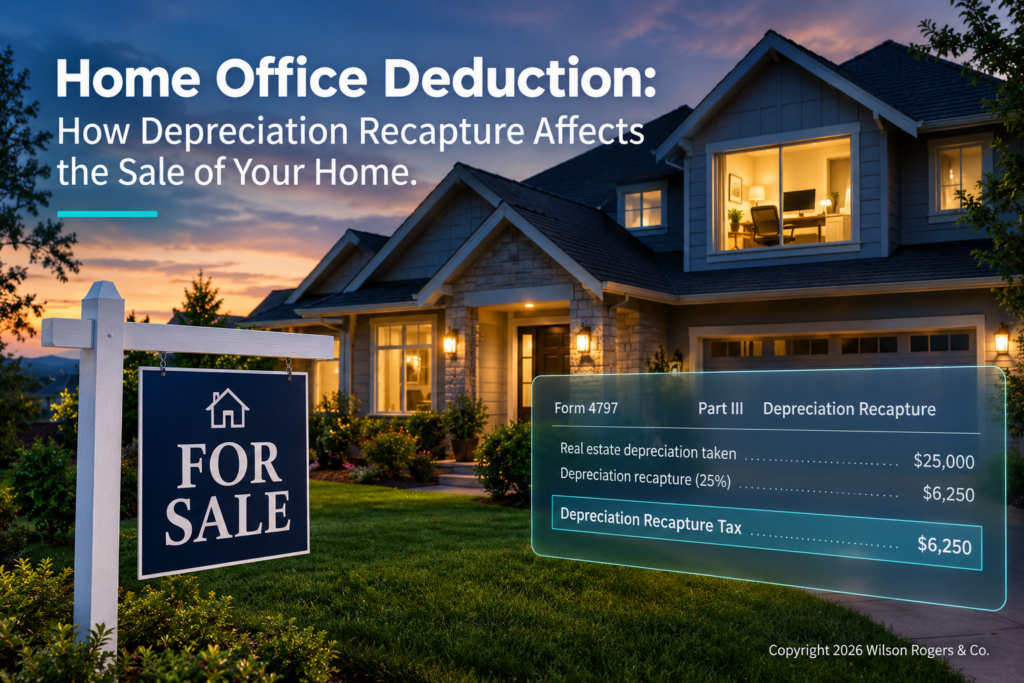
Using part of your home for business can provide meaningful tax savings through the home office deduction. Homeowners and renters alike can benefit from this deduction, but if you later sell your home, there’s an important consideration: depreciation recapture. Understanding how this works can help you plan ahead and avoid surprises at tax time.
Requirements for the Home Office Deduction
To claim the home office deduction, two key requirements must be met. First, the space must be used regularly and exclusively for business purposes. A home office cannot double as a guest room, den, or entertainment space. Occasional or incidental business use, such as quarterly meetings, does not qualify. Second, your home must serve as your principal place of business. Even if you conduct work elsewhere, you may qualify if you use your home substantially and regularly. Separate structures, such as garages, studios, or barns, can also qualify if they are used exclusively for business.
How to Claim the Deduction
Deductions are generally based on the percentage of your home used for business. There are two calculation methods. The simplified method allows a deduction of $5 per square foot, up to 300 square feet, for a maximum of $1,500. Depreciation is not claimed under this method, which means no recapture tax applies when you sell, and recordkeeping is minimal.
The regular (actual expense) method calculates the actual expenses of operating your home, including mortgage interest, utilities, insurance, repairs, and depreciation. Expenses are allocated based on the business-use portion of your home, and deductions are reported on IRS Form 8829. While this method often results in larger deductions each year, it triggers depreciation recapture when you sell your home.
Where you report the deduction depends on your business type. Self-employed individuals typically report it on Schedule C, Line 30. Employees may report eligible expenses on Schedule A as itemized deductions (if allowed). Partnerships, LLCs, and S-Corps usually handle the deduction through accountable plans or entity-level reimbursements.
Depreciation Recapture Explained
Depreciation reduces your taxable income in the years you claim it, but when you sell your home, the IRS requires you to recapture the depreciation for the business-use portion. Depreciation recapture is taxed at a maximum rate of 25%, separate from long-term capital gains, which are generally taxed at 15%. Even if you didn’t claim all allowable depreciation, the IRS requires recapture of any portion that could have been claimed.
Example:
- Home purchase price: $300,000
- Business-use portion: 10%
- Depreciation claimed: $10,000
- Sale price: $500,000
Recapture: $10,000 taxed at up to 25%
Remaining gain: $190,000 may qualify for the capital gains exclusion ($250,000 single / $500,000 married filing jointly)
Capital Gains Exclusion and the Home Office
The capital gains exclusion allows homeowners to exclude up to $250,000 (single) or $500,000 (married filing jointly) of gain on the sale of their primary residence if they owned and lived in the home for at least two of the last five years. If your office is inside the home, the exclusion generally applies to the entire home, but depreciation recapture still applies.
If your office is in a separate structure, the IRS treats it as a separate dwelling unit. You must meet ownership and use requirements for both the home and the structure to apply the exclusion. If these requirements are not met, gains from the office portion are fully taxable, including depreciation recapture at 25% and any additional gain at 15%.
Planning Strategies Before Selling
Business owners can take steps to minimize the impact of depreciation recapture. If the office is in a separate structure, consider not claiming home office deductions for at least two years before selling to maximize the exclusion on the full property. If the office is inside your home, continue claiming deductions, since recapture is required regardless of whether you claimed them.
Maintaining detailed records is essential. Keep track of expenses, depreciation, and the square footage of your office. Accurate documentation ensures correct calculation of recapture and can help prevent errors or audits.
Why Depreciation Recapture Isn’t a Penalty
It’s important to understand that depreciation recapture is not a penalty. It simply balances the tax benefit you’ve already received. Depreciation reduces taxable income over the years, providing real savings, and recapture ensures the IRS taxes the portion of gain already offset by those deductions. Even with recapture, the home office deduction remains a valuable tool for business owners, helping offset real expenses and reflecting the dual purpose of your home as both a residence and a workspace.
Why Does The IRS Hold EITC Refunds?
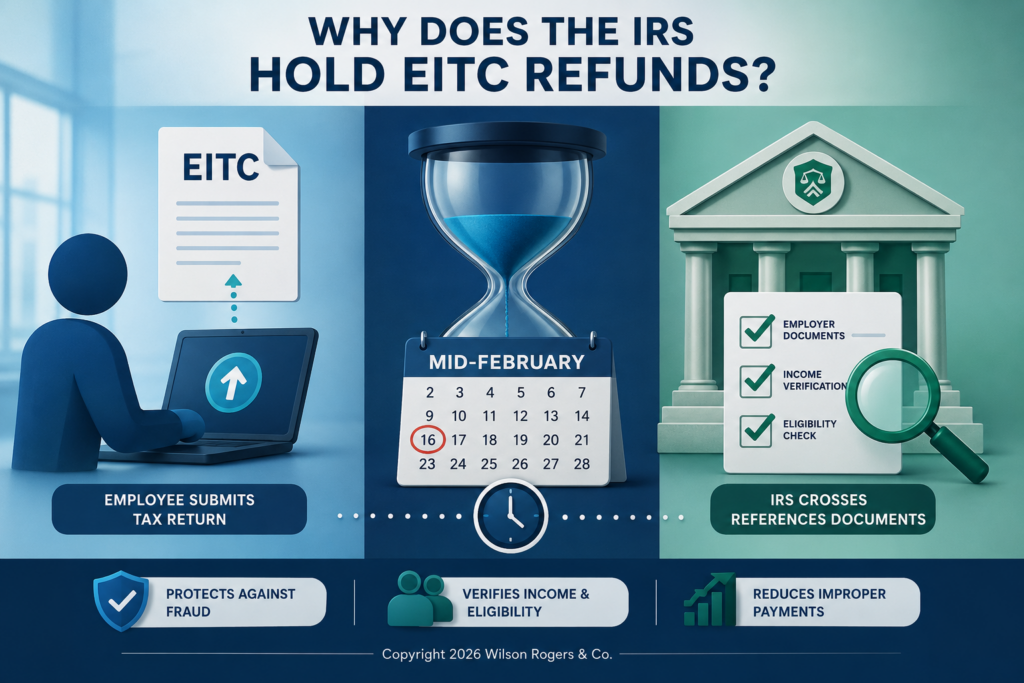
Understanding the EITC and Why Refunds Are Delayed by the IRS
The Earned Income Tax Credit (EITC) is a federal tax credit designed to support working individuals and families with lower to moderate income levels. It is intended to reduce tax liability and, because it is refundable, it can also increase a taxpayer’s refund—even when no federal income tax is owed. Eligibility for the credit is based primarily on earned income, such as wages, salaries, tips, and self-employment income. However, qualification is not determined by income alone. Filing status, the number of qualifying children, residency requirements, and valid Social Security numbers for all individuals on the return also play a critical role. Because of these combined factors, the EITC is one of the more complex credits in the tax code and requires careful compliance with IRS rules.
While the credit can provide a meaningful financial benefit, it is also subject to additional IRS scrutiny. This is especially true when it comes to the timing of refunds.
Why the IRS Holds EITC Refunds
Taxpayers who claim the EITC often notice that their refunds are issued later than expected, particularly when compared to returns without refundable credits. This delay is not the result of a processing issue, but rather a set of requirements and safeguards built into the tax system.
Federal law requires a refund delay
Under the Protecting Americans from Tax Hikes Act (PATH Act), the IRS is required to delay the issuance of refunds that include the EITC (as well as the Additional Child Tax Credit) until at least mid-February each year. This rule applies regardless of when the return is filed. Even if a taxpayer submits their return in January, the IRS is not permitted to release the refund before the mandated date. This timing requirement was implemented to allow additional verification before refunds are issued.
Increased focus on fraud prevention
The EITC has historically been one of the most frequently reviewed credits due to its high claim volume and susceptibility to errors and fraudulent filings. Common issues include incorrect dependent claims, mismatched income reporting, and identity theft-related filings.
The delay period gives the IRS additional time to evaluate returns for inconsistencies and potential fraud indicators before issuing refunds.
Verification of income and eligibility
EITC eligibility depends on information that must be independently verified, including wages reported by employers, dependent qualifications, and filing status accuracy. During the hold period, the IRS cross-references tax returns with third-party reporting documents such as W-2s and 1099s to confirm that the information provided is consistent.
This verification process is designed to ensure that only eligible taxpayers receive the credit and that refund amounts are accurate.
Reducing improper payments
Because the EITC is a refundable credit, it represents a significant portion of federal tax refunds each year. Even small inaccuracies can result in improper payments. The additional review period helps the IRS reduce these errors and maintain compliance with federal tax law.
What Taxpayers Should Expect
A delayed EITC refund is not necessarily an indication of an issue with a tax return. In most cases, it simply reflects the standard processing timeline required under federal law.
Once the PATH Act hold period concludes in mid-February, refunds are generally issued in the order they were received, assuming no additional review or verification is required.
However, further delays can occur if the IRS identifies discrepancies in income reporting, dependent information, or if additional identity verification is needed.
Conclusion
The Earned Income Tax Credit remains one of the most impactful credits available to working taxpayers, but it is also subject to enhanced oversight. The IRS refund delay associated with the EITC is not discretionary, it is a statutory requirement intended to reduce fraud, verify eligibility, and ensure accurate payment of refundable credits.
While the waiting period can be inconvenient, it serves an important role in maintaining the integrity of the tax system and ensuring that refunds are issued correctly.
How to Report Gambling Winnings and Losses
Gambling income often creates confusion at tax time because the reporting rules do not follow what most taxpayers naturally expect. Many assume they are only taxed on their “net” winnings for the year. However, the IRS does not allow gambling to be reported that way. Instead, winnings and losses are handled separately, and that distinction drives the outcome on your tax return.
Reporting W-2G Gambling Winnings
When you receive a Form W-2G, it means your gambling winnings have been reported to both you and the IRS. These forms are typically issued for larger payouts from casinos, sportsbooks, lotteries, or similar gambling activities that meet reporting thresholds. Even though a W-2G is issued, it does not change how the income is treated. The full amount shown on the form is taxable and must be included on your return.
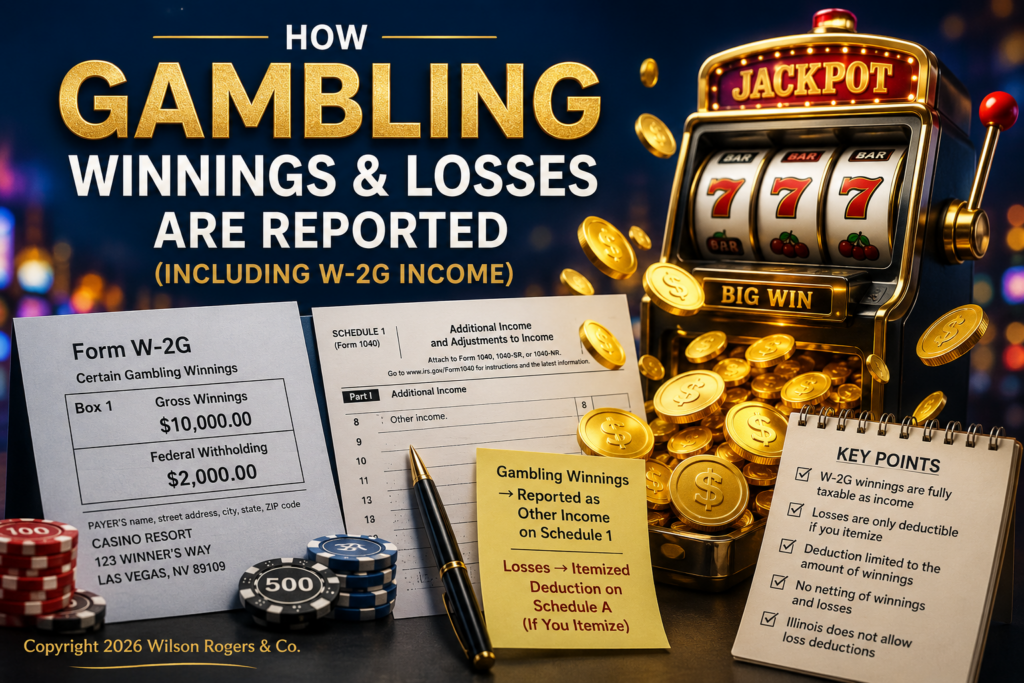
From a reporting standpoint, W-2G winnings are included as Other Income on Schedule 1 (Form 1040). That amount then flows through to your Form 1040 and increases your total taxable income. The key point here is that the IRS is always looking at the gross winnings reported on the form, not any net figure after losses. If federal income tax was withheld and shown on the W-2G, that withholding is treated as a prepayment toward your total tax liability. It is applied when you file your return, similar to wage withholding, but it does not change the fact that the full winnings are still taxable.
How Gambling Losses Are Treated
Gambling losses are not reported in the same place as winnings, and they do not automatically reduce the income shown on a W-2G. Instead, losses are only deductible if you itemize deductions on Schedule A. This is an important distinction because many taxpayers take the standard deduction, and in those cases, gambling losses provide no tax benefit at all. Even when itemizing, losses are limited. You can only deduct gambling losses up to the amount of gambling winnings reported on your return. There is no ability to create a net loss or carry excess losses forward to future years.
For example, if you have $10,000 in W-2G winnings and $12,000 in losses, your deduction is limited to $10,000. The remaining $2,000 is not usable for tax purposes.
No Netting of Winnings and Losses
One of the most common mistakes taxpayers make is assuming they can simply net their gambling activity for the year. The IRS does not allow this approach. Gambling winnings are reported in full as income, and gambling losses are only considered separately as an itemized deduction if you qualify. There is no single calculation on the tax return where the two are combined into a net result.
State Tax Considerations (Illinois)
Illinois follows a different approach than the federal return when it comes to gambling losses, and this is where taxpayers often get caught off guard. At the federal level, gambling losses can be deducted if you itemize, up to the amount of gambling winnings. Illinois does not follow this treatment in the same way. Illinois still taxes gambling winnings in full, but it generally does not allow a deduction for gambling losses. This means that even if you had significant losses during the year, those losses typically do not reduce your Illinois taxable income. Your gambling winnings remain fully included in your Illinois return, without the same offset you might see federally.
As a result, you can end up in a situation where your federal return reflects gambling losses (if you itemize), but your Illinois return still taxes the full amount of gambling winnings. This difference can be especially noticeable for taxpayers with regular gambling activity, where the overall economic result of the year does not match the taxable outcome at the state level.
Recordkeeping Requirements
The IRS places the responsibility for documentation on the taxpayer. This means maintaining records that support both winnings and losses, including dates, locations, types of gambling activity, and amounts. While casino or sportsbook statements can be helpful, they should not be relied on as the only source of documentation if records are ever requested.
Bringing It All Together
The most important takeaway is that gambling winnings reported on a W-2G are fully taxable and must be included in income regardless of losses during the year. Those winnings flow through Schedule 1 into Form 1040 and increase taxable income directly. Losses, on the other hand, are limited, conditional, and reported separately. They only provide a benefit if you itemize deductions and only up to the amount of reported winnings.
Once you understand that winnings and losses are reported in different parts of the return, the structure of how gambling is taxed becomes much clearer and easier to follow.
Click above to watch our Money Management and Tax Chit Chat video series!
Click Above For Your Top Secret Guide To Tax Reduction, Business Success and Solving IRS Debt Problems!
Click Above To Learn 111 Ways To Slash Your Tax Bill!