Understanding the “No Tax on Tips” Provision Under the One Big Beautiful Act (OBBA)
Tax rules continue to evolve, and every so often a provision gets a headline that sounds far simpler than what the law actually does. The “no tax on tips” provision under the One Big Beautiful Act (OBBA) is a good example of that. While the name suggests that tip income is no longer taxed, that is not what the law provides.
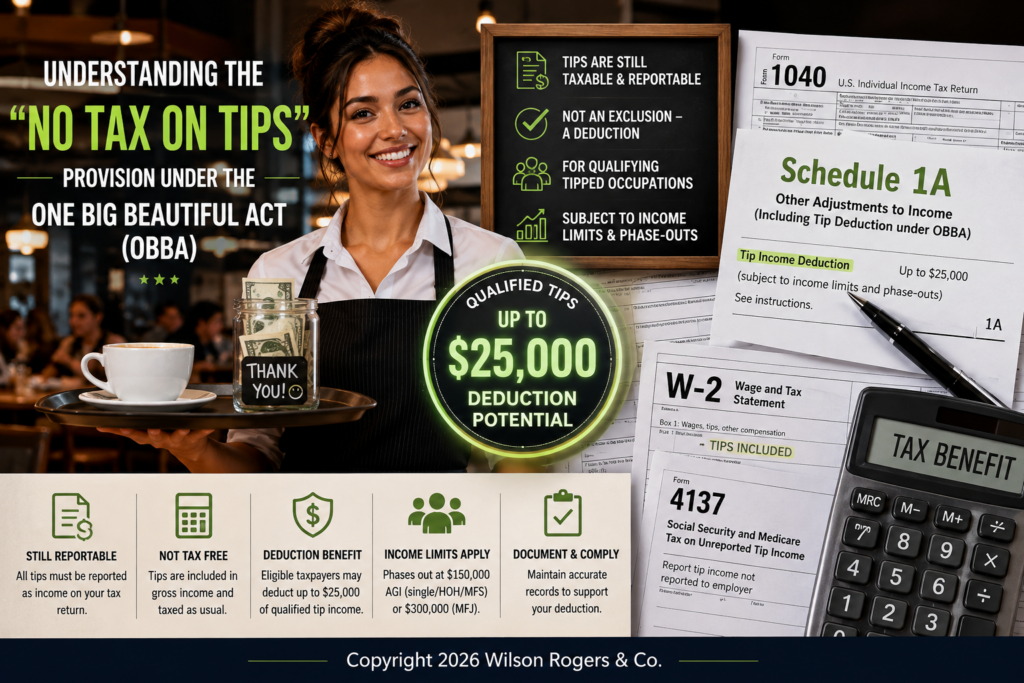
Tip income is still fully taxable and still must be reported. The core reporting rules have not changed. What OBBA introduces is not an exclusion from income, but a potential deduction that may reduce taxable income for certain qualifying tip earnings.
Tip Income is Still Reportable Income
The most important point to understand is that nothing about tip reporting has been removed or reduced. Employees and self-employed individuals are still required to report all tip income as part of gross income.
For employees, this continues to be reflected on Form W-2 as part of Box 1 wages. For self-employed individuals, tip income is still included in business receipts and ultimately flows through to Schedule C and Form 1040.
So despite the branding of “no tax on tips,” the income itself is still very much part of the tax system. The change occurs later in the return process, not at the reporting stage.
What the Provision Actually Does
Under OBBA, certain taxpayers may be eligible for a federal income tax deduction tied to qualified tip income. This is where the terminology often causes confusion. The law does not remove tips from taxable income. Instead, it allows a deduction against taxable income if the tips meet specific requirements. To qualify, the income must come from occupations that customarily and regularly received tips prior to December 31, 2024. This keeps the benefit focused on traditional tipped industries such as restaurant staff, bartenders, salon workers, and similar service-based roles.
Not all payments labeled as tips qualify. Service charges, mandatory gratuities, and standard wages are not included in the definition, even if they may resemble tips in practice.
How the Tax Benefit Is Applied
Even when tip income qualifies, it is still included in gross income. There is no exclusion at the wage or income reporting level.
Instead, the benefit is applied later as an adjustment to income. This means the taxpayer first reports all income normally, and then, if eligible, applies a deduction that reduces taxable income. This structure is important because it changes how the benefit is felt. Rather than removing tax from tip income entirely, it reduces overall taxable income after everything has already been reported.
Income Limits and Phase-Out Rules
The deduction is not unlimited and is subject to both a cap and income-based reductions. The maximum deduction allowed under OBBA is $25,000 per year. However, not every taxpayer will receive the full amount. The benefit begins to phase out once adjusted gross income exceeds certain thresholds. For single filers, head of household, and married filing separately, the phase-out begins at $150,000 of AGI. For married filing jointly, the threshold is $300,000. As income increases above these levels, the deduction is gradually reduced until it is fully phased out.
For self-employed taxpayers, there is also an additional limitation. The deduction cannot exceed the net profit of the business generating the tip income, which prevents the deduction from creating or increasing a loss position.
How Tip Income Is Reported Under Current Rules
Despite the introduction of this provision, the way tip income is reported has not changed. Employees still receive Form W-2 reporting their wages, including tip income in Box 1. Employers may separately track qualifying tip amounts for reporting purposes, but the overall structure remains the same. For individuals, all tip income continues to flow into Form 1040 as part of gross income. There is no separate exclusion or adjustment at the wage level. The only difference appears later in the return, where eligible taxpayers may apply the deduction.
Where the Deduction Appears on the Tax Return
The deduction is claimed on Schedule 1A of Form 1040, which is a new schedule introduced beginning in 2025 under OBBA. This schedule is used for “Other Adjustments to Income,” including several new provisions created by the legislation. In general, the deduction is based on either qualified tips reported by the employer on Form W-2 or tip income reported directly by the taxpayer on Form 4137 when applicable.
Regardless of the reporting method, the key requirement is that the income must be properly documented and traceable through official records.
Documentation and Compliance Requirements
As with most tax provisions tied to income adjustments, documentation is essential. The IRS will expect consistency between employer reporting and taxpayer reporting, and discrepancies can create issues during review. Supporting documentation may include payroll records, employer tip allocation reports, Form W-2, and Form 4137 when tips are not fully captured through payroll systems.
Accurate reporting matters not just for compliance, but also for ensuring the deduction is not disallowed due to incomplete or inconsistent records.
Final Takeaway
Despite its name, the “no tax on tips” provision does not eliminate taxation on tip income. Instead, it creates a targeted deduction that reduces taxable income for qualifying taxpayers in certain tipped occupations. The income is still reported, still tracked, and still subject to the same reporting rules as before. The difference lies in how the tax calculation is adjusted after reporting is complete.
As with most tax law changes, the real impact comes down to details, documentation, and income level. For taxpayers who rely on tip income, understanding how this provision fits into the broader return is key to avoiding confusion at tax time.
A Guide to the “No Tax on Overtime” Provision in the OBBA
Understanding the “No Tax on Overtime” Provision Under the One Big Beautiful Act (OBBA)
One of the more commonly misunderstood changes introduced under the One Big Beautiful Act (OBBA) is the “no tax on overtime” provision. At first glance, the name suggests that overtime pay is no longer taxable. In reality, that is not the case. This provision does not eliminate tax on overtime wages. Instead, it creates a limited deduction that applies only to a specific portion of overtime compensation, and only when it is properly identified, calculated, and reported.
What “No Tax on Overtime” Actually Means
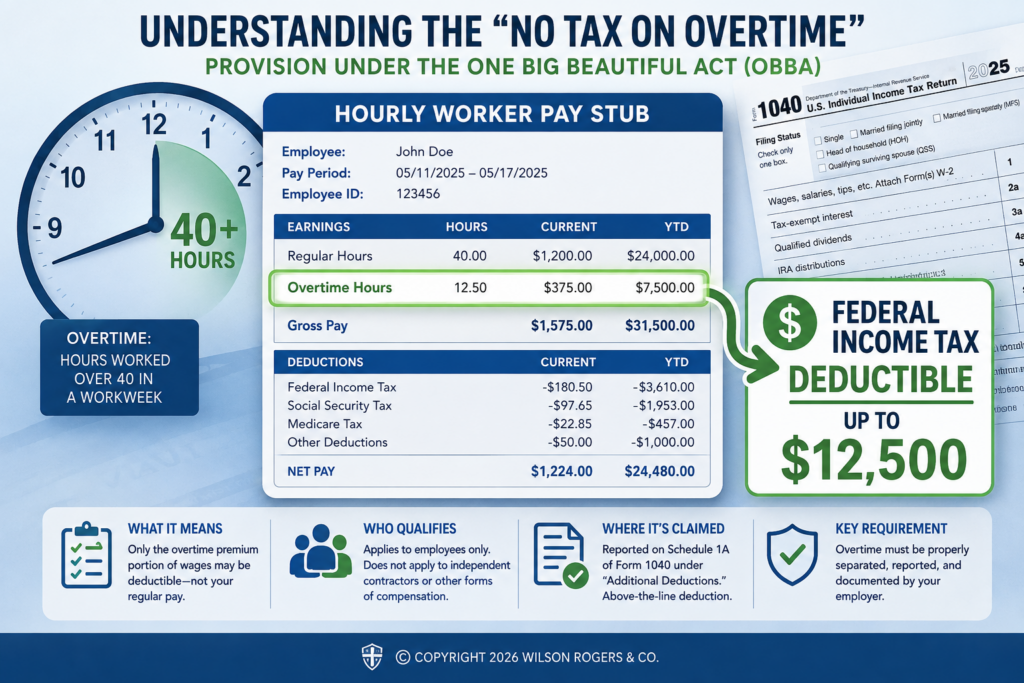
Under OBBA, the provision applies only to the overtime premium portion of wages. This is the additional amount paid above an employee’s regular hourly rate for hours worked beyond standard thresholds. Regular wages remain fully taxable, only the premium portion may qualify for the deduction. Overtime is generally defined under FLSA (Fair Labor Standards Act) rules, typically for hours worked over 40 in a workweek. This provision applies strictly to employees and does not extend to independent contractors or other forms of compensation such as bonuses. It is also important to understand that simply working overtime is not enough to qualify. The overtime must be separated into its regular rate and overtime premium, and only the premium portion is eligible for consideration.
Limits and Income Phase-Out Rules
Like most tax provisions, the overtime deduction includes strict limitations. The deduction for qualified overtime compensation is capped at $12,500 per year for most filers and $25,000 per year for Married Filing Jointly.
The benefit also phases out based on income. The phase-out begins when adjusted gross income exceeds $150,000 for Single, Head of Household, and Married Filing Separately, and $300,000 for Married Filing Jointly. As income increases beyond those thresholds, the deduction is gradually reduced until it is fully phased out.
Employers are required to separately account for qualified overtime compensation. This reporting requirement is part of the framework that ensures proper identification of eligible amounts.
How Overtime Is Reported
Even with this provision, overtime reporting has not changed at its core. On Form W-2, total wages are still reported in Box 1, which includes both regular and overtime earnings. However, the overtime premium portion must now be separately identified using updated IRS wage codes or reporting fields.
On Form 1040, overtime income is still included in gross wages. The key difference is that the tax benefit is not applied at the wage level. Instead, it is calculated later in the return as an adjustment to income.
Where the Deduction Is Claimed
The deduction is reported on Schedule 1A of Form 1040 under “Additional Deductions.” This is a new OBBA-related line item beginning in 2025. This is considered an above-the-line deduction, meaning it reduces adjusted gross income before either the standard deduction or itemized deductions are applied. This structure is significant because it can affect taxable income more broadly than a typical below-the-line deduction.
Documentation and Verification Requirements
Proper documentation is a key part of this provision. The IRS will expect clear support showing how overtime was calculated and separated from regular wages.
Pay stubs alone that simply label overtime are not sufficient. The underlying breakdown must clearly show regular pay versus overtime premium amounts. Verification should be based on employer payroll records, which serve as the primary source of truth, followed by pay stubs as supporting documentation. Employee statements or estimates are not reliable on their own and should not be used in place of formal records. Consistency across all documentation is essential. The classification of overtime must match across payroll systems, W-2 reporting, and any supporting forms used in the return.
Final Takeaway
The “no tax on overtime” provision under OBBA does not eliminate taxation on overtime earnings. Instead, it provides a limited deduction that applies only to the overtime premium portion of wages and only for taxpayers who meet specific income and reporting requirements.
While the provision may offer meaningful tax relief for eligible individuals, it depends heavily on accurate payroll reporting, proper classification of wages, and strong documentation. As with many tax changes, the details determine the outcome, and precision in reporting is essential for compliance.
How OBBA New Car Loan Interest Deduction Works
Understanding the New Car Loan Interest Deduction Under the OBBA
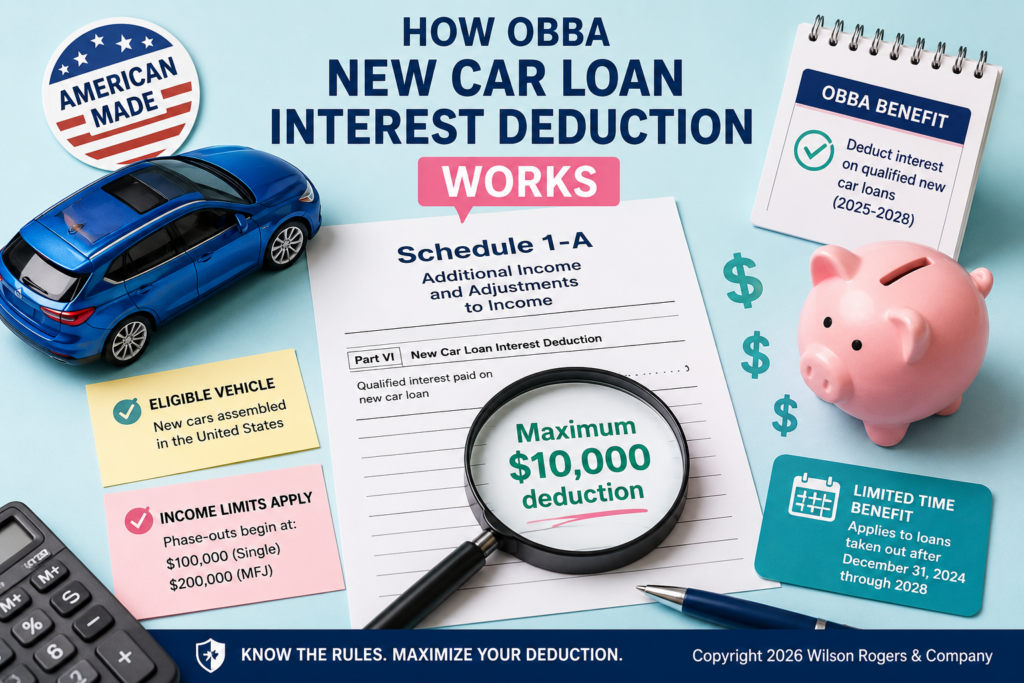
The One Big Beautiful Act (OBBA) introduces a new deduction for car loan interest that can be easy to misunderstand or misapply if the requirements aren’t carefully reviewed. While it may sound straightforward, the details around vehicle eligibility, loan structure, and income limits are critical. Missing any one of these rules can result in claiming a deduction that doesn’t actually apply.
Below is a breakdown of how it works, who qualifies, and how it must be reported.
What This Deduction Is
Under the OBBA, taxpayers may deduct interest paid on a qualified passenger vehicle loan. The key distinction here is that only the interest portion of the loan qualifies—not the purchase price, not the down payment, and not any related costs like insurance or registration. Another important feature is how the deduction is claimed. It is available regardless of whether you itemize deductions, which makes it more broadly accessible than many traditional tax breaks. Instead of being reported on Schedule A, it is taken on Schedule 1A, reducing your adjusted gross income directly.
Vehicle Qualification Requirements
This is the most important part of the rule set, and it cannot be overlooked. Before considering any interest amounts, the vehicle must be confirmed as qualifying.
The vehicle must be for personal use and cannot be used for business or mixed-use purposes. It must be a passenger vehicle and must have final assembly occurring in the United States. It also needs to meet IRS passenger vehicle weight limits.
In addition to the vehicle requirements, the loan itself must also qualify. The loan must be incurred after 2024 and must be secured by a first lien, meaning it is a secured loan used specifically to purchase the vehicle. If any of these requirements are not met, the deduction does not apply.
Caps, Phase-Outs, and Reporting
The deduction is capped at $10,000 of interest per tax year. It begins to phase out when adjusted gross income exceeds $100,000 for single filers and $200,000 for married filing jointly. Once income exceeds these thresholds, the available deduction is gradually reduced until it is fully phased out.
How to Report the Deduction
The deduction is calculated and reported on Schedule 1A of Form 1040. This is a deduction, not a credit, meaning it reduces taxable income rather than directly reducing tax liability.
Proper documentation is also required. Taxpayers must have lender interest documentation such as Form 1098-V or a similar statement to support the deduction.
Important Reminder for Business Vehicles
Business vehicle interest follows entirely different rules and must not be combined with this deduction. The OBBA provision applies strictly to qualified personal-use vehicles, and blending business interest into this calculation would result in an incorrect application of the rules.
In Summary
This deduction is temporary and is currently available for tax years 2025 through 2028. Proper application requires careful verification of vehicle eligibility, loan qualifications, adjusted gross income thresholds, and correct reporting on Schedule 1A. While it can provide meaningful tax savings, it is highly dependent on meeting all qualification rules exactly as outlined.
What is Circular 230 & Why Taxpayers Can Feel at Ease
Ever feel nervous handing over your tax documents to someone else? You’re not alone. Every year, taxpayers trust preparers with their most personal financial information—income, investments, dependents, and more—hoping everything is done correctly.
The good news? There’s already a safeguard in place to protect you and hold your preparer accountable. It’s called Circular 230, and it’s one of the most important—but least known—rules in the tax world.
What Exactly is Circular 230?
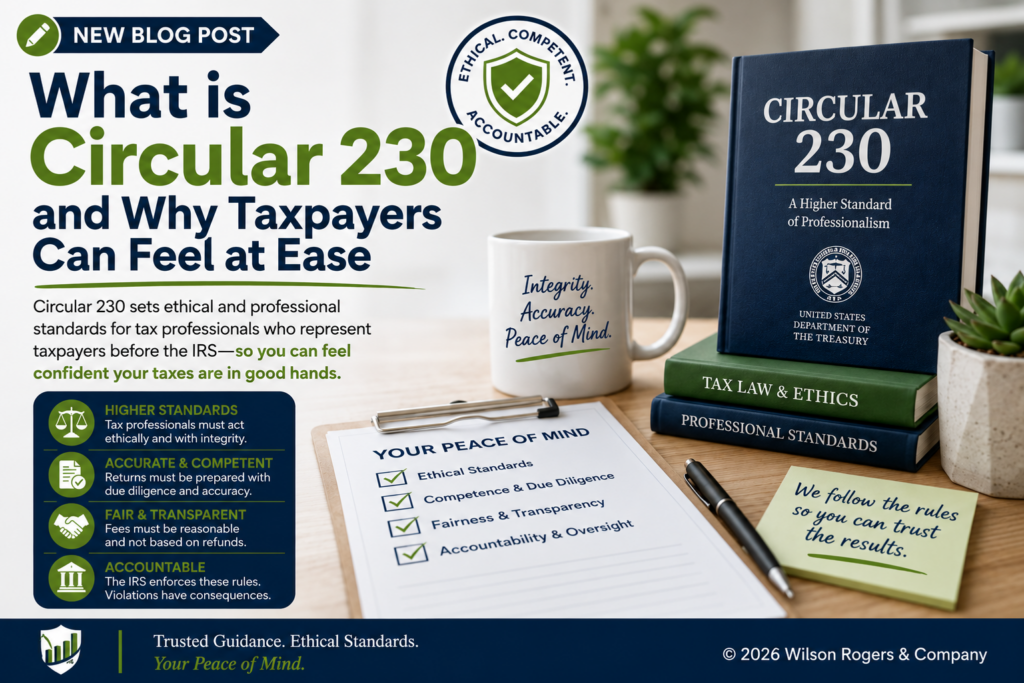
Circular 230 is an official publication from the U.S. Department of the Treasury. It sets the rules and ethical standards for professionals who represent taxpayers before the IRS.
This includes CPAs, Enrolled Agents (EAs), tax attorneys, and other individuals authorized to practice before the IRS. Essentially, if someone is legally allowed to handle your taxes, they must follow Circular 230.
Think of it as the IRS’s code of conduct for tax professionals. It ensures that your preparer acts with integrity, honesty, and professionalism—giving you confidence that your taxes are in capable hands.
How Circular 230 Protects You
Circular 230 exists not just for professionals, but for taxpayers. It ensures that anyone handling your return is competent, ethical, and accountable.
First, it holds preparers to a higher standard. They must act ethically, avoid conflicts of interest, and exercise due diligence. Misleading clients, making unrealistic promises, or taking risky tax positions is not allowed.
Second, it requires accuracy and competence. Tax professionals must verify information and ensure returns are correct. This reduces the risk of errors, penalties, or audits from sloppy or negligent work.
Third, it promotes fairness. Circular 230 regulates fees in many cases, preventing unreasonable or contingent charges. You can trust you’re being charged fairly, not based on the size of your refund.
Finally, it enforces accountability. The IRS Office of Professional Responsibility monitors compliance, and a preparer who acts unethically can be suspended or barred from practice. That oversight means you’re not on your own if something goes wrong.
Why This Matters to You
Working with a preparer covered under Circular 230—like a CPA, EA, or tax attorney—gives you peace of mind. They are legally bound by federal ethics and practice standards, required to act in your best interest, and can face real consequences for misconduct.
Put simply, Circular 230 gives you a safety net every time you file. Your preparer is trained to handle your taxes responsibly, accurately, and ethically.
Your Role as a Taxpayer
Circular 230 protects you, but you still play a key role in keeping your tax process safe. Always confirm your preparer’s credentials, review your return before signing, keep copies of your records, and provide accurate information. Being proactive helps protect both you and your preparer.
Final Thoughts
Most taxpayers never think about Circular 230, but it works quietly in the background to keep the tax system ethical, fair, and accountable. It’s why you can hand over your financial documents to a qualified preparer and trust that they are required to act professionally.
Behind every trusted tax professional is a set of IRS-enforced rules designed to protect you. Circular 230 gives taxpayers peace of mind, knowing their preparer is qualified, ethical, and committed to doing things the right way—every single time.
Benefits of E-Filing vs. Paper Filing
E-Filing vs. Paper Filing: Which Is Better for Taxpayers?
When tax season arrives, one of the first decisions taxpayers face is how to file their return. While paper filing was once the standard, electronic filing—commonly known as e-filing—has become the preferred method for both taxpayers and the IRS. And for good reasons. E-filing offers speed, accuracy, and security that paper simply can’t match.
Whether you file on your own or work with a tax professional, understanding the benefits of e-filing can help you make a confident, informed choice.
Faster Processing Means Faster Refunds
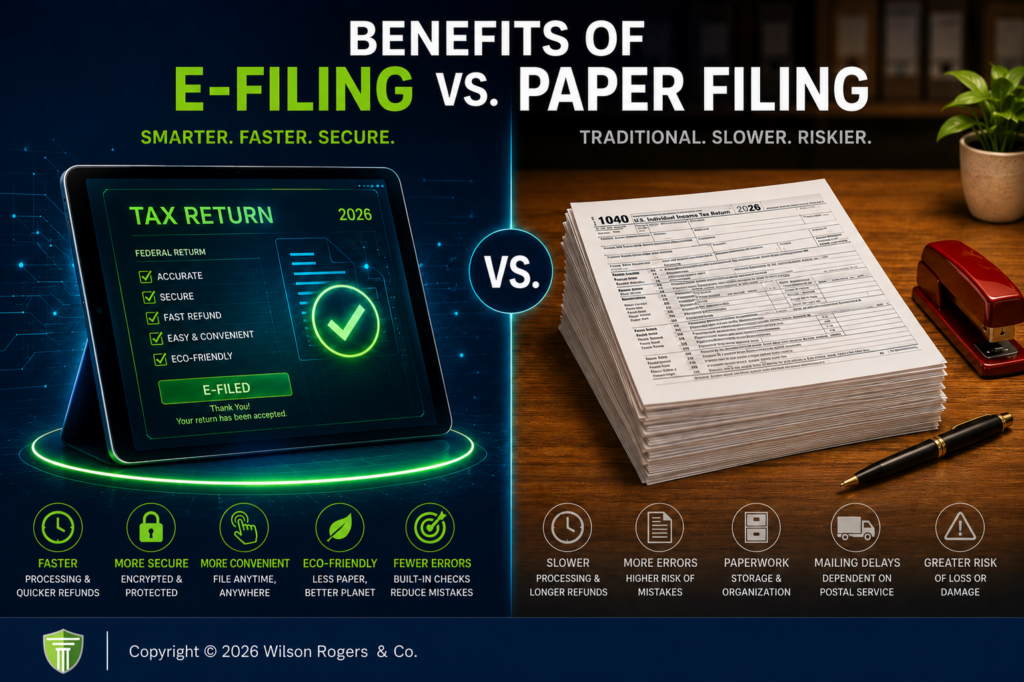
One of the most significant advantages of e-filing is how quickly your return moves through the IRS system. Electronic returns are transmitted instantly and begin processing within hours. In most cases, taxpayers who e-file and choose direct deposit receive their refunds in 1–3 weeks.
Paper returns, on the other hand, must travel through the mail, wait in IRS processing queues, and be manually entered into the system. This often results in 6–12 week wait times—and longer during IRS backlogs.
If getting your refund quickly is a priority, e-filing is the clear winner.
Greater Accuracy and Fewer IRS Notices
E-filing significantly reduces the risk of mathematical errors and missing information. Tax software automatically performs calculations, checks for inconsistencies, and flags required fields before the return is submitted. The IRS reports that e-filed returns have a much lower error rate compared to paper filings.
With paper returns, even a small mistake—such as a mismatched Social Security number or an overlooked signature—can trigger delays or IRS notices.
E-filing helps avoid these issues and ensures your return starts on the right foot.
Immediate Confirmation of Submission
Waiting and wondering whether the IRS received your paper return can be stressful. With e-filing, you receive electronic confirmation that your return has been received and accepted. No guessing, no tracking numbers, and no risk of lost mail.
For taxpayers who value peace of mind, this acknowledgment is a major benefit.
Enhanced Security and Data Protection
E-filing systems use encrypted, secure channels to protect your sensitive financial information – the same level of protection used by major banks. Paper returns, however, can be lost, misdelivered, or even stolen while being mailed.
If safeguarding your personal information is a top priority, e-filing offers the strongest layer of protection.
Easy Access to Prior-Year Tax Documents
When you e-file, your tax professional or software program securely stores your return and supporting documents. If you need a copy for a mortgage, loan application, or audit, retrieving it takes seconds.
Paper returns can be misplaced or damaged, creating stress when documentation is needed most.
Environmentally Friendly
E-filing cuts down on unnecessary paper and reduces waste. It’s a simple way to go greener during tax season.
Required for Many Preparers and Businesses
The IRS requires certain tax preparers and many businesses to electronically file once they meet specific thresholds. E-filing helps ensure compliance and avoids penalties, making it the practical choice for most professionals.
When Paper Filing May Be Necessary
Although e-filing is the preferred method, there are a few situations where paper filing may still be required or beneficial:
- Filing After the E-File Deadline
Once the IRS e-file system shuts down for the season—typically in October—late returns must be submitted on paper. This often happens when taxpayers miss both the regular deadline and any extension deadline.
- Returns That Cannot Be E-Filed
Certain uncommon forms, elections, or specialized filings cannot be submitted electronically. For example, if your return includes forms the IRS does not support for e-file, a paper return may be necessary.
- Correcting Identity or Data Issues
If the IRS rejects an e-filed return due to mismatched Social Security numbers, prior-year AGI problems, or identity theft flags—and the issue can’t be resolved electronically—a paper return may be required.
- Amended Returns (in rare cases)
Although most amended returns can now be e-filed, some older tax years or special situations still require mailing a paper Form 1040-X.
- Filing Without Proper E-File Access
Taxpayers with limited technology access or those who prefer physical signatures in rare circumstances may choose paper filing, though this is far less common.
While these situations exist, they are the exception—not the rule. For the vast majority of taxpayers, e-filing remains the most efficient and reliable option.
Conclusion
While both e-filing and paper filing will get your tax return to the IRS, the benefits of e-filing—faster refunds, fewer errors, stronger security, and immediate confirmation—make it the smarter choice for most taxpayers. Paper filing still plays an important role in special situations, such as filing after the e-file deadline or handling uncommon forms the IRS doesn’t support electronically. But for everyday taxpayers and most businesses, e-filing remains the simplest, safest, and most efficient way to stay compliant during tax season.
Click above to watch our Money Management and Tax Chit Chat video series!
Click Above For Your Top Secret Guide To Tax Reduction, Business Success and Solving IRS Debt Problems!
Click Above To Learn 111 Ways To Slash Your Tax Bill!