Should I Hire a Tax Professional For My Small Business?

Do I really need a tax professional?

For taxpayers with the simplest income tax returns, do-it-yourself software and websites often seem like the way to go.  These individuals often have only one source of income (i.e. W2 from their employer),  may have a home mortgage with interest, some student loan debt and maybe some childcare credits.  But for those with more complex situations, such as revenue from businesses, income from interest and dividends, capital gains on a home sale or foreign assets, seeking the expertise of a professional can save time, money and potential legal complications.

For small business owners, and many other taxpayers, there are several reasons why seeking a tax professional might be better than going it alone.  In this post, we’ll discuss some of the most common and influential drivers that typically signal it’s time to make the switch.

Types of Tax Advisors
The first thing to know is that anyone can claim to be a tax expert.  Furthermore, there is no requirement that people who prepare tax returns have to be licensed by the IRS.  With that being said, note that there are (generally) three designations when it comes to tax professionals:

  • Enrolled agent (EA).  An EA is licensed by the IRS and has either passed a difficult test or has at least five years of experience working for the IRS.  EAs are “generally” the least expensive of the tax pros and often offer bookkeeping and accounting assistance.
  • Certified public accountant (CPA) and other accountants.  CPAs are licensed and regulated by each state.  They perform sophisticated accounting and business-related tax work and prepare tax returns.  Larger businesses or businesses with complex business tax returns often use CPAs. The larger CPA firms (e.g. The Big 4) are expensive.  Smaller CPA firms and practitioners can be less expensive and may be better suited for the typical small business.
  • Tax Attorneys.   Tax Attorneys are lawyers with a special tax law degree (called an L.L.M. in taxation) or a tax specialization certification from a state bar association.  Tax attorneys can be expensive, but you should consult one if you have a tax problem, are in criminal trouble with the IRS, need legal representation in court, or need business and estate planning.

Reasons to Hire A Tax Professional
So when is the right time to hire one of the individuals listed above? Typically, it’s once one of the following items below occurs:

  • Your tax situation exceeds your expertise or your software.  Even what may seem like a “straightforward” situation can quickly turn into more than one bargained for.  For example, let’s say that you drive for one of those ride share companies.  At tax time, you receive a Form 1099-K, a Form 1099-MISC and a Yearly Summary.  Some of the documents include numbers from one of the other documents, and some documents appear to have totally different numbers.  Some have fees that “may be deductible” but you aren’t sure which ones to include.  Do you add them all?  Do you only include some?  What if you leave a number off that should have been reported?  A tax professional can help ensure everything is reported correctly and that you don’t wind up getting an IRS Automated Adjustment Notice for under reporting your income.
  • Your time is valuable and you’re spending too much of it preparing your return.  While you may be able to prepare your taxes yourself for $100 or less online, many do-it-yourself filers spend an enormous amount of time when doing so.  According to the 2018 Form 1040 Instructions per the IRS, the average taxpayer will spend 11 hours preparing their return. 
    Average Taxpayer Burden for Individuals
    Average Time (Hours)
    Type of TaxpayerPercentage
    of Returns
    Total
    Time
    Record
    Keeping
    Tax
    Planning
    Form
    Completion &
    Submission
    All
    Other
    Average
    Cost
    (Dollars)
    All taxpayers100%115241$200
    Nonbusiness70%72131$110
    Business30%1910351$400
    Estimated Average Taxpayer Burden for Individuals by Activity per 2018 Form 1040 Instructions
    This number jumps to 19 hours if you have a business!  Hiring a professional can reduce that to the time it takes to gather your tax documents and forward them to their office, go over a few items with them and then review the final return for accuracy.  If your time is better spent closing sales deals, running your business or spending it with family and friends, then hiring a tax professional can make perfect cents (pun intended).
  • You could be missing out on valuable deductions.  In addition to saving you countless hours of painfully boring and costly tax guessing, experienced preparers know the deductions that you may qualify for, and which items are tax deductible if you own a business.  They can also easily tell you if it’s more beneficial to itemize or take the standard deduction.  Even if you just earn only a little income on the side, a professional may be able to find you deductions or credits that will more than pay for their services and keep more of your hard earned money out of the pockets of Uncle Sam.  Lastly, the cost of having your taxes prepared by a professional can also be tax deductible as a professional fee if you have a business.
  • The tax law is constantly changing.  Adding to the complexity, new tax laws are enacted every year that affect virtually everyone, making it tough to keep up with changes and how they might affect you.  For example, the new 20% Qualified Business Income Deduction will no doubt cause some frustration for those this tax year (especially if you in the “phase in” range for a partial deduction).  For small businesses that have to manage income tax withholding and reporting for their employees, taxes are even more complex.  While tax software can help, an experienced professional that “has seen it all before,” and also keeps up with tax law changes through educational courses, can make the process easy peasy lemon squeezy!
  • A mistake was made in the past.  If you do your taxes yourself, you are much more likely to make a mistake.  Mistakes happen, but when they happen to you, it may feel like they are costing you big time.  A simple math error can cause a return to be inaccurate, leaving you liable for unpaid taxes and interest.  For errors the IRS believes are not accidental, such as failing to report income, taxpayers can also face large fines and even criminal prosecution.  A skilled tax professional can not only help ensure that your returns are accurately prepared, but they often can help you rectify a past mistake.
  • You want peace of mind.  The only people that look forward to an IRS audit are IRS auditors!  The best way to avoid their scrutiny is to make sure your tax return is in compliance with the tax laws.  To do that, why not hire a professional who lives, works and breathes taxes every day (or at least a lot more frequently than you do)?  There is still a chance than any taxpayer will get audited, but if you use the services of a professional CPA, Enrolled Agent or Tax Attorney, and your return is selected for further inspection by the IRS, those professionals can typically help represent you on your behalf before the IRS.  Don’t go before a court without a lawyer, and don’t go before the IRS without a professional.

How much does it cost to hire a tax professional? 
According to the 2018 survey by the National Society of Accountants, the average federal tax return in the U.S., including the tax return for the person’s state of residence, cost $294 for a professional preparer to handle if the taxpayer itemizes and $188 if they don’t.  If you own a business that needs to file a Schedule C (for business income and expenses) that will tack on $187 more.  But as outlined above, there are numerous reasons why this cost can be well worth it.

Do you need help with your business taxes this year?
If you don’t want to deal with the hassle and headache of navigating the new tax law, or simply don’t have the time, we’d be happy to assist you!  Call the office now to schedule your appointment or request your complementary tax situation analysis (valued at $197 but free if you mention this blog post).  We are a year round practice and can even help you file your state taxes no matter where you are located.
What is the 20% QBI Deduction?

In late 2017 with the passage of the Tax Cuts and Jobs Act (TCJA), a new 20% deduction for pass through businesses was created.  This deduction is also known as the section 199A deduction, the deduction for qualified business income (QBI), the 20% deduction and the pass-through deduction.  In this post, we’ll discuss who can take the deduction, how it is calculated and provide some examples to aid in ones understanding.

Who may take the section 199A deduction? Generally speaking, individuals, trusts and estates with QBI, qualified REIT dividends or qualified publicly traded partnership (PTP) income may qualify for the deduction.  This income must be derived from a qualified trade or business operated directly or through a pass-through entity.  From an “entity” standpoint, the following are those that may be able to take the deduction:

  • Partnerships
  • S-Corporations
  • Sole proprietorship’s (i.e. Schedule C filers)
  • LLCs
  • Real estate investors
  • Trusts, estates, REITs and qualified cooperatives

So as you can see, the deduction is intended for those entities that are not classified as C-Corporations.  Why?  We’ll since the TCJA cut the corporate income tax rate to a flat 21%, this was the way to replicate a similar treatment for those entities that were not structured as such.

What is QBI?  QBI is the net amount of qualified income, gain, deduction and loss from any qualified trade or business. Only items included in taxable income are counted. In addition, the items must be effectively connected with a U.S. trade or business. Items such as capital gains and losses, certain dividends and interest income are excluded.

What is not QBI?  QBI is not items used in determining net long-term capital gain or loss, dividends, interest income, reasonable compensation, guaranteed payments or amount paid or incurred by a partnership to a partner who is acting other than in his or her capacity as a partner for services

What is a qualified trade or business?   It is any trade or business other than one of the following:

  • One that is defined as a specified service trade or business (SSTB), which includes those that involve the performance of services in the fields of health, law, accounting, actuarial science, performing arts, consulting, athletics, financial services, investing and investment management, trading, dealing in certain assets or any trade or business where the principal asset is the reputation or skill of one or more of its employees.
  • One that involved performing services as an employee (i.e. one in which you receive a W2)

What information should my K1 have on it for me to take the QBI deduction?  If a K1 fails to report any item below, the IRS will presume that the QBI, W-2 wages and the unadjusted basis immediately after acquisition (UBIA) of qualified property are equal to zero:

  1. Whether the business is an SSTB.
  2. Whether there is more than one trade or business.
  3. QBI for each trade or business.
  4. W-2 wages and UBIA of qualified property.
  5. Any REIT dividends.
  6. Any PTP income.

How is the deduction for QBI calculated?  Now this is where things “can” get complicated.  In the simplest application, the deduction is equal to 20% of domestic QBI from a qualified trade or business.   The deduction is taken on an individuals personal return and “below the line.” Thus, it reduces taxable income and not adjusted gross income (AGI).  The following 199A Calculator will give you a quick idea of how it works and what a QBI deduction might look like for your situation.

The calculation itself, is dependent on the taxable income reflected on the taxpayers return:

Below threshold:  If a taxpayer’s taxable income is below $315,000 for a married couple filing a joint return and $157,500 for all other taxpayers; the deduction is the lesser of:

  1. 20% of the taxpayer’s QBI, plus 20 percent of the taxpayer’s qualified real estate investment trust (REIT) dividends and qualified PTP income or
  2. 20% percent of the taxpayer’s taxable income minus net capital gains.

So basically, the deduction will never be greater than 20% of the taxpayers QBI or their taxable income. Now what happens if the income is above the amounts specified above?

Between threshold:  If the taxpayer’s taxable income is between thresholds (i.e., between $315,000 and $415,000 for married taxpayers filing jointly; between $157,500 and $207,500 for others), the QBI deductible amount for the business is subject to a limitation based on W-2 wages and/or UBIA.  In these instances, the deduction is calculated as:

  1. 20% of QBI for that trade or business less,
  2. An amount equal to the reduction ratio multiplied by the excess amount.
    • The “reduction ratio” is calculated as (Taxable income – $315,000)/$100,000 for those filing MFJ and (Taxable income – $157,500)/$50,000 for all other taxpayers
    • The “excess amount” is the amount by which 20% of QBI exceeds the greater of:
      • 50% of Form W-2 wages paid by the business, or
      • 25% of Form W-2 wages paid by the business plus 2.5% of the UBIA

Above threshold:  If the taxpayer’s taxable income is above the thresholds (i.e., $415,000 for married taxpayers filing jointly and $207,500 for others), the deduction is:

  1. the lesser of
    • 20% of QBI for that trade or business OR
  2. the greater of
    • 50% of W-2 wages for that trade or business OR
    • 25% of W-2 wages for that trade or business PLUS 2.5% of the UBIA of all qualified property

I have income from a SSTB. How does that affect my deduction?   Your ability to take the deduction will depend on your taxable income and will be calculated as follows:

  • The limitation does not apply to any taxpayer whose taxable income is below the $315,000/$157,500 threshold amounts.
  • For taxpayers whose taxable income is within the phase-in range ($315,000 to $415,000 for joint filers and $157,500 to $207,500 for all other filing statuses), the taxpayer’s share of QBI, W-2 wages and UBIA of qualified property related to the SSTB may be limited/reduced (see Example 5  below)
  • If the taxpayer’s taxable income exceeds the phase-in range (i.e. greater than $415,000 for joint filers and $207,500 for all other filing statuses), no deduction is allowed with respect to any SSTB.

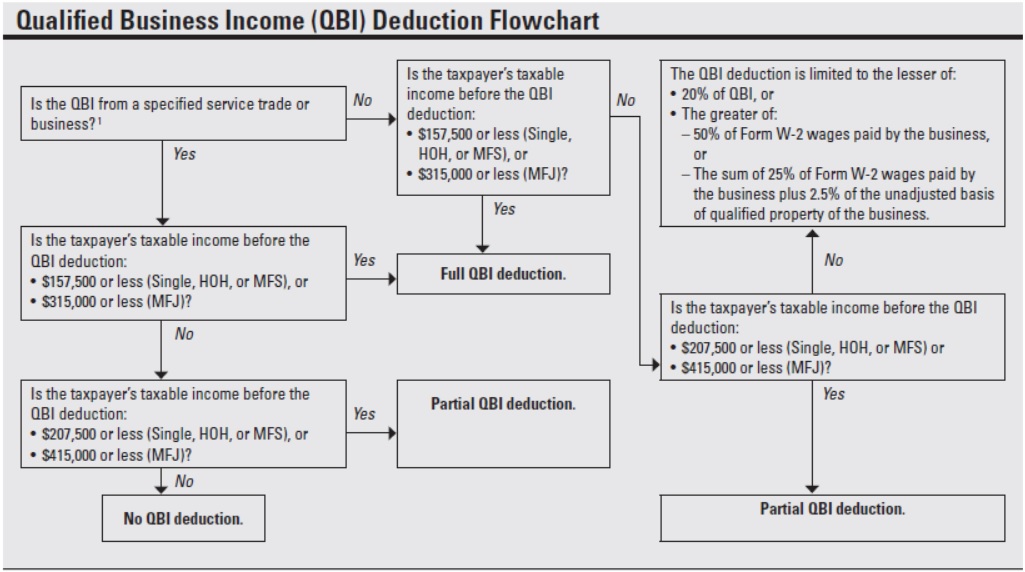
I am a visual person.  Do you have a flowchat to illustrate what all of the above means?
Ask and you shall receive.  Take a look at the graphic below (absent some of the calculations).

Calculation examples using various ranges and business types.  On August 8, 2018, the IRS released proposed regulations on §199A, providing guidance on their interpretation of provisions regarding the new 20% deduction for pass-through entities. The proposed regulations span 184 pages and provide numerous definitions, examples, and anti-abuse provisions.  As such, it’s a good idea to review the examples in the link (see page 114/184) as the IRS has outlined computations for many scenarios.

The examples shown below are designed to help you gain a general understanding of how the information presented above comes into play.

Income below threshold examples

Example 1  In 2018, Pilar, an unmarried individual, operated an accounting and tax business (a SSTB) as a sole proprietor and earned a net Schedule C income of $100,000. She did not have any capital gains or losses. She claimed the standard deduction of $12,000 so her taxable income was equal to $88,000.

Pilar’s QBI deduction is $17,600, the lesser of 20% of her QBI ($100,000 x 20% = $20,000) or her taxable income minus long-term capital gain ($88,000 x 20% = $17,600). Because she is in the lowest range, the fact that she operates SSTB is irrelevant.

Example 2  Assume the same facts as above except that Pilar had $7,000 in long term capital gains.  Pilar’s QBI deduction is $16,200, the lesser of 20% of her QBI ($100,000 x 20% = $20,000) or her taxable income minus long-term capital gain ($88,000 – 7,000 = $81,000 x 20% = $16,200).

Example 3  Popeye and Olive Oyl are married and file a joint individual income tax return.  Popeye earned $300,000 in wages as an employee for the Department of Defense in 2018. Olive Oyl owns 100% of the shares of Alessi, an S corporation that manufactures olive oil.  Alessi generated $100,000 in net income from operations in 2018.  Alessi paid Olive Oyl $150,000 in wages in 2018.  Neither Popeye or Olive Oyl have any capital gains or losses. After allowable deductions not related to Alessi (i.e. personal itemized deductions) , Popeye and Olive Oyl’s total taxable income for 2018 is $300,000.

Popeye and Olive Oyl’s wages are not considered to be income from a trade or business for purposes of the QBI deduction.  Because Alessi is an S corporation, its QBI is determined at the S corporation level.  Alessi’s QBI is $100,000, the net amount of its qualified items of income, gain, deduction, and loss. The wages paid by Alessi to Olive Oyl are considered to be a qualified
item of deduction for purposes of determining Alessi’s QBI.

The QBI deduction with respect to Alessi’s QBI is then determined by Olive Oyl, Alessi’s sole shareholder, and is claimed on the joint return filed by Popeye and Olive Oyl.  Their QBI deduction is equal to $20,000, the lesser of 20% of Olive Oyl’s QBI from the business ($100,000 x 20% = $20,000) or 20% of Popeye and Olive Oyl’s total taxable income for the year ($300,000 x 20% = $60,000).

Income within threshold examples

These limitations are phased in for joint filers with taxable income between $315,000 and $415,000, and all other taxpayers with taxable income between $157,500 and $207,500.

Example 4  Bonnie and Clyde are married and file a joint individual income tax return. Bonnie is a shareholder in Public Enemy, an entity taxed as an S corporation for Federal income tax
purposes that conducts a single trade or business (freight operations). Public Enemy holds no qualified property.

Bonnie’s share of Public Enemy’s QBI is $300,000 in 2018.  Bonnie’s share of the W-2 wages from Public Enemy in 2018 is $40,000. Clyde earns wage income from employment by an unrelated company.  After allowable deductions unrelated to Public Enemy, Bonnie and Clyde’s taxable income for 2018 is $375,000.  Bonnie and Clyde are within the phase-in range because their taxable income exceeds the applicable threshold amount, $315,000, but does not exceed the threshold, or $415,000.  Consequently, the QBI component of Bonnie and Clyde’s QBI deduction may be limited by the W-2 wage and UBIA limitations but the limitations will be phased in.

The UBIA of qualified property limitation amount is zero because Public Enemy does not hold
qualified property.  Bonnie and Clyde must apply the W-2 wage limitation by first determining
20% of Bonnie’s share of Public Enemy’s QBI.  This amount equals $60,000 ($300,000 x 20%). Next, Bonnie and Clyde must determine 50% of Bonnie’s share of Public Enemy ’s W-2 wages. This amount is $20,000 ($40,000 x 50%).

Because 50% of Bonnie’s share of Public Enemy’s W-2 wages ($20,000) is less than 20% of her share of Public Enemy’s QBI ($60,000), Bonnie and Clyde must determine the QBI component of deduction by reducing 20% of Bonnie’s share of Public Enemy’s QBI by the reduction amount.

Bonnie and Clyde are 60% through the phase-in range (that is, their taxable income of $375,000 exceeds the threshold amount by $60,000 and their phase-in range is $100,000). Bonnie and Clyde must determine the excess amount, which is the excess of 20% of Bonnie’s share of Public Enemy’s QBI, or $60,000, over 50% of Bonnie’s share of Public Enemy’s W-2 wages, or $20,000. Thus, the excess amount is $40,000.  The reduction amount is equal to 60% of the excess amount, or $24,000 ($40,000 x 60%).

Thus, the QBI component of Bonnie and Clyde’s  deduction is equal to $36,000, 20% of Bonnie’s $300,000 share Public Enemy’s QBI (that is, $60,000), reduced by $24,000. Bonnie and Clyde’s QBI deduction is equal to the lesser of (i) 20% of the QBI from the business as limited ($36,000) or (ii) 20% of Bonnie and Clyde’s taxable income ($375,000 x 20% = $75,000). Therefore, Bonnie and Clyde’s  deduction is $36,000 for 2018.

Example 5  Assume the same facts as in Example 4, except that Public Enemy was engaged in a SSTB (consulting). Because Bonnie and Clyde  are within the phase-in range, Bonnie must reduce the QBI and W-2 wages allocable to Bonnie from Public Enemy to the applicable percentage of those items as a proportion to the phase out range.  Furthermore, she must apply a reduction amount to the calculation.

The applicable percentage equals 100% minus the percentage obtained by dividing (a) the pre-QBI deduction taxable income of the taxpayer in excess of the applicable threshold amount by (b) $100,000 for joint-return filers or $50,000 for other filers.  Reduction amount means, the excess amount multiplied by the applicable percentage.  It is calculated as 20 percent of QBI over the greater of 50 percent of W-2 wages or the sum of 25 percent of W-2 wages plus 2.5 percent of the UBIA of qualified property.

For Bonnie and Clyde’s applicable percentage, their taxable income ($375,000) exceeds their threshold amount ($315,000) by $60,000.  A ratio of 60% (i.e. $60,000/$100,000) is what is used to find their applicable percentage of 40% (i.e. 100% – 60% = 40%).  Accordingly, in computing the QBI deduction, the couple would only be allowed to take into account 40% of the QBI, W-2 wages, and qualified property with respect to the trade or business.

Thus Bonnie’s QBI is “adjusted” to $120,000 ($300,000 x 40%) and her share of W-2 wages is “adjusted” to $16,000 ($40,000 x 40%).  These “adjusted”  numbers must then be used to determine how Bonnie’s QBI deduction is limited.  The deduction will be limited to the lesser of:

  • (i) 20% of Bonnie’s share of Public Enemy’s QBI or
  • (ii) the greater of the W-2 wage or UBIA of qualified property limitations.
  1. Twenty percent of Bonnie’s share of QBI of $120,000 is $24,000.
  2. The W-2 wage limitation equals 50% of Bonnie’s share of Public Enemy’s wages ($16,000 x 50%) or $8,000.
  3. The UBIA of qualified property limitation equals $0

To calculate the reduction amount Bonnie and Clyde must first determine the excess amount.  This is calculated as the excess of 20% of Bonnie’s share of Public Enemy’s QBI, as adjusted ($24,000), over 50% of Bonnie’s share of Public Enemy’s W-2 wages, as adjusted ($8,000). Thus, the excess amount is $16,000. The reduction amount is equal to 60% of the excess amount or $9,600. Thus, the QBI component of Bonnie and Clyde’s QBI deduction is equal to $14,400 ($24,000 – $9,600).

As Bonnie and Clyde’s QBI deduction is equal to the lesser of (i) 20% of the QBI from the business as limited ($14,400) or 20% of Bonnie’s and Clyde’s taxable income ($375,000 x 20% = $75,000), their QBI deduction is $14,400 for 2018.

Income above threshold examples

Example 6   Ernie, an unmarried individual, is a 30% owner of Bert LLC, which is classified as a partnership for Federal income tax purposes. In 2018, Bert LLC has a single trade or business (landscaping) and reported QBI of $3,000,000.  Bert LLC paid total W-2 wages of $1,000,000, and its total UBIA of qualified property is $100,000.  Ernie is allocated 30% of all items of the partnership.  For the 2018 taxable year, Ernie reports $900,000 of QBI ($3,000,000 x 30%) from Bert LLC . After allowable deductions unrelated to Bert LLC (i.e. personal itemized deductions), Ernie’s taxable income is $880,000.

Because Ernie’s taxable income is above the threshold amount, the QBI component of Ernie’s QBI deduction will be limited to the lesser of:

  • (i) 20% of Ernie’s share of Bert LLC’s QBI or
  • (ii) the greater of the W-2 wage or UBIA of qualified property limitations.

So while it might not be clear, there are three calculations related to the two bullets above:

  1. Twenty percent of Ernie’s share of QBI of $900,000 is $180,000.
  2. The W-2 wage limitation equals 50% of Ernie’s share of Bert LLC’s wages ($1,000,000 x 30% = $300,000 x 50%) or $150,000.
  3. The UBIA of qualified property limitation equals $75,750, the sum of:
    • (i) 25% of Ernie’s share of Bert LLC’s wages ($1,000,000 x 30% = $300,000 x 25%) or $75,000 plus
    • (ii) 2.5% of Ernie’s share of UBIA of qualified property ($100,000 x 30% = $30,000 x 2.5%) or $750.

For items 2 and 3 above, the greater of the limitation amounts ($150,000 and $75,750) is $150,000.

The QBI component of Ernie’s QBI deduction is thus limited to $150,000, the lesser of (i) 20% of QBI ($180,000) and (ii) the greater of the limitations amounts ($150,000).  Ernie’s QBI deduction is equal to the lesser of (i) 20% of the QBI from the business as limited ($150,000) or (ii) 20% of Ernie’s taxable income ($880,000 x 20% = $176,000). Therefore, Ernie’s QBI deduction is $150,000 for 2018.

Ready to get help?  As you can tell, the computations involved in taking the deduction get more complicated depending on the taxpayers income.  If you don’t want to go through the mechanics of calculating your QBID and ensuring it is correct, why not let a professional do the work?  Feel free to give us a call or drop us an email and we’d be happy to assist you ensure that everything is done correctly.  Plus, you won’t have to spend the time doing it!

What Is An Eligible Education Institution?

Do I get a tax write off for this?

The IRS provides taxpayers certain tax breaks when you pay for education.  However, there is a catch.  The monies paid (i.e. tuition) have to be to an eligible education institution.  What exactly is that?  Read on my friend.

Tax Benefits Available
The following are the benefits commonly available to taxpayers:

  • Tuition and Fees Deduction: The tuition and fees deduction can reduce the amount of your income subject to tax by up to $4,000.  You may be able to deduct qualified education expenses for higher education paid during the year for yourself, your spouse or your dependent.
  • American Opportunity Tax Credit: A credit for tuition, required enrollment fees and course material for the first four years of post-secondary education for up to $2,500 per eligible student per year. Your modified adjusted gross income (MAGI) must be under $90,000 ($180,000 for joint filers) and you must not have claimed the AOTC or the former Hope Credit for more than four tax years for the same eligible student. Forty percent of this credit may be refundable.
  • Lifetime Learning Credit: The Lifetime Learning Credit is 20% of the first $10,000 of qualified education expenses paid for all eligible students. The maximum credit is $2,000 per return regardless of the number of eligible students. There is no limit on the number of years the credit can be claimed for each student; thus the reason it is referred to as “lifetime.”

Eligible Education Institution Defined
An eligible educational institution is a school offering higher education beyond high school. It is any college, university, trade school, or other post secondary educational institution eligible to participate in a student aid program run by the U.S. Department of Education.  This includes most accredited public, nonprofit and privately-owned–for-profit post secondary institutions.

With that said, if you are attending a school in another country, there is a possibility that it is NOT considered an eligible education institution.  In general, if you aren’t sure if your school is an eligible educational institution:

• Ask your school (i.e. someone in the financial aid department) if it is, or
• See if your school is on the U.S. Federal Student Aid Code List.

TIP: A small number of schools, not on the list, may be eligible educational institutions and the school can confirm that for you.

New Book – How To Slash Your Taxes!

Filled with 111 proven topics to help you slash your tax bill!

Let’s face it, no one likes to pay more in taxes than they should.  In our office, we typically tell taxpayers that they should aim to be within +/- $1,000 with regards to their refund or having a balance due.  A balance due of $1,000 while not pleasant, is manageable for most people when it comes to paying it outright or setting up a payment plan.  Getting a refund of $1,000 or less you means that you didn’t give Uncle Sam too much of an interest free loan for a year.  Hey, it’s not called a “refund” for no reason; it’s your own money they are giving you back!

But what happens when people (i.e. taxpayers or tax preparers) push the limits to cut a tax bill?  Well, since we deal with the consequences fairly often, let’s just say that it’s usually not good.  Furthermore, it’s totally unnecessary and who has the time to keep looking over their shoulder wondering if the big, bad IRS is going to come knocking?

The point of this book is to show you that there are hundreds of ways that you can achieve tax savings while doing it both legally and ethically.  This is largely due to the complexities of the Internal Revenue Code (IRC) and all of the loopholes that have been incorporated into it over time.  This book highlights 111 topics that can help you capitalize on this fact and in turn slash your tax liability.

So no matter if you are a parent, homeowner, investor, landlord, retiree or business owner, this book has something for everyone!  Check out the video below to hear more and look below the video on ways that you can place an order.

You can also view this video on our YouTube Channel here.

How To Order Your Copy

Order directly from our office.  You can order via credit card by clicking the “Buy Now” button below.  If you select the “autographed with my custom message” option, you will be contacted post order to obtain your message.  Please note that payment processing is performed via PayPal and if you do not have an account, you can simply select the option to pay with credit or debit card at the bottom.  All orders processed via this method include Illinois sales tax as well as priority shipping via USPS.

Don’t have a credit card or simply want to pay via check?  Then please complete this HTSYTLE Order Form and return it to our office.


Please select author autograph type


Order via Amazon.  If you do not want an autographed copy, or do not want to order via our office, you can order your copy via Amazon.  Simply visit the author page for Jared R. Rogers, CPA  and complete your order that way.  You will have the choice of ordering either the paperback or Kindle edition.

How Will The New Tax Law Affect Me?

On December 22, 2017, the Tax Cuts and Jobs Act was signed into law.  It has been touted as one of the most significant overhauls to the Internal Revenue Code since the Tax Reform Act of 1986.  The new law reduces tax rates for corporations and individuals, while repealing many deductions taxpayers were accustomed to, in an attempt to “simplify” the filing of their tax returns.  This post will focus on the changes that will impact individuals.  We’ll follow it up with another that focuses on the changes for business entities at a later date.

One of the most important things to note about the changes outlined below is that many go into effect for tax years ending after January 1, 2018.  As such, most of this will not apply when you file your 2017 tax return during the 2018 filing season (i.e. the ones due 4/17/18).  With that said, under each section you will find a “planning” comment to aid you in preparing for how it may impact the tax return you file in early 2019.

Tax Brackets and Tax Rates
The new law retains the seven tax brackets that previously existed, however, the rates are now 10%, 12%, 22%, 24%, 32%, 35% and 37%. Shown below are how the brackets and rates are applied to each filing status:

Single Taxable Income

$0 to $9,525 × 10.0% minus $0.00 = Tax
$9,526 to $38,700 × 12.0% minus $190.50 = Tax
$38,701 to $82,500 × 22.0% minus $4,060.50 = Tax
$82,501 to $157,500 × 24.0% minus $5,710.50 = Tax
$157,501 to $200,000 × 32.0% minus $18,310.50 = Tax
$200,001 to $500,000 × 35.0% minus $24,310.50 = Tax
$500,001 and over × 37.0% minus $34,310.50 = Tax

Married Filing Joint & Qualified Widow(er) Taxable Income

$0 to $19,050 × 10.0% minus $0.00 = Tax
$19,051 to $77,400 × 12.0% minus $381.00 = Tax
$77,401 to $165,000 × 22.0% minus $8,121.00 = Tax
$165,001 to $315,000 × 24.0% minus $11,421.00 = Tax
$315,001 to $400,000 × 32.0% minus $36,621.00 = Tax
$400,001 to $600,000 × 35.0% minus $48,621.00 = Tax
$600,001 and over × 37.0% minus $60,621.00 = Tax

Married Filing Seperate Taxable Income

$0 to $9,525 × 10.0% minus $0.00 = Tax
$9,526 to $38,700 × 12.0% minus $190.50 = Tax
$38,701 to $82,500 × 22.0% minus $4,060.50 = Tax
$82,501 to $157,500 × 24.0% minus $5,710.50 = Tax
$157,501 to $200,000 × 32.0% minus $18,310.50 = Tax
$200,001 to $300,000 × 35.0% minus $24,310.50 = Tax
$300,001 and over × 37.0% minus $30,310.50 = Tax

Head of Household Taxable Income

$0 to $13,600 × 10.0% minus $0.00 = Tax
$13,601 to $51,800 × 12.0% minus $272.00 = Tax
$51,801 to $82,500 × 22.0% minus $5,452.00 = Tax
$82,501 to $157,500 × 24.0% minus $7,102.00 = Tax
$157,501 to $200,000 × 32.0% minus $19,702.00 = Tax
$200,001 to $500,000 × 35.0% minus $25,702.00 = Tax
$500,001 and over × 37.0% minus $35,702.00 = Tax

Standard Deduction
The new law doubled the amount of the previous standard deduction to the following amounts:

Standard Deductions Per Filing Status

Single or Married Filing Seperate$12,000
Married Filing Jointly of Qualifying Widow(er)$24,000
Head of Household$18,000
Additional age 65 or older, or blind, per person, per event:
MFJ, QW or MFS$1,300
Single or HOH$1,600
Dependents. The standard deduction is the greater of $1,050
or earned income plus $350, up to regular standard deduction

Planning Comment: If you previously  itemized, you may no longer need to due to these increased amounts.  Remember, the IRS lets you take the standard or itemized deduction, whichever is greater.  With that being said,if your itemized deductions (discussed below) do not exceed these amounts, your tax filing just “theoretically” became more simple.

Personal Exemptions
The personal exemption has been repealed and will not be available after tax year 2017.

Planning Comment: If you have a large family and moderate income, this change might hurt you.  Because you will no longer receive an exemption for every member of your household listed on your return (which lowers your taxes), you could see your tax bill increase.

The Alternative Minimum Tax (AMT)
The phaseout thresholds have been increased to $1,000,000 for those filing as married filing joint, and $500,000 for all other taxpayers (other than estates and trusts). These amounts are indexed for inflation.

Alternative Minimum Tax (AMT) Exemptions

Individual$70,300
Married Filing Jointly & Surviving Spouses$109,400
Married Filing Separately$54,700

Itemized Deductions
With the exception of the items outlined below, all other itemized deductions are repealed. The overall limitation on itemized deductions for upper income individuals is also repealed.

  • Medical Expenses:  For 2017 through 2018, expenses exceeding 7.5% of income are deductible.  This percentage increases to 10% in 2019.
  • State and Local Taxes (SALT): Taxpayers can claim up to a $10,000 deduction for a combination of state and local income tax, sales tax, or real estate taxes.  Foreign real property taxes are no longer deductible.
  • Mortgage Interest:  The deduction for mortgage interest is capped at $750,000 of debt, but is still allowed on a first or second home.  The interest on home equity loans will no longer be deductible.  Interest on up to $1 million of acquisition debt for loans entered into prior to December 15, 2017 is grandfathered and still deductible.
  • Charitable Contributions: Taxpayers who are able to itemize deductions can still include charitable contributions. The current limitation to 50% of income is increased to 60%.
  • Casualty Losses: Deductions for unexpected losses to personal property are no longer deductible unless covered by specific federal disaster declaration.
  • Wagering Losses: The meaning of losses from wagering transactions (i.e. gambling) is clarified to include other expenses incurred by the individual in connection with the conduct of that individual’s gambling activity (e.g. travel expenses to or from a casino).

Planning Comment: There are two big changes/challenges in this area.  First, since the SALT deduction is capped at $10,000, that means that you have to close a gap of anywhere between $2,000 – $14,000 to keep itemizing depending on your filing status.  As such, we suspect that single homeowners may still find themselves itemizing, but those filing as married filing joint may not (unless they pay a significant amount of mortgage interest).

The second area revolves around the removal of the items that were subject to a 2% floor of your income.  So, if you previously deducted any of the items listed below, know that you will not be able to claim them after filing your 2017 tax return:

  • work-related travel, transportation, meal, and entertainment expenses
  • depreciation on a computer or cellular telephone your employer requires you to use in your work
  • dues to a chamber of commerce (or professional societies) if membership helps you do your job
  • education (work-related)
  • home office expenses for part of your home used regularly and exclusively in your work
  • legal fees
  • subscriptions to professional journals and trade magazines related to your work
  • tools and supplies used in your work
  • union dues and expenses
  • work clothes and uniforms (if required and not suitable for everyday use)
  • tax preparation fees

Child Tax Credit
The child tax credit will increase to $2,000 per qualifying child and will be refundable up to $1,400 (subject to phaseouts).   Phaseouts, which are not indexed for inflation, will begin with adjusted gross income of more than $400,000 for those filing as married filing jointly or $200,000 for all other taxpayers.

Non-Child Dependent Credit
A new $500 non-refundable credit covers dependents who don’t qualify for the child tax credit, such as children who are age 17 and above or dependents with other relationships (such as elderly parents). You can’t claim the credit for yourself (or your spouse under married filing jointly status).

Kiddie Tax
The kiddie tax applies to unearned income for children under the age of 19 and college students under the age of 24. Unearned income is income from sources other than wages. Taxable income attributable to net unearned income will be taxed according to the brackets applicable to trusts and estates. The rules for tax applicable to earned income are unchanged.

Student Loan Interest Deduction
For 2018, the maximum amount that you can deduct for interest paid on student loans remains at $2,500. Phaseouts apply for taxpayers with modified adjusted gross income (MAGI) in excess of $65,000 ($135,000 for joint returns) and is completely phased out for taxpayers with modified adjusted gross income (MAGI) of $80,000 or more ($165,000 or more for joint returns).

Section 529 Plans
Distributions of up to $10,000 per beneficiary can be used for tuition expenses for public, private or religious elementary or secondary school. The limitation applies on a per student basis rather a per account basis. Distributions can also be made for expenses related to homeschool.

Discharged of Student Loan Indebtedness
The exclusion from income resulting from the discharge of student loan debt is expanded to include discharges resulting from death or disability of the student.

Educator Expenses
The bill retains the present law above-the-line deduction of $250 (indexed for inflation) for out-of-pocket expenses.

Bicycle Commuting Reimbursement
The exclusion from gross income and wages for qualified bicycle commuting reimbursements up to $20 is suspended.

Moving Expense Deduction
Moving expenses related to a job change are no longer deductible except for active members of the military.

Alimony
Beginning with divorces in 2019, alimony payments to an ex-spouse are no longer deductible and not taxable to the recipient.

Affordable Care Act
The penalty for failing to maintain minimum essential coverage for individuals (individual mandate) is repealed beginning in 2019.

Estate Tax Exemption
The estate and gift tax exemption is doubled for estates of decedents dying and gifts made after December 31, 2017, and before January 1, 2026.  The exemption increases to $11,200,000 in 2018. The generation skipping transfer (GST) tax exemption is also doubled.

Changes To Be Aware Of When Filing Your 2017 Tax Return

The U.S. tax code is constantly being modified,  which means that each new filing year brings changes that taxpayers need to remember when filing their tax return.  So what changes took place last year, and how will they impact the filing of your tax year (TY) 2017 federal tax return? Read on my dear friend.

Two extra days to file
This change is probably most important to all those procrastinators out there.  April 15th is the traditional day in which we’re all supposed to file our tax return. But this year, filing day has been pushed back to April 17th due to the combination of a weekend and a Washington, D.C. holiday.

The usual April 15th deadline falls on a Sunday this year.  Normally, taxpayers would have to file their tax returns by the following Monday, which would be April 16th.  But the D.C. holiday Emancipation Day is held on Monday, April 16th.  Since Federal law states that Washington, D.C. holidays impact tax deadlines the same way federal holidays do, that gives taxpayers across the country yet even another extra day to file.

Inflation adjustments
For TY 2017, the IRS increased the value of some different tax benefits:

  • The standard deduction was increased to $6,350, $9,350 and $12,700 for those using the single, head of household and married filing jointly filing statuses respectively
  • The maximum earned income tax credit (EITC) rises to $6,318
  • The maximum income limit for the EITC rises to $53,930
  • The foreign earned income deduction rises to $102,100

You might need a driver’s license or state ID to file electronically
Tax fraud has become a growing problem over the years.  To combat this, many states are now requesting or even requiring that taxpayers provide their driver’s license or state ID information if they want to file their state tax returns electronically.  You’ll still be able to submit your state tax returns electronically without providing this information, but doing so might trigger a manual review by your state to verify your identity. This means it could take longer to receive any refund  you are entitled to if you don’t provide this information.

Refunds will be held for those claiming EITC or ACTC until mid February
The IRS will not issue refunds for people claiming the EITC or Additional Child Tax Credit (ACTC) before mid-February. The law requires the IRS to hold the entire refund, even the portion not associated with EITC or ACTC.  Per the IRS, they expect the earliest EITC/ACTC related refunds to be available in taxpayer bank accounts or debit cards starting on February 27, 2018, if direct deposit was used and there are no other issues with the tax return.  This law change, which took effect at the beginning of 2017, helps ensure that taxpayers receive the refund they’re due by giving the IRS more time to detect and prevent fraud.

The IRS will not accept e-filed returns without indicating health coverage compliance
The IRS has stated that it  will not accept electronic tax returns from individuals who do not address the health coverage requirements of the Affordable Care Act (ACA). The IRS will accept electronic returns only when taxpayers indicate whether they had health insurance, had an exemption, or will make a shared responsibility payment.  The good news is that the penalty amounts remain the same for TY 2017.

The floor to deduct medical expenses has been lowered to 7.5 percent of AGI
The threshold for unreimbursed medical expenses increased from 7.5 percent to 10 percent of Adjusted Gross Income (AGI) for most taxpayers in 2014. There was a temporary exemption from January 1, 2013 to December 31, 2016 that allowed individuals age 65 and older and their spouses to still use the lower 7.5 percent floor.  However, due to the Tax Cuts and Jobs Act of 2017, all taxpayers are now subject to the decreased threshold of 7.5 percent.

Mileage
Do you use your car for business or work?  Well, the standard mileage rate dropped to 53.5 cents per mile, down from 54 cents for 2016.  The rate used for medical and moving mileage drops to 17 cents per mile, down from 19 cents in 2016.  If there is a bright spot, the charitable mileage rate remains unchanged at 14 cents per mile.

Tuition and fees deduction eliminated
This above the line deduction expired at the end of 2016.  While there is a bill proposed by the Senate Finance Committee to “extend” this and other expired tax provisions, it hasn’t been passed as of the writing of this post.  With that being said, you can no longer take a “deduction” for tuition or qualified fees you pay on behalf of yourself or your dependents.  However, the American Opportunity Tax Credit and the Lifetime Learning Tax Credit are still available.  Just noted that they are subject to phase-out limits and some other restrictions that prevent all taxpayers from claiming them.

Exclusion of foreclosure debt forgiveness from income eliminated
Another big change is the elimination of the tax code provision that allowed taxpayers who had discharged indebtedness related to home foreclosure to exclude it from their income.  The qualified principal residence indebtedness exclusion allowed individuals to exclude discharged debt from being reported as income. However, similar to above, this provision expired at the en of 2016 and is another item included in the extender bill mentioned above.

Time running out to claim your TY 2014 refund
April 17, 2018, is the last day to file your 2014 tax return to claim a refund. If you miss the deadline, your refund goes to the U.S. Treasury instead of to you. You also lose the opportunity to apply any refund dollars to another tax year (e.g. 2015, 2016, etc.) in which you owe income tax.

You might need to renew your ITIN if you have one
The 2015 Protecting Americans from Tax Hikes (PATH) Act provided that an Individual Taxpayer Identification Number (ITIN) would expire if an individual fails to file a tax return (or is not included as a dependent on another’s tax return) for three consecutive years.  Under this new rule, taxpayers who have an ITIN that has not been used at least once in the past three years will no longer be able to use that ITIN on a tax return as of January 1, 2017.   Additionally, individuals who were issued ITINs before 2013 are now required to renew their ITINs on a staggered schedule between 2017 and 2020.  So, if any of the above situations apply to you and you need to file a tax return in 2017, you may need to renew your ITIN if it has expired.

Foreign financial disclosures
If you are a U.S. resident, you have to file information about your foreign holdings if they exceed $50,000 at year-end, if you’re a single filer.  Foreign holdings exceeding $75,000 at any point during the year must also be reported. For those who are married filing jointly, the limits rise to $150,000 at any time, and $75,000 at year-end.

For U.S. citizens living abroad, the reporting limits rise substantially. Single filers need only report accounts exceeding $200,000 at year-end, or $300,000 at any point during the year. For joint filers, the limits are $400,000 at year-end, or $600,000 at any time during the year.

Joint mortgage, but only one SSN on 1098?

What's mine is yours and what's yours is mine!

What’s mine is yours and what’s yours is mine!

So maybe you purchased a home with your fiance, spouse, parents, friend or business partner.  Each of you pays half (or some other portion) of the mortgage throughout the year.  When it comes time to file your taxes, you plan to file a return separate from the other person, but there is just one problem.  Then 1098 that was provided either list both of your names and the other persons SSN OR it simply just list the other parties information all together.  So how do you go about claiming your piece of what is reported on the 1098?

Figure Your Share
If you and another party (or multiple parties) were liable for, and make payments towards, a mortgage in which another party received the Form 1098, the first thing you must do is figure out each party’s share.   Technically the person that received the From 1098 should do this and provide the amounts to you, but in reality either party may do it.  So, for example, if each person paid 50% of the payments that yielded $9,825 of interest being reported on the Form 1098, then each one is entitled to deduct $4,912.50 on their tax return.

Attach A Statement To Your Return
To report the $4,912.20 of mortgage interest paid, each person should attach a statement to their tax return explaining this. Show how much of the interest each person paid, and give the name and address of the person who received the form. Your share of the interest is then reported on Schedule A (Form 1040), line 11, along with the words “See attached” next to the line.  The person may also deduct their share of any qualified mortgage insurance premiums on Schedule A (Form 1040), line 13.  If the property in question is a rental property, then you can follow the same procedures stated above, but enter “See attached” on line 12 of Schedule E.

For more information on the above, or reporting home mortgage interest in general, see Publication 936; Home Mortgage Interest Deduction  and refer to the section “How To Report.”


How To Report A 1099-A

short sale

If you borrow money from a lender to purchase a property, the lender may require the loan to be secured by the purchased property.  If the lender later acquires the secured property from you or has reason to know that you abandoned or stopped using the secured property, the lender may send you a Form 1099-A (PDF), Acquisition or Abandonment of Secured Property.  So just how do you then use this from to report the sale to the IRS?  What types of tax consequences are involved?  Is there different treatment if the form is issued in connection with you principal residence versus a rental property?  Read on to find out.

Property Sales and Capital Gains
When a property is foreclosed or abandoned, it is treated as a sale from a tax standpoint. This means that one will have to calculate what their gain or loss on the disposition of the property is.  This is usually calculated by taking the sales price and subtracting the cost (or basis) in the property.  The only problem is that unlike a normal sale, there’s no “selling price”  with regards to what the lender paid to buy the property back from you.  This is where Form 1099-A comes into play.

The Information on Form 1099-A
Form 1099-A provides you with the date of sale and the “selling price” of the property.  Taxpayers will use either the fair market value of the property or the outstanding loan balance on the property for the selling price.  Both these figures are reported on the form.

  • If the loan is recourse (one where the borrower is personally liable for the balance), the sales price will be the lesser of outstanding debt reduced by any amount for which the taxpayer remains liable, or FMV of property
  • If the loan is non-recourse, the sales prices will be the full amount of debt regardless of the FMV of property

While this is not an absolute indicator, the loan was probably a recourse loan if the bank has checked “yes” in Box 5, which asks “Was borrower personally liable for repayment of the debt?”

Reporting the Sale
Assuming the foreclosed/abandoned property was your personal residence, you must prepare and file Form 8949 and Schedule D with your tax return. Use the date of the foreclosure in Box 1 of the 1099-A as your date of sale. Then indicate the selling price. This will be either the amount in Box 2 or the amount in Box 4.

Calculate your gain by comparing the “selling price” you used to your purchase price, which is your cost basis in the property. The purchase price and date can be found on the HUD-1 closing statement you received when you purchased the property. The difference between the selling price and your cost basis is your gain or loss.  However, if you have a gain, you  may be able to exclude it so that it’s not taxable.  If you have a loss, it will be considered a a “non-deductible loss” because it is personal in nature.  The following post will go into greater detail.

Investment Properties
If the foreclosed property was used as a rental, then you will need to use Form 4797. For those who have had a rental property foreclosed upon, we advise them to seek assistance from a tax professional because there are additional factors to take into consideration, such as depreciation recapture, passive activity loss carryovers and reporting any final rental income and expenses on Schedule E.

Do You Need Help Reporting Your 1099-A?
If you’ve received a form 1099-A and don’t feel like dealing with the hassle of reporting it, why not give us a call?  We’ve handled this situation numerous times and would be happy to assist you.  Just shoot us an email via the address below or call us at 773-239-8850.

Discharging Taxes In Bankruptcy

bankruptcy

Sometimes a taxpayer finds themselves in the position where they can’t pay their tax liability.  Those taxpayers may come to us and ask us if they qualify to have their taxes discharged in bankruptcy.  Our reply is that while we do help taxpayers deal with resolving their tax debt, they are best advised to consult with an attorney to investigate the bankruptcy option.  You see, only legal counsel, or someone admitted to practice before the tax court, can represent a taxpayer in tax court.  With that being said, we typically help taxpayers with administrative tax resolution methods, which the client should pursue first. These include innocent spouse relief, a request for abatement of penalties, an installment agreement or an offer in compromise (OIC).

However, if those options are insufficient, bankruptcy may be the best way for a taxpayer to either secure a reasonable payment plan (Chapter 11 or Chapter 13) or to liquidate their assets to pay off all or a portion of their tax debt (Chapter 7). Using administrative tax resolution methods help a taxpayer avoid having a “black mark” on their credit history. However, a federal tax lien listed on the debtor’s credit report may damage their credit rating just as much as a bankruptcy notation.  Needless to say, if you think you may qualify based on the information shown below, one is advised to contact an attorney who specializes in bankruptcy law.

What tax debts may be discharged in bankruptcy?
To be dischargeable, individual income tax liabilities must meet the following “technical” rules of 11 USC §§ 523(a)(1) and 507(a)(8):

  • More than three years must have elapsed since the tax return generating the liability was due, including extensions.
  • The tax return must have been filed more than two years earlier than the bankruptcy petition (generally applicable to late-filed returns). Note, however, that IRS-prepared substitute for returns (SFRs) are not considered filed returns for this purpose, and thus a tax liability assessed from them would not be subject to discharge (IRC § 6020(b)).
  • At least 240 days must have elapsed since the date of an IRS assessment (generally applicable to audit adjustments and amended returns). This time frame is extended by an OIC.

Bankruptcy Basics
A bankruptcy court filing immediately stops the collection efforts of all creditors, including the IRS. This legal protection is called the “automatic stay.” At the end of the proceedings, some or all of the petitioner’s debts—including, in some instances, tax liabilities—may be discharged, meaning they are eliminated or no longer legally enforceable. There are two types of bankruptcy:

Liquidation.   A filing under Chapter 7 liquidates assets that are not exempted under federal or state law and distributes pro rata amounts to unsecured creditors. (Keep in mind that proceeds from the forced sale of nonexempt assets in a liquidation bankruptcy may be significantly less than in an arm’s-length transaction outside of bankruptcy.) Any unsecured debts remaining after such distribution are discharged, including certain tax debts. The court forces all creditors (including the IRS) to accept the proceeds of the liquidation in full settlement of all dischargeable liabilities included in the petition. However, a tax lien recorded before the bankruptcy was filed survives the bankruptcy to the extent it attaches to property owned by the debtor at the time of the bankruptcy. Eligibility for a Chapter 7 bankruptcy is limited to debtors whose income is below a “means tested” amount or whose “non-consumer” debts exceed their “consumer” debts.

Deferred payment plans. This type of filing (Chapter 11 for individuals or Chapter 13 for businesses) forces a payment plan on debtors through a trustee. Creditors (again, including the IRS) must accept an installment schedule that pays at least as much of the dischargeable debt as would have been paid in a Chapter 7 proceeding, and which fully pays all secured and priority creditors within five years (11 USC § 1322). Nondischargeable taxes are often priority debts, which must be paid in full over the life of the plan. To qualify for Chapter 13, the debtor must have a steady stream of income: Wages, Social Security, pension payments and receipts of an independent contractor all qualify.

The key takeaways?

  • In order to be dischargable in bankruptcy, the taxes generally have to be “old” in nature.
  • The primary “tax-related” downside to filing for bankruptcy protection is the additional collection time it allows the IRS. Once taxes are assessed, the IRS normally has a total of 10 years to collect them, along with penalties and interest. Therefore, once a bankruptcy case is over, the IRS will retain whatever time remained on the original 10 years, plus the time the bankruptcy case was pending, plus an additional six months (IRC 6503(h)(2)).
Go to Top